
In short
The Disciplined Investor Podcast - Episode #955 Summary
Episode Overview Title: TDI Podcast: The Probability Payoff Description: A deep dive into the current market trends, untapped opportunities in Venezuela's oil sector, and a discussion with Todd Tresidder from FinancialMentor.com.
---
Key Themes and Topics
- Market Trends
- Early 2026 Outlook:
- The episode opens with a positive outlook for the markets in January 2026.
- Discussion on recent developments in sectors like defense due to geopolitical tensions.
- Venezuela Oil Sector
- Untapped Opportunities:
- Venezuela has the largest oil reserves (approximately 300 billion barrels).
- Potential for U.S. companies to enter the Venezuelan market amid discussions of regime change.
- Concerns Raised:
- Historical failures of U.S.-led regime changes in other countries (e.g., Libya, Iraq).
- Risks of instability and humanitarian crises following such interventions.
- Investment Implications:
- The oil sector may yield high returns, but significant political, financial, and environmental challenges exist.
- Employment and Productivity Insights
- Productivity Data:
- Recent productivity numbers showed significant growth (4.9% vs. 2.5% expected).
- Decrease in unit labor costs indicates increased efficiency in production.
- Technological Advancements:
- The role of technology, AI, and automation in driving productivity and reducing costs.
- Discussion with Todd Tresidder
- Financial Education:
- Todd emphasizes the importance of understanding financial principles and the math behind investments.
- Discourse on the difference between probability and expectancy in investments:
- Expectancy = Probability x Payoff.
- Investment Strategies:
- Challenges conventional wisdom around “buy and hold” strategies and emphasizes the significance of tactical asset allocation.
- Highlights the importance of risk management in determining safe withdrawal rates from portfolios.
Key Takeaways from Todd’s Insights
- Volatility Tax: The impact of volatility on investment returns and safe withdrawal rates.
- Tactical Asset Allocation: Focus on managing volatility can enhance compound growth and improve safe withdrawal rates significantly.
- Misleading Financial Myths:
- The podcast criticizes common myths like the “4% Rule” and “10 Best Days” investment strategies as oversimplified and potentially misleading.
---
Conclusion The podcast episode underscores current market opportunities and challenges, particularly in the oil sector, while providing listeners with advanced insights into investment strategies and financial education. Todd Tresidder's discussion revolves around the importance of understanding the mathematics behind financial decisions and the risks associated with conventional investment advice.
---
Recommended Actions
- For Investors:
- Evaluate potential investments in the energy sector with caution.
- Consider the implications of market volatility and historical valuations on retirement planning.
- For Financial Education:
- Explore resources offered at FinancialMentor.com to deepen understanding of wealth planning and investment strategies.
---
Additional Resources
- [FinancialMentor.com](http://FinancialMentor.Com) - For deeper insights and courses on financial planning.
- [The Disciplined Investor Website](http://thedisciplinedinvestor.com) - For more episodes, strategies, and investment advice.
Disclaimer: This podcast is for informational purposes only and does not constitute personalized investment advice. Always consult a qualified financial advisor before making investment decisions.
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOMarket Updates and Trends
1:19 to 2:20
Discussion on recent market trends and the defense sector's growth.
“If you're looking for a portfolio manager, look no further.”
Venezuela's Oil Opportunities
2:20 to 3:17
Analyzing the implications of Venezuela's oil situation on the market.
“But some of the things that were in the news over the last couple of months, it's like, just disappeared.”
Productivity and Labor Costs Analysis
3:17 to 5:54
Exploration of productivity numbers and their impact on labor costs.
“I mean, there was things in the background going on.”
Technological Impact on Labor
5:54 to 7:03
Examining how technology affects productivity and job markets.
“Put a pin in it for a second because I want to talk about unit labor costs that came out just at the same time.”
U.S. Involvement in Venezuela
7:03 to 9:39
Discussing the consequences of U.S. intervention in Venezuela.
“Now, unless we see something very different from these two-month numbers or the quarterly, but the two months that we've seen changing, there is something to look at there.”
Global Precedents and Future Risks
9:39 to 11:47
Assessing the implications of U.S. actions in Venezuela on global politics.
“thinking that is historically unsupported.”
Investment Opportunities in Venezuela
11:47 to 14:01
Exploring potential investment avenues in the wake of Venezuelan changes.
“the issues about Taiwan, a bit different.”
Investing in Venezuela: Opportunities and Risks
14:01 to 17:05
Explore the complexities and potential of investing in Venezuela amidst its political and economic challenges.
“and they still have a significant leverage over Venezuelan assets and even, I would dare say, probably decision-making.”
The Potential of Venezuelan Oil Reserves
17:06 to 20:08
Understand the significance of Venezuela's oil reserves and the hurdles to investment.
“government, I think is going to be hard-pressed to do.”
Todd's Focus on Financial Education
21:49 to 22:36
Hear about Todd's mission to educate others on financial issues and wealth creation.
“Yeah, just working away, building out courses.”
Show all 29 chapters
The Misunderstanding of Investment Strategy
22:37 to 24:14
Discuss the difference between intuitive probability and mathematical expectancy in investing.
“a lot of times, like the beginning of the show, I talked about defense stocks.”
The Importance of Expectancy Mathematics
24:15 to 28:00
Learn why expectancy mathematics is crucial for understanding investment returns.
“But what really drives investment returns and it's counterintuitive is it's expectancy mathematics, right?”
Understanding Investment Confidence and Client Reality
28:00 to 28:55
Explore the complexities of client confidence in investment and the statistical realities that influence their decisions.
“It tells them, hey, you're 95 % confident you're not going to fail.”
The Flawed Premise of Modern Portfolio Theory
28:55 to 29:59
Delve into the historical context of modern portfolio theory and its implications on investment strategies.
“No, it's interesting because, you know, I think I think I get to the bottom, get to the bottom of some of this where you talk about the financial myths.”
The Illusion of Historical Optimization
29:59 to 33:22
Learn about the misconceptions surrounding the use of historical data for portfolio optimization and its limitations.
“because this is a great example what you're bringing up, right?”
Shifts in Diversification Strategies
33:22 to 35:36
Examine how recent economic shifts necessitate changes in investment diversification strategies, including the rise of gold.
“I actually attended, back then, I was a bit of a geek when it came to this stuff because I was really interested in it, and I spent time with Brinson B.”
Reassessing Financial Myths in Investment
35:36 to 36:43
Critique popular financial myths and explore the truth behind investment strategies based on market volatility.
“And that's why you hear a lot now about people talking about a 60-20-20 portfolio, the other 20 being gold.”
The Misconception of Market Timing
36:43 to 41:26
Discuss the common misconceptions around market timing and the importance of understanding volatility in investment.
“But anyway, and so all of a sudden they're talking about a 60-20-20 to replace the 60-40.”
Tactical Asset Allocation Explained
41:26 to 42:05
Discover the principles of tactical asset allocation as a strategy that can effectively manage investment risks without predicting the future.
“The truth is volatility clusters, right?”
Understanding Market Timing and Tactical Asset Allocation
42:05 to 44:26
Learn the key distinctions between market timing predictions and tactical asset allocation strategies.
“So any investment strategy predicated on a prediction of the future, the market will go up.”
The Safe Withdrawal Rate Explained
44:26 to 46:04
Discover how the safe withdrawal rate is determined and its implications for retirement planning.
“So all these guys are trying to predict the future, right?”
The Impact of Volatility on Returns
46:04 to 48:21
Understand how return volatility affects withdrawal rates and investment strategies.
“I'm going to go down with the last dollar in my coffin.”
Tactical Asset Allocation and Financial Outcomes
48:21 to 50:46
Explore how tactical asset allocation can enhance safe withdrawal rates and financial flexibility.
“So if you want to narrow the gap between your safe withdrawal rate and your compound growth, you have to narrow the volatility of returns.”
Navigating Conventional Wisdom in Investing
50:46 to 53:08
Learn about the pitfalls of conventional wisdom in investing and the importance of critical thinking.
“I mean, I was trying to really keep it on the low here, you know.”
The Importance of Financial Education
53:08 to 56:06
Understand the significance of financial education in making informed investment decisions.
“misunderstandings of reality but they they intuitively appeal to people they make sense And they use the numbers close enough to reel that it takes an expert to take it apart and show why it matters.”
Understanding Financial Literacy and Fraud Detection
56:06 to 58:08
Learn how financial education empowers individuals to identify fraud and make informed decisions.
“I'm talking about as you are learning the, and understanding the basics so that they could do really good things for themselves and their family.”
Real-World Examples of Financial Fraud
58:08 to 1:00:06
Explore notable cases of financial fraud and learn how to recognize warning signs.
“the yields go up on, well, no, that's not going to happen.”
Valid Investment Strategies vs. Fraudulent Claims
1:00:06 to 1:02:38
Discover the difference between legitimate investment strategies and fraudulent claims in finance.
“just by understanding how this stuff works.”
The Importance of Financial Education and Planning
1:02:38 to 1:04:35
Understand the significance of a strong financial education and planning for long-term success.
“And if you think you don't need it because you have a financial advisor's financial plan, think again.”
Transcript
Automatic transcript. May contain errors.0:00This episode is brought to you by Interactive Brokers. And will the U.S. unemployment rate exceed 4.5 % in January 2026? At IBKR Forecast Trader, the yes was recently at 33 % and the no was at 65%. With Interactive Brokers Forecast contracts, you can trade on future events like climate change, the economy, or even politics. You choose yes or no. And if you're right, you get paid. It's that simple. Explore trending data, spot the trends, and make your prediction. Trade forecast contracts at interactive brokers and earn a dollar for every correct prediction. Plus, you'll earn 3.14 % APY on your investment with an interest-like incentive coupon.
0:45And you'll get$3 for signing up with Forecast Trader, which you can use for any purpose or to start trading. Forecast contracts are not suitable for all investors. Go to ibkr.com slash forecast and start predicting today. The last trading day for this contract is February 6th, 2026. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast.
1:18Todd Tresidder:This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz & Company, from seed through harvest, cultivating financial success.
1:37Capturing Maduro and buying Greenland, all in a day's work. Markets off to a great start this year, but there's plenty of January to go. And Venezuela oil, untapped opportunity, but let's take a closer look. and our guest today, Todd Treseter, founder of financialmentor.com. All this and much more on episode number 955 of the Disciplined Investor Podcast.
2:13And we're back at it in full swing. Vacation time is over. No time to rest. As the information comes fast, it's like trying to take a sip from an open fire hydrant these days. I mean, last week, we spent a good time talking about one thing, and all of a sudden this week, it's amazing how it's almost like that doesn't exist anymore, although this week there's a few things that do exist that are carryover. But some of the things that were in the news over the last couple of months, it's like, just disappeared. That is the news cycle that we're living in right now. Now, listen, last week we spent a good amount of time talking about why the defense sector could be a great place to look at for 2026.
2:54And honestly, that timing is as good as it gets. We nailed it. As John C. Dvorak would say, we nailed it. The reality is that we didn't think that something was going to break this quickly. How would we have known of anything going on in Venezuela? I mean, there was things in the background going on. And, of course, the various ships that were seized and the boats that were blown up. All that, of course. But the action in Venezuela and the talk about Greenland and President Trump nonchalantly saying that the military budget should be increased from$1 trillion to$1.5 trillion in 2027. That put an absolute fire under the shares of the sector, the defense sector, and in particular, the names we mentioned on last week's episode.
3:50Those things are on fire. And yes, we did buy those for our clients. And it has been an unbelievable run just in the short, I don't know, five, six days that it's going on. I want to talk about something that's kind of interesting and then get into something that I have been thinking about And it took me a few days to really flush it out And get to my thoughts on it, which was Venezuela And the idea that all of a sudden we're going to have all this oil and all things that are just great And oil prices are going to collapse And we're going to get all these riches and start all up But we'll get to that in a second because there are some things in there and the concept of what is being talked about by many of the politicians that are on the side of this wondrous opportunity that is very reminiscent and rings many bells of something that happened other times in history that didn't really play out as expected.
4:51And everything is tracking very closely. We'll get to that in one second. I want to talk about something that I thought was really interesting, though, a data point that was released this week. Forget about the employment stuff. That was all exciting and all from the initial claims, jobless claims and the ADP numbers and all that. I want to talk about the productivity numbers. The preliminary quarter three productivity numbers came in at 4.9 % versus 2.5 % expected. And productivity measures the output per hour worked, right? So this jump from what was expected and almost double the consensus to 4.9 % is suggesting that businesses are producing much more per labor hour than is expected or that was expected.
5:40Wow, how is that? Kind of interesting. Now, the prior was also revised up from 3.3 % to 4.1%. So the trend is strengthening on top of an incredible number to begin with. Now, hold that thought. Put a pin in it for a second because I want to talk about unit labor costs that came out just at the same time. The preliminary quarter three was at a negative 1.9 % versus the 0.8 % positive consensus. Oh, my. Think about that. Because unit labor costs, they measure the labor cost per output, right? So a negative number means that costs are falling. That makes sense. The prior reserve is revised down even more to negative 2.9 % from a plus 1%.
6:32So costs have been dropping sharply somehow. Could it be due to, I don't know, things like technology, adoption, AI, automation maybe, efficiency improvements? Of course, I mean, we had all of this going on post-pandemic, right? The idea that restructuring leaner operations may have boosted output without adding any labor. Now, when you combine both things, the productivity and the unit labor costs, what you're finding is that something is going on in the background. The idea that maybe technology and, dare I say, the idea going against Lisa Su from AMD and all the other people are talking about how it is not about less jobs.
7:14I think it is about less jobs. I think they're not talking about less jobs because they don't want to create a situation where the people working on AI and the technology people that are coming up with all this will get nervous about that they're going to be replaced. the proof is in the pudding right here. Now, unless we see something very different from these two-month numbers or the quarterly, but the two months that we've seen changing, there is something to look at there. And that is going to be an interesting impact that will be seen on inflation if we continue to see this productivity really cut your labor costs and us able to get the same amount of production out at a less cost.
8:04So something to think about. I want to talk about Venezuela for a second. And I want to start by something that I wrote as an inside piece, an internal piece that we'll use it for our own research. And sometimes we'll take snippets of it, talk about it, get it out to clients, et cetera. But I want to share with you some of the things that we talked about. And it deals with Venezuela. Henry Kissinger said, control oil and you control nations. Okay, well, something to be thinking about in this circumstance as we are now knee-deep in crude, or potentially in a very heavy, sour crude that needs a lot of refinement that we maybe are getting, I don't know what they said, I'm talking about 50 million barrels freebie or something.
9:00Whereas if you look behind the curtain and really what it talks about was utilizing the money for Venezuela and then Venezuela will buy back things from us and only buy American products with the profits, but we're going to hold the money until such time as Venezuela is stabilized. But I've been chewing on this a bit and the notion that the United States can simply intervene in Venezuela and quickly turn the situation around, you're creating this stable, prosperous and pro-American outcome, I think is tier one, level one, basic and overly simplistic, thinking that is historically unsupported. Because in the past, when we had this US-led regime change, because that's what this is, right?
9:48Isn't this simply a regime change? We're not taking that over. Even though President Trump said we're going to be running the joint, right? We're going to be running the place. But this is simply a regime change Which by the way in effect hasn't even happened Because the second up, the vice president is taking over right now Not even the rightfully elected politicians That were put in place Are actually going to be running the country But when we did things in the past like Libya and Iraq What happened? It frequently resulted in prolonged instability, these power vacuums that were created, violence on a variety of different levels, and in the end, a humanitarian crisis rather than any kind of rapid improvement.
10:52So what is going on kind of raises your eyebrow into thinking about this could be setting up a very dangerous global precedent. Because if you think that the U.S. can simply overthrow a government that they feel and we feel that's unacceptable, which I'm not arguing whether or not Maduro was a bad guy. We know what the story was there. But where does that stop? Where do you draw the line? because these actions erode international norms and they encourage reciprocal interventions by other powers, potentially destabilizing other places. And the knock-on effects, like for example, what now they're talking about is the concern about the production of oil in Chile and what's going to happen to other countries.
11:41And you think about a place like Taiwan and what's going on in Ukraine. Is it okay that they are doing this in Ukraine? I mean, we did it here. Now it's kind of normalized. the issues about Taiwan, a bit different. There's a lot of parallels that have been drawn by this and saying that, you know, oh, if the United States can do this, then China's going to, they're going to just, you know, take over Taiwan. These longstanding claims over the self-governing island and the rhetoric that's going to happen by these U.S. actions, interesting, but I don't think so. Because the U.S. action in Venezuela, it does give China the chance to say, hey, look at what they did.
12:20Look, the Americans break its own rules when they want to. You know, we're going to do what we want. I don't think so. I don't think this is going to speed up. You know, when you do the research, you look at what all the experts are talking about. It clearly shows that it's a much different circumstance. Taiwan is much harder to invade because there's a strong defensive line. And China might have these really great talking points, this propaganda due to what we did in Venezuela, but it probably won't change the real risk or even the timeline on any big moves in Taiwan. The big thing, though, that I think is really the most head-scratching is the proposals that the U.S.
13:09energy companies could swiftly enter Venezuela developed these incredible oil resources with the U.S. government somehow reimbursing costs through seized assets and various aid packages. I'm not sure about that. Venezuela, as much as it was to be a part of what we're doing, still aligned closely with China and Russia. These are relationships that were built over decades. There was all sorts of military cooperation, infrastructure loans, oil. So now listen, the bonds in Venezuela have gone up, I don't even know, some ridiculous amount. They was a defaulted bond, so really couldn't get your hands on that unless you already had them in default and that worked out for the players that held on to them.
13:53The stock market, I think it was in the last few days up 75 % or something like that. Good stuff. But there are big ties to Moscow and Beijing. and they still have a significant leverage over Venezuelan assets and even, I would dare say, probably decision-making. So I think that American firms that enter or they're thinking about entering are going to require significant guarantees before they do so. Now, you and I, it'd be very difficult, next to impossible, to actually invest in or directly in Venezuela at this point. It's just not something we could do. Can we find some tertiary types of investments like, for example, a Chevron or other players that will enter into?
14:49And for example, our defense plays, right? And the defense plays are a tertiary investment thesis and sector that can be utilized for that because we know that the military is going to have to be expanded on this, right? The one thing, and I'll really finish up on this item here, but the one thing that I think about when I think about this whole decapitation of the leading bad guy from the government body is the notion that if we are going to now be available to go in, and expand the infrastructure and build out and do all this, what does that remind me of, I was thinking? Where, particularly where we were so excited about a change in what was going to happen and the relationship in particular with the United States and another country and the bell ringing of the opportunity financially for us all to get involved, where is this most similar to?
15:54And I was thinking Cuba. There was a time many years ago that Cuba was opened up for investment, right? Under the Obama presidency, I went to Cuba during that period. And this was like 2014, 2015. And during that time, the policy was focused on encouraging economic liberalization and private sector growth through the increased travel, which happened. This tourism boom and all these remittances that will come back to the country. And while it did generate this temporary tourism boom and some expansion, we got to say that of small businesses, the overall reserves were limited. The embargo remained largely in place.
16:46Political reforms, they talked about it, but then it kind of went backwards. And then what happened? U.S. reversals just curtailed all that. So I think this is a similar opening, quote unquote, opening in Venezuela could produce modest incremental opportunities, but widespread benefits, I don't know. You know, the persistent corruptions, just the infrastructure, what it would take to build the infrastructure and the reluctance of companies to do so without any kind of guarantees by the U.S. government, I think is going to be hard-pressed to do. Now, with that all said, and this is a, oh my gosh, did you know this moment?
17:30Venezuela has more oil reserves. In fact, it's the largest. When I say that, the largest. I'll say it again, the largest. 300 billion barrels of oil is said to be held there, which accounts for about upwards of 20 % of the global total. This is unbelievable, right? It's in an area called the Orinico Belt area, which is heavy crude, which is very difficult. It's like from the Canadian tar sands. This is a hard, called sour sometimes, type of oil that takes a lot more refinement. But this exceeds those in Saudi Arabia. This is transformative if we can get it right. This is pretty exciting if the production capacity can be modernized.
18:29And if, in fact, sanctions can be eased and all this goes on, all of this is going to only happen if we can overcome the substantial, very substantial technical and financial and environmental and political hurdles. So from an investment standpoint, yes, it does open up big opportunities. but there's plenty of risks. The main winners, probably going to be the energy companies, especially oil infrastructure companies. That's why you probably saw the Caterpillar just, I mean, just go up like crazy. You look at the Dow Jones Industrial Average and what's going on there this year, leading the pack, and a lot of that's because of, for example, companies like, well, Goldman Sachs was big, but Caterpillar as well.
19:18Then you have material stocks, right? So it may take decades, maybe a little less, to see these real production increases. Because again, these damaged facilities that are going on for decades that haven't been revived. But something to think about as an investment thesis as we go along and to watch this carefully. We're very early on, very in the infancy of this change. And with that, I think that there is a lot of opportunity, but a lot of risk. But that's when the opportunity is the greatest. And I think some of those areas, particularly with energy and some of the infrastructure companies, have opportunity to look at.
20:06Do your research. And from there, maybe you'll find some additional opportunities. I want to talk about interactive brokers and ask you a question, because what if the next big opportunity was hiding in plain sight? IBK, our desktop, helps you find it. With powerful discovery tools like Multisort, you can scan thousands of instruments using custom filters by sector, performance, volatility, and more. Dig deeper with advanced charting and real-time data. You can also have quick trade buttons and access over 160 markets. Whether you're spotting trends, adjusting your strategy, or responding to market shifts, IBKR Desktop gives you everything you need to move from idea to execution, all in one modern platform.
20:53Best informed investors choose interactive brokers. Remember SIPC. Download IBKR Desktop at ibkr.com slash desktop. And our guest today is Todd Treseder. He's graduated from the University of California, Davis, with a BA in economics and a passion for creating successful businesses. He's a serial entrepreneur. Since childhood, Todd went on to build his own wealth as a hedge fund investment manager before retiring at age 35 to teach others. And today he provides advanced investment and retirement planning education at financialmentor.com, showing you what works, what doesn't, and why based on a depth of proven experience, this can occur.
21:37He's the author of five financial planning books, including How Much Money Do I Need to Retire? Don't Hire a Financial Coach and Variable Annuity Pros and Cons. So let's get right on with it. So, Todd, how are you? How you been? I'm good. Good. Yeah, just working away, building out courses. So just doing a lot of writing lately. Oh, yeah? Yeah. It's time. You like that. That's your thing. I mean, the education component and the getting information from you to them. Yeah. I like the impact it has on people. I like making that my life work, you know, is to make an impact on people and raise their awareness around financial issues.
22:18Well, last time you were on was February of 2016. Jeez. which was just about, we'll call it, we're just going to call it 10 years ago. Okay. So a lot of things have happened since then, obviously. A lot of learning that you've had since then, we all have, right? And a lot more information you could share. Let's talk about, I want to kind of, you know, a lot of times, like the beginning of the show, I talked about defense stocks. I talked about Venezuela. And I talked about what's going on with productivity. But I think I like to mix it up a lot of times with, or mix in, not mix it up. but mix in the discussion of bigger picture and things that people need to do.
22:58Because it's really interesting, you know, to know about everything that's happening up to the moment. But the reality is that's not how people make money, is it? That's my viewpoint. You know, I don't invest based on news. I don't invest based on those things. I've always been a quantitative investor and I've always looked at the numbers, which to me drives returns, right? I mean, it's the compound growth of your wealth. And so you've got to understand the math of how wealth works. And what is the, I don't want to say the secret, but what's the reality there? How does math work in terms of this?
23:32And differential? Yeah. The piece that most people don't intuitively get is that expectancy, mathematical expectancy is what determines the compound growth of your portfolio. And most people intuitively, they think in terms of probability, like what's the likelihood of something occurring? So let's play off of what you're talking about earlier. They attack Venezuela, you know, or we take Maduro. So what is the impact of that on what's the probability that oil stocks are going to go up? Like, are oil stocks going to do better? Are they going to do worse? Is the oil market going to go up or down?
24:07Like people think in terms of likelihoods of things occurring. And that's the human intuitive thing. But what really drives investment returns and it's counterintuitive is it's expectancy mathematics, right? That's what determines the compound growth. And that is different from probability in that it's probability times payoff. And so you have to take into account payoff. And why that's important is because extreme payoffs are critically important to the entire compound growth equation. It's the opposite of what conventional financial advice teaches, right? So conventional and financial advice will teach things like you should ignore interim volatility because eventually the market goes to new highs.
24:54If left of its own device, there is no volatility. If you look and stretch it long enough, right? That's the whole concept. Yeah, that's the premise. But it's actually mathematically wrong, okay? And it's provably wrong. And it has very real-world effects that show up in conventional advice, but they just don't label it as such. And so - So can I stop you? Because I want to get some definition here and some clarity. Sure. So on why it's wrong, I'll give you, I'm going to ask, I'm going to give you something I did this week and tell me if that's what you're talking about. So I did a Monte Carlo simulation on a client's potential outcome.
25:27And, you know, Monte Carlo is different than a straight line where we say, okay, well, you'll average what the market's average of, I'm just picking a number, 8 % per year. and then, you know, without that interim volatility and that drawdowns and all that, you know, because it's just compounding every year at 8%. Whereas a Monte Carlo simulation gave me hundreds of different scenarios and sometimes they work and sometimes they don't for the client. Are you saying because of some of the real life things that happen, that should be taken into consideration in a bigger way than just the assumption that risk goes to zero over time?
26:05You're on track. Let me expand on it a little bit. So Monte Carlo simulation, there's a variety of different versions of it. You can either synthesize returns or it'll randomize existing or actual market returns. And so what you'll end up with is you'll end up with a confidence interval. So let's say you're working with your client and you end up with a 95 % confidence interval that they don't outlive their money, right? Using a 30 year time horizon, that would be like a standard Monte Carlo analysis. What it fails to show is what is the 5 % and what is the real risk. So for example, using volatility as a consideration, the 5 % time that it fails is not random.
26:48It's not randomly distributed despite what Monte Carlo premise is. it occurs from periods of high market valuation, which then leads to extreme market volatility, rare events. It's less than 5 % of total market history. And so let's say you have a client right now today. So as we record this, it's January of 2026. It's the most overvalued markets in all recorded history. And so the math of that says that the expected return over the next 12 years is actually negative 5 % compounded. And that's based on correlations of historical periods of similar valuations or valuations that were less extreme.
27:29And so what happens is the Monte Carlo failures are not randomly distributed. They occur, that 5 % failure occurs 100 % of the time from valuations that aren't as extreme as this. And so somebody that receives a Monte Carlo simulation that says, hey, I'm 95 % confident I'm going to be okay, and they retire today, they're actually retiring today in the 5 % window that has a high likelihood of failing. But that's not what it says. It tells them, hey, you're 95 % confident you're not going to fail. But that's distributed over the entire spectrum of investment returns and investment valuations. It's not pointing out the period they're in now where they're choosing their retirement.
28:15And this goes into a lot of mathematical myths that go on in financial management because there's a huge difference between your client who's an N of one, right? There is no sample size to a client. There is no random distribution to a client. They are a market timer by birthright, right? Right. They are they are born into a period. They got returns from a certain period and they will retire into a certain period. And it's all determined by their birth year. And so they do not have any sort of statistical reality to their results. So back to you. No, it's interesting because, you know, I think I think I get to the bottom, get to the bottom of some of this where you talk about the financial myths.
29:04Right. One of them is back in the day when everybody was using modern portfolio theory to try to build portfolios based on the efficient frontier. There you go. You know, I'm talking about here. Right. The whole thing was. Well, I mean, it's laugh. It's laughably funny. It was laugh. Finish your question. Yeah, at the time, it was like, okay, let's get into this. Let's see what this is all about, right? And I was running all sorts of models and trying to come up with, you know, this highly efficient portfolio based on the models that were presented because – and the one thing that always bothered me was this whole idea of portfolios – well, what would they say?
29:43The portfolio returns were 92 % based on blah, blah, blah, when it was not in fact that. Remember the whole 92 % basis thesis on portfolio returns were based on the allocation? Remember that whole thing? Well, yeah, let's back up and bring people up to speed here because this is a great example what you're bringing up, right? So modern portfolio theory, 1952, Harry Markowitz. He was a Nobel laureate for it. It's this absolutely beautifully elegant theory, right? What you do is you design your optimal asset allocation. There's this theoretically optimal asset allocation called the capital efficiency line or something like that.
Read the full transcript
30:24And so what you're trying to do, you have this curve that occurs where you've got this tradeoff. And let's just use stocks versus bonds to keep it simple. It's stocks, bonds, cash, whatever else you want to throw in there. And so you start substituting these. and you move along this efficient frontier curve that eventually intersects the capital efficiency line at some point. Well, that's where we get this theoretical 60-40 portfolio, right? That's theoretically somewhere close to where it connects, where the efficient frontier connects. So what happens is as you get rid of more volatile things, i.e.
31:00stocks, and substitute in less volatile things, this is called risk dilution, by the way. You're diluting the risk of your portfolio, but of course you're diluting the return at the same time. So what happens is you move down the efficient frontier, but you move down more in risk. So it's becoming more efficient as you substitute some bonds with some stocks. The reason that occurs is non-correlation, right? Non-correlation in returns allows that to occur. So it's this beautifully elegant theory of how to design this optimal asset allocation, right? And so far, it sounds good. The problem is it's completely wrong, like not even close, like not even in the ballpark.
31:45I'm not even nitpicking. It's wrong, dead wrong. And the reason it's so completely wrong and completely useless is easily provable. What you can do is what happens, it's built on a flawed premise, right? The flawed premise is that you design this optimal portfolio based on the historical return, volatility, and correlations of the assets that you're working with when you design this model portfolio, right? Well, the assumption is everything. The point is there. Let me just mention it so listeners can understand this. The assumption is that everything in the past will be in the future. That's the problem of the assumption.
32:22Yeah, it's exactly what I was getting at, is the premise is that the past returns, volatility, and correlation will have some bearing on the future. Reality is it's not even close. Like, it doesn't have any bearing. You can have different assumptions that you optimize over. You could optimize a portfolio and come up with 100 % stocks for a 10-year, 15-year, 20-year period, and then you can come up with 100 % bonds for another period. Like not even in the same ballpark. It has absolutely no relationship to what an optimal portfolio is for the only time period that matters, which is your future, the unknowable future.
33:02And that's the key that people miss is the future is unknowable. And so you can't optimize based on past returns, volatility, and correlation. And so it's this gorgeous theory that is the foundation of the 64-day portfolio, much of the asset allocation used in conventional advice, and it's completely irrelevant. It doesn't work at all. I actually attended, back then, I was a bit of a geek when it came to this stuff because I was really interested in it, and I spent time with Brinson B. Bauer and Hood, well, B. Bauer actually, at meetings. William Sharp had dinner with him out in California, and I was the guy like, I don't understand.
33:38Can you explain something to me? Like why are we using standard deviation, not downside deviation, and utilizing that as part of the complex of this? And why are we doing this and not that? You know, there was a lot of little things in there that I really was hard-pressed to understand how this came into be and how – but, listen, fun families like DFA and all these guys made their mark with this. And there is some components of it I do like. if you can really find long-term sectors that are thinly correlated, not that that's going to always be the case, but if there is something, there's something to that to building a portfolio potentially for some downside risk mitigation and for some buffering.
34:22But I agree that the idea of spending time with a dial, trying to figure out the exact efficiency of a portfolio based on those metrics, as you mentioned, is great. And computers could do it looking backwards. But going forward, the whole thing just blows up right in your face. Right. So let's bring it to current times, right? You hit on a key point. The only way it has any validity is if you can find financial non-correlation of returns, volatility, and risk that has some financial basis to it. Like there's some logic that will persist going into the future. And so the reason stocks and bonds have historically been, and particularly in recent history, right?
35:05I'm talking like in the last 40, 50 years, right? It's been such a great diversifier and it's worked beautifully all the way up until 2022 when it failed is because bonds will tend to rise during a deflationary decline because the federal government will then lower interest rates, which raises the value of bonds. bonds. And so you have a financial logical basis of why bonds provided good non-correlation and was a good investment product for diversification of stocks. And that worked until it doesn't. And that's why you hear a lot now about people talking about a 60-20-20 portfolio, the other 20 being gold.
35:49So why is gold suddenly a good diversifier? The answer is inflation, right? So in an inflationary decline, there's only, let me put it a different way. Let me phrase it a different way. During a declining market, all assets correlate towards one. All correlations rise, usually with the exception of one asset. So in a deflationary decline, that one asset is bonds. So credit risk instruments, okay, in general, bonds specifically. And during an inflationary decline, it's precious metals, oil, commodities, et cetera, et cetera. And so real things in broad terms. And so that's why all of a sudden you're hearing a lot of talk is because we're an inflationary environment, gold's running.
36:40And there's a lot of reasons why gold's running. That's not it. But anyway, and so all of a sudden they're talking about a 60-20-20 to replace the 60-40. And going back to our earlier conversation, that was nowhere from any history that you would be running that leads up to current, that was nowhere on the capital efficiency line. Right, right. Right? Yep. There's just no relationship. You have to understand how this stuff works at a deeper level. These are just financial myths that are widely touted that don't work. Another one that's interesting on the same lines and within the same, I would say the same genre to a degree, but yet at the same timeframe when it was created, American funds for a long time had a mountain chart that you would look at.
37:25And it was this brochure that would show you over time. And it says, you know, if you missed the X number of days out of the trading year, you know, you would, I think it was the 10 best days. And I always said to myself, Todd, I said, how come they don't show us if I just escape to 10 worst days? Right. I'm just saying, I was always wondering that. I really, it was a big head scratcher to me. I'm like, well, this is great. And I'll tell you, let's just get to the punchline here for one second. These are all measures that were created by marketing teams that were utilized from some research that was done along the way somewhere.
38:04where they plucked out what they wanted to pluck out as the best way to convince people to give them their money. I mean, that's, that's the way I see it. Yeah. I'm actually shocked at how many really intelligent people subscribe to the 10 best days, 10 worst days myth. Yeah. Okay. It's mind blowing misuse of statistics and math and historical data. And yet there's so many really intelligent, well thought out people that have written pieces supporting this. And so it's just another widespread myth. And so let's go through the conventional wisdom. We agree that most people would only talk about the 10 best days.
38:42They don't talk about the 10 worst. Correct. Correct. I call it the 10 best days, 10 worst days, right? Yeah. You'll see it promoted as the 10 best days. You can even do the 20 best days. And so let's first of all, get the myth, right? The myth is that's widely touted. And again, high level experts. I mean, famous authors, you know, these are people that should know better and they're promoting this. And it says, if you miss the 10 best days over X years, you know, it's always different, right? Or the 20 best days over Y years. It doesn't matter. It's always the same thing. then your long-term returns will be a tiny fraction.
39:20Now, don't quote me on it, but it's a dramatic difference. It's like if you compounded at 8%, you might compound it like 2 % or 3 % by missing the 10 best days. It's a huge difference in your compound returns. And that part is legit. That part of the analysis is absolutely mathematically correct and legit. The problem is the conclusion. The conclusion they come to universally is, well, since you can't ever know where the 10 best days are going to be, you have to buy and hold because you can't ever miss any of them. So you have to buy and hold, right? So now let's look at what the truth is. What's really going on here.
39:5718 of the 20 best days all occur below the 200 day moving average. Okay. So it's, it's a who's who of the worst time to be invested because all market volatility occurs below the 200 day moving average. And I'm not using a 200 day moving average is any magical thing. You could say the 50-day moving average. You could say below trend line. You could say, I mean, there's a lot of ways to define it. But one way to put it out is a downtrending market. Yeah. Well, the bottom line is that all the best days you've ever seen usually in a market happens in a bear market. Yeah, exactly the point. That's exactly where I was going.
40:30Which by the way, when I look at it, I always confirm the fact that we're in a bear market if I see something crazy like that. Yeah. And you always see it. Every bear market, volatility clusters. So the actual truth is volatility clusters, both up and down. So the reverse of, so here's the reverse logic. They're basically really telling you when they advocated that you have to be invested during the worst possible losing periods in history in order to make money. Right. That's what they're actually advocating. Just to saying that out loud sounds ridiculous, by the way, because it is, it absolutely is.
41:05Right. And then the flip side math, which you alluded to was if you pick up the 10 best days, I'm sorry, the 10 worst days and remove those, then your returns are equally grown. So again, I'm not, don't hold me to the math, but it's something like if it was 8 % compound, it jumps to 12 or 14 % compounded if you threw out the 10 worst days. So what's the truth? The truth is volatility clusters, right? Volatility clusters, big days, both up and down occur during volatile periods, which is downtrending markets. And so what that does is that points out that the very thing everybody tells you to ignore, which is volatile market environments, are actually the most important.
41:47They literally determine the validity of your investment strategy, the volatile periods, the very thing everybody says you should ignore because eventually the market runs to new highs. So how do you conquer that or combat that as an investor? what's the bottom line i teach tactical asset allocation okay so tactical asset allocation works you know that would tie into another myth right people will tell you um you can't market time but then nobody defines what market timing is right people have this sense that they know what market timing is but they don't and so let's define it if you define market timing as predicting the future.
42:31So any investment strategy predicated on a prediction of the future, the market will go up. Oil stocks are going to do well. You know, the world's coming to hell in a hand basket, whatever the prediction is of the future. If you're investing based on prediction of the future, it doesn't work. Right. So that's how you're defining market timing. Any prediction of the future, it's correct. It doesn't work. However, if market timing is defined as a statistically valid risk management tool that never knows anything about the future, it's just working with serial autocorrelation and statistical validity, then it works.
43:07It works reliably. It works consistently. It works with mathematical discipline. And so you can create a tactical asset allocation model using statistical methods that has a buy and sell characteristic that can look like market timing, right? Because it'll be buying and selling. But the fact is it never knows anything about the future. If you look at the buy and sell signals in a valid TAA model, a valid tactical asset allocation model, it knows absolutely nothing about the future. There's no predictive quality to it whatsoever. And yet because it manages volatility, that affects the compound growth, that affects the safe withdrawal rate, that has all kinds of positive effects, which are all valid.
43:52Yeah. And I think what most people think of when they think of market timing is the gurus of the 80s who, you know, the Elaine Garazellas or this one or that one, or even some of the big hedge fund guys that, you know, when they say, hey, we're all in on Chinese tech stocks, you know, or, you know, hey, there's going to be a crash in two weeks and it happens. And it's like, wow, my God, this person's amazing. And then, by the way, where are they now? Yeah. Well, I mean, I was laughing when you said that because I haven't heard Elaine Garazellas' voice in years, or her name in years. shunned shunned she was a she was a huge name in her day so it was and she could move markets kathy wood kathy wood same thing yeah kathy wood is in the same is the same genre i think a little different kathy wood make predictions about the future that were bold that were absurd you know she did uh uh elaine did a couple different uh you know market crashes are going to happen and that's it god i'm trying to remember the guy's name before that i mean there was a guy that was huge before that, that literally could move markets based on money supply figures and all kinds of things.
44:59It wasn't Dan Dorfman, was it? No, it was somebody else. I remember Dan Dorfman too, though. He was arrested. I think. Yeah. Yeah. So all these guys are trying to predict the future, right? Cause it's great media. Oh, it's the best. What do you mean? That's the, if you could do that, if you can nail that once, you could ride that for a decade. Oh yeah. It's great media. It's great for eyeballs. It's great for advertising, all the things that run media. and it has absolutely no validity for investing, no useful practical value whatsoever. It's a complete waste of bandwidth. Yep. I want to go back to something you said and pick up on it because it was just said in passing.
45:34And you talked about how tactical allocation and some of the components of it. And we talked about briefly. We're not going to want to get into the depths of this, but you mentioned something that I think is really interesting about the safe withdrawal rate. The safe withdrawal rate from a portfolio. As a matter of fact, it's interesting. Just today, a client asked me, how much money would I need to generate$350 ,000 per year throughout my lifetime? I said, listen, there's a lot of variables that go into that. What's the inflation rate going to be? Are you leaving money to the next generation?
46:05You're going to say, screw that. I'm going to go down with the last dollar in my coffin. But that is the basic premise of a safe withdrawal rate. And the industry has had a number for years. It's been this 4 % to 5%. or I'll even go three to 5 % as a number. Yeah, I was going to say, you have to actually go under four to be, but go ahead. But that's the kind of an industry wide number. But again, that is a straight line number that we don't really know what's going to happen in the future. But why is, you know, tell me about that and how do we solve this problem of figuring this all out? The way you solve the problem.
46:46So there's a lot of questions in what you just asked. Okay. So I'm going to go with the last one you just asked, which was how do you solve it? You have to solve the volatility of your returns. So the difference between, so here's a fun question that very few investors ever really seriously consider, which is why is your safe withdrawal rate? Let's call it 3%, 4%, 5%, whatever the number, right? It varies with, here's the factors it varies with. And this leads to the answer. um the factors it varies with is inflation rate and market valuations right right and so if market valuations are low and inflation's low it's going to be higher and if market valuations are high and inflation's high it's going to be below four percent it's going to be like three percent the common thing was the four percent rule came from william bangen back when he did some research and people never ask why is safe withdrawal let's use four percent just because it's called the four percent rule.
47:44Why is that a tiny fraction of your compound return? So on the portfolio that supposedly supports a four percent safe withdrawal, maybe it compounds at eight percent historically. Right. Why is that? And that has to do with the volatility tax. Okay. The volatility tax, the volatility of returns, that very thing that conventional wisdom tells you to ignore is back on the table again as a key factor. The more volatile your returns, the more volatile return stream, which is why inflation and market valuations affect it, the more volatile return stream, the wider the gap between your compound annual growth and your safe withdrawal rate.
48:26So if you want to narrow the gap between your safe withdrawal rate and your compound growth, you have to narrow the volatility of returns. That's why, by the way, your safe withdrawal rate is actually higher than your return on T-bills because there's no volatility in the return stream. So you're literally spending the interest plus capital as you draw down over a 30-year amortization schedule. So it's the one example where your safe withdrawal rate actually exceeds the return stream. For every other asset, your safe withdrawal rate is less than the return stream. So you run with that and give me a new question.
49:04I'm just trying to think through this and that there's also the - By the way, that's the magic to tactical asset allocation. Tactical asset allocation is lowering the volatility of the return stream. It's not that it does that much better on the offense side, putting points on the board. What it does is it controls risk, right? So it's reducing the volatility of the return stream so that your compound annual growth is getting closer to your average growth and the dispersion of returns is smaller. So what that does is that increases your safe withdrawal rate. I've got tactical asset allocation models with safe withdrawal rates that theoretically, theoretically on a perpetual withdrawal rate, which is the most conservative measure, right?
49:48Perpetual. Of course, forever. Yeah, perpetual withdrawal rate runs up to 8%. Really? Yeah. That's impressive. I would never advocate that. Right. I would never advocate that. But just think about it. If you went from three and change, which is a realistic safe withdrawal rate for right now, given inflation, given market valuations, three and change is what most people would come up with for a safe withdrawal rate right now. And you moved it out to six. That means you've literally doubled the amount of lifestyle for any given portfolio, or you've cut in half the amount of savings you have to accumulate, or you've shortened the amount of life you have to give to accumulating those savings and you can retire sooner.
50:31It's a life-changing difference. Live a lot longer. Yeah, most people have no understanding of how this stuff works. Well, I mean, it's not easy. And that's why there's professionals and there's people out there. You know, the fact is that a lot of times I talk to people and they're like, I don't know what you just said. I said, what do you mean? That was pretty easy. I mean, I was trying to really keep it on the low here, you know. I remember my first book that I wrote, people were like, hey, this is great. I don't know what you said, but it's so interesting. I said, what do you mean? So then I wrote a second book that was kind of a lower version of that, you know, an easier read.
51:02And people are still like, I have no idea what you're talking about. I'm like, wait, I tried to explain some very basic points about compounding of interest. Well, the thing is not everybody is cut out for managing their own money or dealing with this. There's emotional issues. There's mathematical issues. There's just, listen, let's face it. There's right brain, left brain issues going on. and but these are the kind of things that people should be aware of that there are other options and that I think that if I was to summarize our discussion right now is that there's a lot out there in the media and marketing that makes things look a certain way that maybe not, it may not be the actual reality that there's a better way in some circumstances and that you don't have to follow along with just this simple like, give it to a broker and it's just going to buy and hold forever.
51:55You know, this, this concept, right. Or, or, um, uh, you know, simply go, uh, because, because they say it's cheap. We should go to ETFs that are passive only as an example. I don't know if, you know, I'm just making this up. Um, that, that, that's the only way to go. There's many ways to do the same thing, right. And to get, get ahead. I'm, I'm agreeing with you. I'm going to say it in a slightly different way to put a different spin on it, but it's basically, it's basically the same thing, but I'm going to put it in a different way. You have to be very careful of conventional wisdom for the very reason you said, which is, hey, Todd, that sounded really interesting.
52:28I have no idea what you just said, but that was really cool, right? Conventional wisdom is simple enough that people can understand it. It has intuitive appeal, and it's close enough to reality that passes the smell test. And so that's what becomes conventional wisdom. That's what's widespread throughout the internet. okay what you and i are talking about is more advanced and that does not become conventional wisdom so i have a thing i call level one versus level two so like buy and hold four percent rule you know 10 best days these are all level one right and they're they're fundamental misunderstandings of reality but they they intuitively appeal to people they make sense And they use the numbers close enough to reel that it takes an expert to take it apart and show why it matters.
53:22We're not taking this apart to entertain ourselves. This changes people's financial outcome in life. Right? So level two is a more advanced understanding. It's more nuanced. But it never has mass appeal. Okay? When was the last time one of your listeners heard me? Yeah. You know? We just cycled through, I know. Well, heard you through our listeners. They may have heard you. They may have stuck with you. Yeah, it's just, you know, it doesn't have mass appeal. Okay. And, but it's, it's accurate and it changes lives for the better. And so I choose to stand by level two wisdom. That's what I teach.
53:57And that's what my focus is because that's what works reliably. And just to be clear, level two is not counter. That's not the point. It's advanced. Yeah. And it's not even all that advanced. Like my students all tell me once you get this stuff, it's so obvious. they can't understand why it hasn't always been taught this way. Like, why don't they just teach finance this way is what my students always tell me. Because it's not that complex. You just have to put the puzzle pieces together. It's all built from mathematical expectancy and the future value equation. Because guess what? Those are the two equations that determine your financial outcome in life.
54:33Right. You have to, you can't violate the math. Everything we've talked about here ties back to those two equations in one form or another. It ain't complex. it's just not it's actually remarkably simple once you get it and actually in some ways it's easier because once you get how it works there are no contradictions like if you run around and you listen on the internet to all the various experts they all contradict each other you know one guy tells you you get rich in stocks another guy tells you get rich in real estate another guy tells you it's all about gold right and it varies from time to time they're all wrong okay because it's not about any specific asset.
55:12That's just a risk profile of a specific product. But it's such an easy sell. It's so easy when you start, you know, revving it up and you make it look good. I mean, I can't tell you how many times clients in the past, they don't do it anymore. I put my foot down. Like would send me a TikTok thing. I'm like, what, what, who, first of all, what are the credentials of this person talking? I mean, literally, I'm not talking about even questionable credentials. I'm like, this guy, I think this is just reading something that was put in front of them. And, you know, about, about Bitcoin, about, about this asset or that asset, or, you know, you want to stay away from this, the world is ending.
55:47How many, how many times have we heard the world is ending? So I think, you know, buyer beware, but also as Cy Sims would say, an educated customer is our best, right? An educated consumer is our best customer. An educated consumer, educated investor, I'm not talking about crazy time put into it. I'm not talking about, you know, a full straight up MBA in finance. I'm not talking about that. I'm talking about as you are learning the, and understanding the basics so that they could do really good things for themselves and their family. Yeah. What, what my students tell me is that when you get this stuff, you have a smell test and you can smell bullshit a mile away.
56:26Oh yeah. Yeah. Right. So you, you have a smell test. You can see it. I can see it. And my students can see it because they've learned the fundamental truths. They've learned how this stuff actually works in reality. So when, when these talking heads go up and they start pontificating nonsense, you just look at and go, Oh, look at that. He's predicting the future. I can dismiss that. Oh, look at that. He doesn't even have the math, right? Forget that. Oh God, he's violating volatility mathematics and volatility drag and volatility tax. Like he doesn't have any idea what he's talking about. And you can just, you can just sort the wheat from the chaff, like so fast and easy and i gotta tell you once you know how it works i have helped clients in real time steer clear of three different ponzi schemes big ones oh yeah because back when back back when i coached i had the same thing i would be working through a client's portfolio when i was a coach i don't do anymore right all i have is courses and books now but when i was a coach and i did coaching i would be i would be looking at clients portfolio and i'd say um this smells really bad.
57:29And it's part of the reason I wrote the book about financial fraud, how to detect financial fraud was because I was literally picking off financial frauds in people's portfolios and saving them because they would go back and like, it wouldn't be immediately, but it'd be a year later, two years later, whatever it was. And the fraud would get revealed and they'd be like, oh my God, you saved my rear. Yeah. I can't tell you how many millions of dollars I saved a few clients because they came to me and had me sit down on meetings. I'm like, excuse me, I have a question. You know what I mean? I did that again.
58:02I don't understand how you say you're leveraging this up three times on these treasuries and you're going to blend. What happens if the, if the, if the yields go up on, well, no, that's not going to happen. I'm like, but if it does, well, that's okay. And the bank you're using to back these, and these are considered CDs that you're going to hold who's in are Antigua. And what if I want to get my money? Where is the jurisdiction for me in the finance? It's Antigua. It's a little bitty island in the middle of nowhere. Seriously. So I got to go there and fight for my money. I don't think so. Two years later, two years later.
58:38Who's the big fraud that went down a few years ago? I'm forgetting. It was Madoff. Yeah. Madoff. I say people from that one too. Yeah. So Madoff, right. I'm looking at that. And I told my clients, I said, well, either he knows something I don't, which is unlikely because I spent, I'm not, I'm not blowing my ego here. Right. But I spent 12 years testing. I call it the a hundred thousand dollar garbage pile, testing most models out there to figure out what was valid, what wasn't, what actually produced results, what didn't. And so you get pretty clear on what works, what doesn't. Right. And so I go either he's figured out something I never did.
59:16He knows something I don't, or he's a fraud. And I said, the chances he knows something that would produce those returns is really close to zero, given everything he's claiming he's doing. And so it's got to be a fraud. And you can know it just by looking at the track record. Same thing happened, I don't know if you remember the educator Van Tharp. He used to do psychology of trading. And he had a star student called Maricopa Capital Management. and maricopa actually had the gall to show their track record and i went through that track record knowing the market conditions at the time and what they claimed they were doing and i said point blank i said it's a fraud you can't do that you can't produce those returns from those market conditions doing what he's claiming he's doing it's wrong a couple years later fraud shows up done yeah yeah it's like you can understand what the limitations are and what's valid and what isn't just by understanding how this stuff works.
1:00:12And it's not even so far as going the entire way towards fraud. It's also understanding what is possible and what isn't, which is a much different discussion. Yeah, like let's take Renaissance Fund. Renaissance Technologies and Medallion Fund, right? You could look at that on its surface and think, oh, gee, that's a fraud. But if you look at what they're doing, you realize it's not. They had floors of computers, guys with handheld devices on the trading floors, scalping eights and quarters left and right. They knew exactly what they were doing. It was completely valid. Now, it wasn't scalable, and that was proven by every one of Renaissance other funds, which could never duplicate the track record of Medallion.
1:00:57Right? It was limited by liquidity, and so those early investors that got in Medallion had a home run, whereas other Renaissance Technologies funds never performed to the same degree. Also, when his book came out, things kind of shut down. Yeah, I don't. What's his name? Jim. Jim Simons. Jim Simons, yeah. When his book came out and he was, you know, he wanted to come on the show. I'm like, no, I don't think so. But I'm giving an example of an extraordinary track record that was actually valid. Yeah, no, I got you. Right. And there's a financial reason why it was valid. What they were doing was legitimate.
1:01:32And they had a technology advantage they were exploiting. And they knew the math of how to play the game. and so that was legitimate, whereas you'd look at Maricopa or Bernie Madoff, and you'd go, nope, that's a fraud. Good stuff. Well, hopefully we're going to get together before 10 years elapses. I'd love to. I'd love to, too. I appreciate you having me on. And where can people get information on what you do and what you're talking about? Yeah, so everything is at financialmentor.com, so two words mashed together, financialmentor.com, and I have one course. It's a flag. I call it my master course called expectancy wealth planning.
1:02:11And anybody that listens to this conversation knows why it's named expectancy wealth planning. And it's unique in that it's the only financial strategy course, wealth strategy courses built from the ground up on the math that's valid. And it's not a math course. Like I have tons of people in there that have hate math and they're doing just great in there. So don't, don't be freaking out by math. But it's a master course in understanding financial planning, wealth planning. And if you think you don't need it because you have a financial advisor's financial plan, think again. It's completely different.
1:02:45It's level two. Okay. What you're living in is level one, if you've got a financial advisor financial plan. This is level two. It's also a huge community around tactical asset allocation. And that's what most of my students employ or a mix of that with buy and hold. And I teach a principle called deep diversification while it's true. So anyway, it's all over at financialmentor.com and I have one course and I have a few books and that's all I sell. Top Trusted, I appreciate it. You have a great one. I appreciate you coming on. Good time of the year to do this. Right at the beginning, people getting set for the rest of the year, the rest of their lives and all that.
1:03:20And let's make it happen for them. Yeah, thanks so much for having me. I enjoyed the conversation. Thanks, have a good day. See ya. Right. And that's going to be wrapping it up for this episode of the Disciplined Investor Podcast. That was pretty good. I like that. Going back, especially to the years when we talked about the efficient frontier, which, by the way, we still believe in. I think there's still good use for that, but it has to be modified. We use that as a core of what we do still. But the way that was done years ago, the way that was utilized initially, modifications needed to be made.
1:03:51The concept is there with non-correlating assets, and that's what we do in our portfolios on a regular basis, by the way, for clients. If you're thinking about becoming a client, well, we're looking for you to reach out because we can't find you. Go over to thedisciplinedinvestor.com. There's lots to see there. Find out about the TDI Managed Growth Strategy, our long-short strategy, equity-oriented, some hedging in there. We use options. We use short trading as well, as well as going short. the markets as well as individual stocks. Again, that's all over on the disciplinedinvestor.com. Thanks for joining me this week and every week.
1:04:29I'll see you real soon.
1:04:35This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz and Company, Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements.
1:05:13Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement. Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates.
From the publisher
Capturing Maduro and Buying Greenland – all in a day’s work!
Markets off to a great start – plenty of January to go…
Venezuela oil – untapped opportunity – BUT let’s take a closer look.
And our Guest – Todd Tresidder – Founder of FinancialMentor.com
NEW! DOWNLOAD THIS EPISODE’S AI GENERATED SHOW NOTES (Guest Segment)
Todd Tresidder graduated from the University of California at Davis with a B.A. in economics and a passion for creating successful businesses. A serial entrepreneur since childhood, Todd went on to build his own wealth as a hedge fund investment manager before “retiring” at 35 to teach others. Today, he provides advanced investment and retirement planning education at FinancialMentor.Com showing you what works, what doesn’t, and why based on a depth of proven experience.
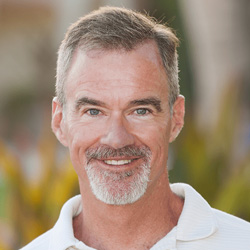
Todd is a financial coach and educator at FinancialMentor.com. He’s the author of five financial planning books including ‘How Much Money Do I Need To Retire?,’ ‘Don’t Hire A Financial Coach,’ and ‘Variable Annuity Pros and Cons.’ You can connect with Todd via his website, Financialmentor.com, Twitter @FinancialMentor, or on Google+.
Check this out and find out more at: http://www.interactivebrokers.com/
Stocks mentioned in this episode: (SHLD), (RTX), (SPY), (GLD), (XLE)