
In short
Episode topic: Market “V” rebound after a 10% drawdown, driven by short covering, while inflation and geopolitical supply shocks (especially Iran/Strait of Hormuz) may still feed into higher prices and slower growth. Discussion includes the Key Reversal Indicator overheating, upcoming earnings season timing vs stock-price peaks, and portfolio risk management via rebalancing/neutral positioning. Guest also addresses AI-driven capex, growth vs value, and emerging markets outlook.
Guest backgrounds
Tom Nelson is Senior Vice President and Head of Asset Allocation at Franklin Templeton Investment Solutions. He co-chairs the firm’s investment committee on asset-class strategy, serves on the Investment Strategy and Research Committee, and is lead portfolio manager for multiple Franklin funds/model portfolios.
Key claims
Supply shock may not yet be causing demand destruction; fertilizer and energy route disruptions could raise food costs later (2H 2026–2027). Consumer confidence is extremely weak, but retail sales and small-business indicators suggest spending/hiring are still holding. AI capex may pressure earnings vs cash flow, but AI infrastructure demand is resilient; long AI beneficiaries/short AI-risk names.
Notable examples
JB Hunt (fuel surcharge resilience), Whirlpool (consumer/durable demand concerns), University of Michigan confidence at 47, Straits of Hormuz AIS bottleneck, Magnificent Seven returns flattening (~5% over 6 months), AI beneficiaries/risks basket up 132% (12 months).
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOThe 10-10-10 Market Recovery
1:17 to 1:39
Discussing the recent market rally and its implications.
“10 % down, then 10 % up in 10 days that fixed all that was broken.”
Interview with Tom Nelson
1:39 to 2:18
Overview of insights from guest Tom Nelson on asset allocation.
“All this and much more on episode number 969 of the Disciplined Investor Podcast.”
Market Dynamics and Predictions
2:18 to 4:49
Analyzing current market dynamics and potential future trends.
“I'm Andrew Horowitz, your fine host and the founder of Horowitz & Company.”
Impact of Inflation on Companies
4:49 to 7:37
Examining how inflation affects various industries and companies.
“And all of a sudden we get some news that really is nothing more than we're going back just one step.”
Supply and Demand Challenges
7:37 to 14:00
Discussing the balance of supply and demand in the current market.
“And I kind of started thinking about what companies would be the most vulnerable.”
Market Outlook and Portfolio Strategies
14:00 to 15:08
Learn strategies to navigate market uncertainty without panic.
“We haven't seen a lot of things that are going to happen.”
Key Reversal Indicator Insights
15:10 to 16:10
Understand the implications of the key reversal indicator in market trends.
“Make objective adjustments to your portfolio.”
Tribute to Mark Mobius
18:47 to 19:46
Reflect on the legacy of Mark Mobius and his impact on emerging markets.
“Seriously, how do you keep that all in balance?”
Macroeconomic Trends and Inflation
19:47 to 24:41
Explore current inflation trends and their potential effects on the economy.
“Yeah, he was definitely an icon in our business.”
Supply Chain Challenges and Market Implications
24:42 to 28:00
Gain insights into supply chain issues affecting market prices and economic growth.
“an interesting study by the Fed recently, and their view is that the impact of tariffs basically leveled off in December, and that is no longer pushing prices higher.”
Show all 25 chapters
Straits of Hormuz and Agricultural Prices
28:00 to 29:10
Discuss the current situation in the Straits of Hormuz and its impact on agricultural prices.
“You mentioned that one of the things we do see is a clearing.”
Consumer Confidence Crisis
29:10 to 30:20
Explore the historic low in consumer confidence and its implications for the economy.
“I talked to somebody in the business in a restaurant recently.”
Analyzing Economic Indicators
30:20 to 32:50
Delve into the conflicting signals from employment and consumer sentiment indicators.
“Number two, what kind of credence, what kind of weight do you put into that particular?”
Capital Expenditures and AI Investment
32:50 to 35:00
Discuss the rise in capital expenditures related to AI and its potential market impact.
“How is that possibly, it seems to be conflicting to me.”
Transformative Power of AI
35:00 to 37:50
Examine how AI is reshaping investment strategies and market dynamics.
“I mean, astonishing numbers, never been seen before, not even close to what's been seen before.”
Implications of IPOs and Market Valuations
37:50 to 40:43
Analyze the potential impact of upcoming IPOs on market valuations and investor behavior.
“this is kind of like, if you think about like the internet boom, there'll be fits and starts as there were then.”
Financial Sector Insights
40:43 to 42:00
Review recent performances and outlooks of major banks amidst economic changes.
“which is essentially full valuation, which you don't usually have with companies.”
Tech Sector Analysis and Value vs Growth
42:00 to 45:50
Discussion on the current state of technology stocks and the dynamics between value and growth investing.
“You see crazy amounts of returns, Intel, SanDisk, WDC, you mentioned, you know, like even NVIDIA, all, I mean, rounding off the bottom.”
Emerging Markets and Economic Factors
45:50 to 48:20
Exploration of emerging markets, their performance, and the impact of geopolitical tensions.
“Now, that spread was more like 11 % or 12 % for a few days there, which was unbelievable.”
Investment Strategies in Uncertain Markets
48:20 to 52:30
Insights on managing investments during unpredictable market conditions and the importance of risk management.
“And so there was a lot that was going for emerging markets and looking out 6, 12, 24 months, very positive on that.”
Target Date Funds and 401k Insights
52:30 to 56:00
Discussion on target date funds, their relevance in 401k plans, and how investors can benefit from them.
“But generally, kind of plus or minus 10 % on the cross asset.”
Understanding Target Date Funds
56:00 to 57:29
Learn about the role and function of target date funds in retirement planning.
“whatever it is, some actively traded environment that that's what they do.”
The Evolution of Target Allocation Strategies
57:30 to 59:24
Explore how target allocation strategies have evolved to accommodate varying risk tolerances.
“You know, the whole crypto community was trying to get in there.”
Behavioral Aspects of Investment Choices
59:25 to 1:01:58
Discuss how behavioral finance influences investment choices among different risk profiles.
“rotating ever so gently throughout the years to a point where you get very little risk by the time you retire.”
Reflecting on Insights from Tom Nelson
1:01:59 to 1:03:10
A recap of key insights shared by guest Tom Nelson in the discussion.
“Make sure to check out all the things they have to offer.”
Transcript
Automatic transcript. May contain errors.0:00This episode is sponsored by Interactive Brokers. And will the Fed raise rates by 25 basis points this June? Interactive Brokers prediction markets recently priced the probabilities leaning towards no. But markets move fast. Trade prediction markets on political, climate, and economic events using simple yes or no contracts priced to reflect probabilities. Use those signals to inform your broader portfolio. Get it right and you'll receive$1 per contracted settlement, plus 3.14 % APY while your trade is open. Prediction contracts are not suitable for all investors. Learn more, though. I want you to go to ibkr.com slash predictions.
0:43The last trading day for this contract is June 17th. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of the Disciplined Investor Podcast. This episode of the Disciplined Investor is sponsored by Horowitz and Company. If you're looking for a portfolio manager, look no further. Horowitz and Company, from seed through harvest, cultivating financial success.
1:1710, 10, 10. 10 % down, then 10 % up in 10 days that fixed all that was broken. Key reversal indicator breaches an important level and employment, inflation, and eco still looking good. Our guest this week that will discuss all this and more is Tom Nelson, Senior Vice President and Head of Asset Allocation at Franklin Templeton. All this and much more on episode number 969 of the Disciplined Investor Podcast.
1:55And what do you think of that? That was a face ripper if I ever saw one. I mean, just wow, the short covering, the short squeeze, that move up from the bottom on just some information. There's no question of that, that we saw this incredible rally that it's the V. It's the V again. Welcome to the TDI podcast, The Disciplined Investor. I'm Andrew Horowitz, your fine host and the founder of Horowitz & Company. We're money managers. We're investment advisors. You know, it's much different what we do, by the way, than what you usually go to a stockbroker for. that many of you are probably using, by the way.
2:39You should get to know us. You'll understand why people have moved on from the traditional stock brokerage or bank lobby broker, or even the insurance agent that pretends to be an investment guy or gal, or anybody that is that commission-based, right? We do wealth management. Money management, investment advisory, wealth management, much different than the transaction-based, commission-based kind of relationship you have with someone who is not really acting as a fiduciary for you, doing it for the benefit of you. This is on the same side of the table that if you make more money, we make more money.
3:19You've heard that before from a variety of places on TV and commercials, but that is the kind of relationship that gives you that financial well-being and the ability to think clearly that the person who is doing things for you is doing things for you, right? They're not selling you, as I heard many years ago, hey, what do you do for a living? Somebody says, well, I sell commissions. I'm like, what? You do what? Yeah. They find people, they see a dollar sign in your head. How much can I squeeze out of that client? Much different than what's going on. Totally different experience. And that's why we have the ability to guide you each week with important insights on markets and finance.
4:01and even the economy. And you know what? We do that with some of the smartest people we know in the business. And today is another great example. We've got Tom Nelson coming on soon. But I have a few things, just a couple of things I want to touch upon before we get to that. The 10-10-10. 10-10-10. We had 10 % down just about for most markets, some a little bit more, some a little bit less in the U.S. Clearly in the international arena, Things broke down much more significantly and then actually turned around much more significantly. But basically that 10 % up or the recovery from those losses took an astonishing just 10 days.
4:42This is a market that has been rolling over throughout the entirety of 2026. And technology was really getting slammed. And all of a sudden we get some news that really is nothing more than we're going back just one step. even though we fell five and the markets recover. They do a V recovery. They hit all-time highs. And this is only after a little bit of insight on where the war is heading. The idea that we're not going to obliterate and end a civilization, which was a horrible thing to say, but that was what was said, and that we are going to conclude whatever this issue is. And a deal, some deal, whatever it means, is going to happen.
5:26Now, meanwhile, by the way, this V recovery happened in the face of some things that are really questionable. I contend, hold on to your socks here, folks, that we have yet to feel the pain of what is about to come from this inflation situation that's going to happen. Now, it's going to be probably contained to certain areas. In fact, I talked about this both on DH Unplugged this week and I was a guest on Frank Curzio's Wall Street Unplugged podcast. You got to get your hands on that. Go over to Twitter. I posted a couple of different clips from that that Frank sent over, and you can see the whole interview.
6:11It was a video-based interview on Spotify and a few other places. But that's all. The links are all going to be on my Twitter feed, Andrew Horowitz. One word is my Twitter feed. Make sure to follow that and you'll get some good stuff and little goodies here and there on that. In fact, we posted the KRI, which I'll get to in a second. But I talked about this issue. I talked about the higher cost of oil. We know that. We see it. It's right there in our face at all times. We see it at the gas pump. You turn on the television. That's all I could talk about. And this week, there was something much different in the demeanor of the market news that came out because there was, in fact, companies that have been talking about pushing up prices of their petrochemical-based products.
6:55So, for example, petrochemicals are a byproduct or utilize petroleum to make these things like polyethylene, right, plastic bags and bottles, polypropylene, which you got food containers and packaging and things of that nature. And then you got PVC, right? Pipes, tubings, polystyrene. You got like things like foam cups, right? Insulation for, I don't know, coolers or for housing or for whatever it may be. And then you got PET, which is a water and soda bottles, food packaging again. So food packaging comes up over and over again. Plastic bags, bottles is all this. And I kind of started thinking about what companies would be the most vulnerable.
7:41And I was kind of surprised what I saw because I did some research into this. And I looked at a variety of the companies like a J.B. Hunt, right? J.B. Hunt is vulnerable, but vulnerable potentially because this transportation. Margins are highly cyclical right now. They have the added cost of fuel. They pass it on these days. We allow this to happen as fuel surcharges. this pressure point, but they have pricing power that weakens quickly with the potential for freight demand softening. And surcharges, even though they put those on, don't always perfectly offset the timing of when the movement of the price of oil happens, right?
8:26The contracts that they have. They may have contracts in place already that they can't add a fuel surcharge on some of them. Now, many of the companies are smart, and they obviously put a fuel surcharge option and the potential into their contracts. And as such, they can move them at will. That's good. That's great. That works. Look at J.B. Hunt, symbol J-B-H-T. The reason why I say this is you would think that with some of the things that are going on right now, that this stock would maybe be in the doldrums or at least not favored. It's close to an all-time high or at least a reasonable high.
9:03In fact, let me look at a chart right now as we're talking about this. The fact that they are doing this well in an environment that, in fact, last week there was a big move up. Yeah, all-time high by a long shot. This is over the last five days, this stock went from 225 to 242, which is about 10 % up in the last five or six days. Well, last month, didn't skip a beat from 200 to 245. You're talking about$45. You're talking about a 20 % move in an environment that people are worried about what is going to happen with fuel calls, what's going to happen with demand, what's going to happen with transportation.
9:54Now, mind you, yes, there is something to be said about that we can't get boats and doing certain things around the country around the world, so maybe logistic companies are going to do a little bit better, but really? We're not looking a little bit further out, I guess. But okay, that was one. The other one that makes more sense in this environment, Whirlpool, for example, probably the top tier vulnerable company out there, they have this big ticket discretionary demand is what really is a major issue for them, right? The other thing is they have insane and intense competition. Huge competition when it comes to their products, their input costs, their material costs, their freight costs.
10:42Obviously, J.B. Hunt's going to get the benefit if they have a, or at least not take a hit if they have a fuel surcharge. But meanwhile, Whirlpool will. Now they'll pass that on and that is inflationary. Of course, we know that. But they're a tough setup for this company. Now, if you look at that chart, totally different situation. Looks like it could be bottoming out right now. I've been laying on this level for, I don't know, the last 20 days or so, maybe 30 days. It's come down dramatically for a while. The concern about what's going on with home building, higher interest rates, soft demand in that area, the question about employment.
11:18Again, it depends on what you want to look at, half full glass or half empty glass. And in the case of Whirlpool, half empty. Concern about all sorts of things that consumers may think about delaying purchase. But then you would think about, well, if that's the case, how come J.B. Hunt? If Whirlpool's not doing well, I mean, who carries those kinds of goods, those durable goods from place to places? Companies like J.B. Hunt. J.B. Hunt, not skipping a beat. Whirlpool, concern about consumer demand. Is it that the impact of the already, the cargo, the goods, the transports that were already in the pipeline are moving through and that's why J.B.
12:06Hunt is doing well? And then we're not really seeing that problem yet? I don't know, there's a lot of weird things going on. The fact is, when we see that there's all these ceasefire announcements, the 10-day ceasefire with Israel and Lebanon and the ceasefire that we have with Iran right now, let's be clear about something. There's a lot of talk about talk. Oil is still above 90. The Straits of Hormuz is still not open for business. Europe is expecting, this was a news item from just a couple of days ago, Europe is expecting to run out of jet fuel in six weeks. Now, that's a problem. Now, some of that will be resolved by U.S.
12:52sending that over, which we don't usually send on that route, but we will do that probably. We hear promises that something will happen that was going to be a ceasefire. But again, even if the Straits of Hormuz are open right now, Now, we're talking about 45 days essentially, or 40 days of closure up to this point. And the problem with that is that the backlog of what we need is a problem. But the demand destruction slash is not there yet. But the problem that we have is not demand destruction at this point. That's why markets are behaving well. We have supply destruction, which hasn't even peaked its head up yet.
13:33because we don't know exactly the extent of it. We know that there are natural gas facilities that are offline now for the next three to five years in the Middle East. We know that there are plenty of pipelines and production facilities and refining plants that are offline for a long time in the Middle East. But okay. There are all these promises, these things. People are excited. we're saying, you know what? We haven't seen a lot of things that are going to happen. We don't necessarily, I don't necessarily think that it's going to be terribly bad per se because there's ways that, we have a lot of ways to fix this.
14:16But proceeding with caution and that's what we're doing with our portfolios. That doesn't mean getting out and whacking and going to zero. No. What it means is that you readjust, you rebalance. And what we've seen right now And you probably noticed That for a period of Minutes Markets care But right now they don't just seem to care about any of this For the most part The companies that seem to have the most problems ahead Stock charts look kind of okay At least for now So let's be smart We're not going to get spooked here With what we do for our clients We're going to use the outlook to plan accordingly I don't want you to get spooked either That's my point.
14:59The whole point here is to give you that permission not to be afraid, not to be spooked, not to be so worried that you just throw away the baby with the bathwater. You know, be smart about this. Make objective adjustments to your portfolio. That's what I'm talking about. Be smart and objective. Don't use emotions. Now, in other news, I want to mention our key reversal indicator. It hit a plus six on Thursday with three clusters above the 0.3 for a while. That's an overheating market. We haven't seen that since about a year ago. And usually what that means is the roll is going to come. There has to be a cooling off of the markets.
15:40It doesn't necessarily mean there needs to be a huge correction, but there needs to be a moment that markets aren't racing ahead. Pretty much every indicator that I've looked at recently, whether it's the Spearman, whether it's RSI, whether it's advanced decline McClellan, the KRI, these are all looking pretty hot. And often what happens is there's a quick cool off period before the trend continues in setup, right? Usually the KRI that we have, key reversal indicator, is really, really good at turning points. It's better, much better actually, much, much better at oversold levels. When markets oversold, we start getting like a negative five, negative six.
16:30And dare I say ever, I think once I've ever seen a negative seven, that's the peak, that's the max. When you get to that level, what happens is that buyers come in. Short covering starts. Short covering is a great catalyst for a rally. That's what we saw in the last couple of weeks. You don't have the same catalyst for a sell-off. People generally speak, speaking, they hold on to the positions for dear life. They're more excited about lower prices. Higher prices, everybody thinks, eh, it's going to go higher than that. Don't worry about it. So this is much better on the oversold side, but when we get these clusters like we've seen either side, oversold or overheated, got to pay attention.
17:17It's important. I think it's important to do and not to slough it off. Let's talk about interactive brokers for a second here. You know, you research your investments, right? You analyze markets, but have you researched your broker? For the past three years, Interactive Brokers' individual clients, listen to this, averaged 24.3 % annual return, beating the S &P 500. Lower costs, competitive returns, competitive rates, and access to 170-plus global markets help investors keep more of what they earn. The broker that you choose matters. Interactive Brokers is a member of SIPC. Learn more at ibkr.com slash performance.
18:02Again, visit ibkr.com performance.
18:13So let's get to our guest. And our guest today is Tom Nelson. He's Senior Vice President and Head of Asset Allocation Portfolio Management for Franklin Templeton Investment Solutions. He's a member of the Investment Strategy and Research Committee as well. He's a portfolio manager of a number of the funds offered for sale at various jurisdictions. lead portfolio manager, Franklin Next Step Fund Series, Franklin VolSmart Allocation VIP and numerous model portfolio programs. He's a portfolio manager of Franklin Lifesmart. He does a lot. Tom, you wear a lot of hats. I do, I do. How do you keep it all together?
18:48Are they all interrelated or something? Seriously, how do you keep that all in balance? So we're structured such that we have kind of one investment committee that I co-chair, which drives our thinking on asset classes. We work with our manager research team to help drive our thinking on managers that we allocate to as asset allocators and security selectors. And although there are a number of strategies that I manage with different objectives, they kind of rhyme in terms of how they're managed. And so the business is pretty scalable from that perspective. Oh, that works. Obviously, I wouldn't expect that you'd be on one committee that is so different than the other that it would take a full-time job for that as well, right?
19:35Yeah. So let's pay a little homage to Mark Mobius, who passed away this week, 89 years old. The guy that the first time I heard emerging markets was, I think, uttered from his mouth. Yeah, he was definitely an icon in our business. Yeah, there's only a couple. Jim Rogers, I think, is one of them. I mean, he was, I put, I don't know why, I put Mobius and Rogers in that same genre. Yeah. Of gents that, you know, were kind of on that thing. Mark Mobius, I mean, he was definitely the most, I mean, who was, who did he start with? Did he start with Franklin Templeton? He was a Templeton guy for 30 years.
20:11Right. Yeah, that really, my opinion, tell me if I'm wrong, but history, I don't, you're more familiar, but he was one of the big reasons that Templeton really expanded because they were really known for their international at first as I saw it. Yes. Yeah, definitely a global manager and particularly kind of the Templeton side of the shop. I mean, it's been since the 1980s when Franklin had acquired Templeton, but that's very much a global orientation and he was a huge name in emerging markets. I think it was the Templeton Foreign Fund. That was the biggie. That was the first. By the way, that's all you had back then, right?
20:48Was there really anything else? Not very many. Not very much going on. I want to talk about some macro. I want to talk about inflation, PPI. We saw, or lack of inflation for that matter. We saw some numbers out this week. We saw the differential between core and the impact there. And I was kind of wondering in your perspective, what you guys are thinking over there at your firm. Are we starting to see demand destruction because of the higher oil prices when you see the difference between headline, which of course includes food and energy. and this PPI and non-headline, no regular core. By the way, an add to that on the heels of a relatively hot, but yet less than expected PCE number that came out just last week.
21:40So kind of put those into perspective on me and tell me where you guys are at on this. Yeah. It's still a little bit early, I would say. the turbulence that we've seen, which is kind of driven by the war in Iran, is very much a supply shock, right? And the largest energy supply shock that we have ever seen. And so will that lead to demand destruction? The expectation right now is for, if we're looking at economic growth like GDP, to be somewhere in the vicinity of 50 basis points lower globally than what the expectations were for 2026 going into the month of March. And so it's still a little bit early.
22:28The numbers on PPI and CPI are a little bit lighter than what we see on PCE, which is the Fed's preferred measure of inflation. And kind of the big difference between the PCE measures and your PPI and CPI are things like housing. And with housing being, I don't want to call it depressed, but let's say stable, that's a lower weight within core PCE. And so you're seeing a little bit higher numbers on that right there. Used car prices, they're still low, but leading indicators, think like the Mannheim used car index, those are inflecting higher. And so if you were to look at the Mannheim price index of used cars, that's going higher over the last couple of months.
23:18It tends to lead the CPI and the PPI version on – particularly the CPI on used cars. That's actually going down. That's likely going to change. It does take a little bit of time for higher energy prices to make their way into official inflation readings. You and I have talked offline about food costs and fertilizer. You know, roughly 30 % of the world's fertilizer transits through the Strait of Hormuz. And that is likely going to impact crop yields and feedstock for cows and chickens and ultimately lead to higher food costs. But that impact is probably going to be more acute in the second half of 2026 and into 2027.
24:01Um, inventories, you know, at, as, uh, as prices go higher, uh, inventories, there's enough inventory that for a couple of months they can be, they can be winnowed down a little bit without, uh, that leading to, to, to, to major price increases. But there's only so long that that can take. um and it's good for it's good for inventory heavy someone who's over inventoried right now is getting a real benefit because what's happening is their costs don't go up because if they're not refilling right now waiting it out they're waiting it out and hoping it comes down but their inventory is like up a lot therefore selling through making higher profitability for the moment right is that true yes absolutely yeah and then finally tariffs right so there was an interesting study by the Fed recently, and their view is that the impact of tariffs basically leveled off in December, and that is no longer pushing prices higher.
24:59And so we're seeing the impacts of tariffs, when that starts to go away, then all else being equal, the upward price pressure from those tariffs is no longer an issue and is no longer leading to higher prices. And so, like kind of getting back to the beginning, it's still a little bit early. The impact is likely to be higher prices and lower growth, but it's still not yet really starting to make its way into what we see as demand destruction and overall lower economic growth. So it's interesting because the market snapped back, the 10-10-10, the 10 % down, the 10 % up, and it took 10 days to basically recapture all of the down that we saw, even from the beginning of the year that we saw some of the movement down before the war that was going on.
25:53We saw a few all-time highs there, but generally speaking, there was kind of a slope down in a lot of sectors since the beginning of the year. We usually say that the markets are a discounting mechanism of forward probability, particularly about six months out in the future. This all sounds like six months out in the future to me, what you're telling me and what I, by the way, think also. But yet markets don't seem to care too much. Yeah, yeah. And we've seen earnings estimates continue to rise, right? They've only gone higher so far this year, but we are a little bit concerned about what the second half of 2026 and into 2027 could ultimately look like.
26:40There's so much that's kind of moving fast. There's so much uncertainty right now. And a lot ultimately depends upon how quickly things de-escalate in Iran and whether or not and how quickly the Strait of Hormuz kind of reopens. And the longer that this plays out, the more difficult it is going to be for economic growth. The other thing that we've taken note of is the fact that if you were to look at things like earnings estimates, and we're starting to get into the midst of earnings season right now. I believe it's not next week, but the week after is going to be the Super Bowl of earnings. And we're really looking forward more so to what companies are saying and the guidance that they're providing on a go forward basis.
27:28But empirically, stock prices tend to peak three months before earnings estimates peak, give or take. But just kind of that lead lag relationship is one that tends to be roughly a three month lead time on stock prices relative to earnings. And so a couple of weeks ago, we would have thought that, or we would have said that prices had peaked in January. Now we've since recouped all of those. But that could be a couple of months time, should we see some consolidation and maybe a small pullback here, that we could see earnings estimates start to roll over and go a little bit lower. You mentioned the Straits of Hormuz.
28:10You mentioned that one of the things we do see is a clearing. And right now there is no evidence that the Straits of Hormuz, that anything's happening besides boats moving forward, turning around and coming back. You could look at a chart of what's called AIS, the signatures that their transponders are putting out, and those are available. Just look up, anybody out there can look up Strait of Hormuz AIS map. And you can see there's a section, it's just a small section that basically is a bottleneck of an area, 21 mile width of region that virtually nothing's moving through. And as you mentioned, the longer this goes on, the longer problem we have, There's also the concern about supply versus demand, destruction, all that.
Read the full transcript
28:57But with all this that's going on and the fertilizer issues, by the way, I saw you saw that note that I wrote maybe, I don't know, three, four weeks ago about my concern about agricultural prices. Right. And all that. I talked to somebody in the business in a restaurant recently. They're buying tomatoes by the case that were twenty dollars per case. now are$70 per case. That's a lot. If you're serving burgers, salads, I don't know, whatever else it may be, that adds up very quickly into a restaurant. Not to mention the fact that you have petrochemical prices going on. We saw that a couple of different companies this week announced that they're increasing the prices by 20 % to 30 % this month and another 20 % next month on their various goods like the chemicals that you put and utilize for packaging.
29:53Packaging is everything. So a lot's happening that I think markets are ignoring, hoping that this comes to fruition. But, Tom, consumers are not. We saw a historic reading just last week, at the end of last week, of the University of Michigan Consumer Confidence. First, what was your comment on that? I think it was down to 47 in the 70 year history of University of Michigan putting this out has never been that low. Number one. Number two, what kind of credence, what kind of weight do you put into that particular? Because for a long time it was pretty heavy people. What kind of weight do you put into that?
30:32And then please tell me what it means. Yeah, I think maybe to start at the end and work my way back is it means that people are concerned. People are unhappy with the situation that they're in. they are generally negative on the outlook for the economy and for their own kind of personal situation. Now, having said that, we would prefer to judge what people do and what corporates do as opposed to what they say, right? And so we would put a little bit less emphasis on consumer confidence, looking at things like retail sales, what they're actually doing. They're continuing to spend money and retail sales are, I would say, fairly strong, actually.
31:19Kind of sitting in the middle there between what people feel and what people do are metrics around intentions of people and businesses. And so on the corporate side, there are some small business optimism indices from the National Federation of Small Businesses that have pretty strong correlations to forward returns, particularly one, small business hiring plans, and then secondarily, small business capital expenditure plans. Those are pretty reliable indicators. And when the small business hiring plans are below kind of both their one year and their five year smoothings or their moving averages, equity returns are essentially zero since 1990.
32:02On the other side, when they are higher, i.e. their expectations for hiring are that companies are going to be hiring. You see stocks returning about 13 % annually. Over the last two months, we've actually moved from one whereby hiring plans were kind of modestly positive to now below those moving averages, which is a little bit concerning. To your point about consumer confidence, small business CapEx plans, That's at the levels that we've not seen since 2009, right after the official end of the global financial crisis. Then how do you explain that we see initial claims at 207? We see unemployment rate miraculously at 4.3.
32:46We see hiring, I think it was, what was it, 177 last month for the, is that the right number? 177 reds? Payrolls was a really nice number. Really nice. How is that possibly, it seems to be conflicting to me. Yeah, 178. You're pretty darn close. It is conflicting, and I don't have a perfect answer for you. And it's one of those things. That's the interesting thing. You know, I know they say that you can't – economics and markets are two separate animals, and sometimes they come together, and it may be more coincidence than it is anything else, right? You know, that idea. But it seems to me, though, and by the way, when I first started in this career and I was looking at indications of what exactly I would be looking at to prepare for the future of what I would be looking at, we created incredible – we still have chart books that we utilize.
33:38We still look at them, but they're just not as useful anymore because the correlation of things like either hiring, firing, GDP numbers, consumer confidence, it doesn't seem to matter. All that matters is if the government is stimulating, if somebody is talking up the markets, and I guess what the Fed is doing. I mean, that's – or take that – the Fed and put that on and overlay that on central banks around the world. Right. And now you have even sovereign wealth funds with unlimited time horizons. There used to be pension funds, but they got themselves in a little bit trouble with things. But you got sovereign wealth funds that have unlimited time horizons that they don't care what price they invest in.
34:25Right. Yeah. So maybe that's all that. I don't know. Let's switch over to the AI trade, shall we? Kind of sauntering over there. Is there more CapEx, I guess, CapEx expenditures for the first, I don't know, the last, we'll call it, better part of what? One and a half year, two years? I'll stretch it out to two years. One and a half years or so, CapEx expenditures, the money that was going to be spent on the buildout of various things, whether it's machinery, chips, whether it's going to be data centers, whether it's going to be electricity, power, unbelievable numbers, right? I mean, astonishing numbers, never been seen before, not even close to what's been seen before.
35:06I heard on Bloomberg just this week, somebody was talking about, he was a really, really smart guy, I thought, and he was talking about the difference between earnings and free cash flow. And the idea that there is going to be, there has been, there's going to be a divide between the two, a chasm between the two that is unlike you've ever seen before because the cap expenditures coming out of free cash flow, a lot of it. Is that a concern? Is that something we need to be worried about? Or is, again, maybe that's something we're looking at, but markets are going to be like, oh, who cares? is for the better good, greater good in the future.
35:43It's going to aid us. It's going to bring in a lot of money. Yeah. Very good question. There's a whole bunch of different kind of layers to that. But, you know, what we've seen is that there's been a massive spend on AI and there continues to be a massive push. And, you know, we were just in a kind of call with our broader team today. And one of the comments that I'll take away that's relevant for this year is that AI, first of all, is part and parcel to our investment processes today. And it's only going to continue to accelerate. And if you don't think that is going to be a big part of what we do, and we're only one small industry, if you will, you kind of have blinders on, right?
36:29And so there has been a little bit of a concern. And this has been going on for as much as like six months from now, particularly with like the hyperscalers, like the Magnificent Seven kind of names that have moved from basically taking a lot of their free cash flow and buying back stock, which reduces the number of shares outstanding and all else being equal, increases earnings per share, right? Artificially. Yes. But it does increase your earnings, you know, to your point about earnings versus cash flow, and to now taking a lot of that cash and putting it to a greater extent into capital expenditures, which doesn't obviously impact earnings per share.
37:17And those capital expenditures take quite a long time to ultimately play out and understand what the return on that investment is going to be. And there are some concerns that it will weigh on, all else being equal relative to what they were doing in the past, weigh on earnings per share. And so we've basically seen a flatlining of the returns of the Magnificent Seven over the last six months or so. They're up like 5 % or so. Having said that, this is kind of like, if you think about like the internet boom, there'll be fits and starts as there were then. We're believers that AI can be transformative.
37:59We've seen this week TSMC come out and kind of with a beat and a raise and guidance that really helps to reinforce the resiliency of AI infrastructure demand. And so while it may take a while to ultimately play out, and we don't know how things will play out until then, the fact is the companies that are beneficiaries of AI are being rewarded a heck of a lot more than companies that are at risk from AI. And so there's a long, short basket. So it's long the AI beneficiaries and it's short those that are at risk. That basket has returned 132 % in the last 12 months. And those beneficiaries don't only include tech companies, but also utilities and industrial companies, energy companies.
39:01And then the short side of that basket, those that are at risk, actually has a higher weight to the tech sector, but it's more weighted towards application software and IT consulting and data processing companies that in some ways may be at risk and some companies could be kind of squeezed out from that perspective. And so we do believe it is transformative, particularly if used in the right way. There are going to be some winners and some losers, but there is a massive build out that is occurring. And it does affect more than just the average technology company. They also saw this week that Google came out.
39:41There was some analysis that showed that they're going to have about$100 billion windfall from the OpenAI IPO when it comes out. That's the embedded value there. And there's other companies too. Microsoft also has a huge position there as well. People knew about that. And then, you know, you go down the list of all the other ones that, you know, you have the Anthropic that supposedly is going to come this year. So we have SpaceX, OpenAI, and Anthropic, right? Those are the three that are supposedly going to suck all the juice out of the markets right now at a full valuation. and I'm going to be so interested in watching the SpaceX IPO that everybody wants to get into, so they believe there'll be a nice pop.
40:23The question is going to be, and by the way, the NASDAQ made room for a five-day window only for them to enter into the NASDAQ 100 index, which is unheard of. And then secondly, what's going to happen when the rug gets pulled when insiders sell that lofty valuation, supposedly 1.7 billion, which is essentially full valuation, which you don't usually have with companies. You get the growth and they just did it all in the background here. Interesting. You mentioned earnings season. We're right in the middle of it. Banks looks like they did pretty well. Wells Fargo is probably the only one that didn't do as well.
41:01They maybe didn't have as much investment trading. The investment work was the biggest side of this. So it's kind of interesting that banks are looking like, and they said, JP Morgan, Jamie Dimon said that it doesn't look like the consumer is really having too much difficulty right now. I think Brian Moynihan from Bank of America also said the same thing. So generally speaking, banks are saying things are good. The yield curve is favorable, not as favorable as it was, but favorable for them. That's a good start. I always find that when banks seemingly start off, everything is all peaches and cream and then just wait a week, just wait a week and things get a little bit crazy.
41:39But that's happening. But that's the value side, right? For a while, we saw the value side, the staples, the utilities, certain healthcare, but not biotech. What am I missing there? Financials and energy. So this was doing really well for a while, then all of a sudden, you kind of go 10, 12 days, you see Microsoft up, I think, 20 % in the last 10 days. You see crazy amounts of returns, Intel, SanDisk, WDC, you mentioned, you know, like even NVIDIA, all, I mean, rounding off the bottom. And I do wonder, by the way, is there something to be said about, hey, we know there's going to be inflationary pressures out there, but how's that going to impact the margins of technology?
42:24Technology, it's not like these guys need, they're not, it's like, okay, hey, Tom, technology company, I'm a buyer. Tom, do me a favor. I need you to ship me X amount of technology. That doesn't go over by train, by plane, by whatever. It just, you know, somehow over the airways. I get it. But the thing here is that maybe that's one of the reasons rotation came back really strong because it seems to be absurdly strong from where it was. But that's the value versus growth discussion. Is this another false start for value over growth? So our models, and we have kind of empirical investors, so we're constantly on the lookout for kind of what factors can be insightful in providing insights as to forward returns across and within asset classes.
43:15So we have kind of a growth versus a value model. It is essentially neutral right now. So, you know, that's kind of a that's kind of a toss up. But here are a couple of data points that I think are really relevant. Growth, for example, if you're just to look at like the Russell 1000 growth index and some of the important sectors like like tech, for example, growth has has has derated. And the NASDAQ, NASDAQ 100, the information technology sector are now trading below their 10 year average multiples. So they've kind of come back from the stratosphere. If you go back a couple of weeks from now, I think it was like two or three weeks ago, ExxonMobil was trading at higher multiples than NVIDIA in terms of forward PEs.
44:06Now, that's reversed itself over the last couple of weeks as the markets have done quite well. And energy has retraced a lot of their rally in the month of March. But if we're looking forward and if we have a view that growth is going to slow a little bit, we're in an environment right now, if you look at some of the composite leading indicators that we track, where growth is positive, but it's kind of slowing at the margin. It's decelerating. That's an environment where overall stock market returns are pretty much average, if you will. But what factors perform best in that environment, particularly on the deceleration, is growth and is quality, right?
44:50And if you think about those larger technology names, they have both, right? They're growth companies. They're growing at the fastest amongst all sectors of the market. And they've got high-quality balance sheets, right? They've got a really wide moat. And so do you really want to be betting against the largest companies generating massive cash flows with solid balance sheets and trading at a roughly 20 % valuation discount to where it was six months ago? Probably not. And in an environment where growth is slowing, people are going to pay up for growth because it is a scarce resource, if you will.
45:28And so if I had to choose between value and growth and close my eyes for the next 12 months, I would, without a lot of conviction, but I would tilt myself towards growth. Yeah, I mean, right now, I think the number, if I'm not mistaken, the differential between the value side, the Russell 1000 value, the Russell 1000 growth, is somewhere about favoring this year to date, I think it was 6 % or 7 % in favor of value. Now, that spread was more like 11 % or 12 % for a few days there, which was unbelievable. And last year, value also did very well. These are the things that were really fascinating about last year.
46:05You got value, you got emerging markets leading into this year as well. Dollar coming down, more of a safety trade, more of the conservative model, more of the blue chips are considered the value side of things. Really kind of interesting stuff going on. But as we're talking about EM now, dollar did move down for a while. The safety trade came in, right? We saw the Swiss franc, the usual place. It used to be the yen too, by the way. The yen was always, but that's no longer. The yen is just disintegrating right before our eyes. And that's why everybody that I know, I'm like, you're going on vacation?
46:34Where are you going? Japan, Japan, Japan. Everybody's going to Japan. Are you going to Japan? I'm not. Yeah. We should go. We should go. But everybody's going to Japan. Seriously, like everybody's going to Japan. And understandably, because the yen is what, at 160, 159 or so. And what's really fascinating about all this is that really benefited emerging markets. Emerging markets were for years really not doing well. And once, though, the dollar turned around during this war, let's call it March, emerging markets got obliterated. Just obliterated because they thought that, number one, South Korea is in there and South Korea has, let me calculate, zero oil reserves.
47:20and they needed everything they can because they get their stuff from Iran or through the Straits of Hormuz and everybody's like, how are we going to do this? So long story short, do we still have a plan to invest and a desire to invest in EM? I would say in short, yes. Going into March, right, so at the start of the hostilities in the Middle East, we were in favor of emerging markets. We were also in favor of Japan. But in emerging markets, they show best on earnings and economic growth. Earnings revision, which can be a powerful factor, earnings revisions in emerging markets have been better than even the U.S.
48:03and the rest of the world. They have more fiscal and monetary policy flexibility than developed markets, which might be important tools as we look out through the rest of this year. They're improving their corporate governance, which is marginal, but it's a positive. and the weakening confidence in the US dollar is also a tailwind. And so there was a lot that was going for emerging markets and looking out 6, 12, 24 months, very positive on that. The war in Iran has absolutely dented the trade, but we don't think it's completely disintegrated it. To your point, EMs, Japan as well, but those are asset classes that are pretty large oil importers and specifically oil importers from the Middle East and Asia, which is a large portion of the emerging markets index, specifically so.
48:58So they've naturally been hit hard in the recent turbulence. They've also rallied the most off of the bottom, right? And so - That was incredible. That was a big rally. The COSPI in Korea is up 20 % month to date. And we're only in the middle of April right now. and emerging markets are up roughly 12%. Both are obviously better than the rest of the world. And so ultimately how things play out will depend upon the conflict and the duration and the intensity and all those kinds of things. But sitting here today, we're still positive on emerging markets. And one of the things that we've done with so much uncertainty around us, when you're uncertain about things, you should have less confidence in things.
49:42When you have less confidence in things, You should take less risk. And we've been bringing a lot of our kind of active positions closer to neutral, if you will. And we've done the same with emerging markets. So it's interesting because I like that. That's something you've mentioned twice now. And I think it would be really helpful for people that are listening to understand more about what does that mean when you say things like, you know, we're going to neutral. You know, we're going to overweight. Now, by the very nature of a fund group that tracks an index, you can't get too far away from the center line.
50:22Is that a true statement? Yeah, yeah. So in overweight, if we're overweighting, I don't know, pick something. If the weight of a particular benchmark that you are looking at but that you want to massage around and it's actively traded, It could be your own benchmark. It doesn't matter what the benchmark is. Is let's say, you know, 10 % emerging markets is an overweight. It's not 20%, right? It's more like 12 to 15, maybe? Yeah, it depends on the portfolio, right? And it depends on the flexibility that we've been given. But for the most part, excuse me, if you think about like a portfolio with a moderate amount of risk, Generally, that's the quintessential 60-40 portfolio, 60 % equities, 40 % fixed income.
51:12And for portfolios that we manage that are intended to be stable, predictable, long-term investments, we can be plus or minus 10 % equities versus fixed income. And it's not often that we - That means 70, 60, it can be 70 or 40, or does it mean 10 % differential from the 60? From the 60. So equities can be anywhere from 70. Right, yeah, okay. Yeah, with neutral. And bonds can be anywhere from 30 to 50. And then within asset classes, so let's just think regionally in equities, you know, plus or minus 10 % similarly is about right. And so one of the things that you don't necessarily want to do is have a high conviction view and be wrong, right?
52:05And so we will be, for the most part, plus or minus five on emerging markets. And that's a riskier asset class, a riskier region than the rest of the world. And so you want to calibrate things based upon how much risk they contribute to the portfolio overall. and those assets that are a little bit more stable, you can afford to have a little bit more leeway around that without getting too far out over your skis in terms of risk. But generally, kind of plus or minus 10 % on the cross asset. So equities versus bonds versus cash, for example. And then plus or minus 10, as a general rule of thumb, U.S.
52:48versus international versus emerging. I'm talking very obviously fine level. So what about, you mentioned the word predictable. What part of the process matters most when markets are unpredictable? You have a whole big process, I know. But what is it that when markets become unpredictable, what is it that you do that matters the most to make sure that you stay where you want the portfolio to be? Does that make sense? Humility? Yeah. Maybe it's humility. Right. Yeah. There are times when you want to be on your front foot and you you kind of want to be pressing on the gas pedal. There are times that you want to have your foot firmly on the brakes.
53:33But there's also times kind of like now where you don't need to be a hero and kind of perhaps pull over and wait for the turbulence without a ton of, you know, without taking a ton of directional risk. And when things are unpredictable, like I said, it's there's not a perfect playbook for anything, but a playbook for geopolitical tensions is one that is really, really difficult to to game plan for. And so I just laugh because especially with geopolitics, it played out on Twitter. Yes. And I don't know what the next social media post is going to be. Yeah. People who do and have a lot of confidence in that are probably not telling the truth.
54:16Yeah. And and so when when risks go higher, when correlations go higher and when uncertainty is high, you know, those those are one of those times that you just don't want to take a lot of active risk relative to, you know, whether your benchmark is not losing money or it's some sort of a market based benchmark. and kind of wait the play out and wait for the fog to kind of lift. So is that, when you talk about risk in this headline-driven, choppy environment and all that, is that kind of good risk management? Is kind of adjusting at the edges right now, looking at, I'm putting words in your mouth here because I think we've talked about this, but look at now, But always have the forward view also squarely in focus so that you don't miss that opportunity and do something stupid because of a near term situation.
55:18Yeah, yeah. And, you know, in uncertain environments like now, it's not a great time to take undue risks. It's not a great time to try to be a hero, right? Particularly when it's really difficult to have any sort of edge on things. And getting it wrong loses credibility and there's career risks in that. And that's important because that's the point, right? The career risk is important to look at. I mean, look, we could say, well, that's selfish of the portfolio manager. But the fact is that if you're investing in a particular portfolio and you want to do a certain thing and your manager goes off the reservation in a bad time, that's just, yeah, there are some funds that you invest in or ETF or whatever it is, some actively traded environment that that's what they do.
56:19Right. And you can't be upset about that. But I think that that is one of the ways that you hold your manager accountable for style drift issues. That's the point, right? Yeah, you got to be true to your style and you're more easily forgiven for not making enough when things are going well than you are for losing a lot of money when things are going poorly. Yeah. Let's just finish up on this. I want to talk about target dated funds and target allocations. First of all, I find it fascinating that most 401ks, you do a lot of 401k business, I know you guys do. And target date funds are a big part of that because people that can't decide, they basically get an actively managed portfolio packaged that should be theoretically appropriate either for a risk or age-based process.
57:16The target date, first of all, have you been hearing anything at all about the potential to put ETFs inside of 401k plans? ETFs or? ETFs. Alts. Forget about alts and all that stuff. You know, the whole crypto community was trying to get in there. And thank God we had a little bit of a blow up where private credit, private equity is probably never going to get in there now. So I'm actually morbidly thrilled about this happening for the benefit of the average 401k participant, to be honest with you. But let's talk about – that's my opinion. You may differ. But ETFs, are they coming – are they going to get in there?
57:55Yeah, yeah. And so target date funds can come into a couple of different types of wrappers. And we have some that are managed in different – without getting into too much details – into different types of wrappers. But what you find under the hood, whether it's a mutual fund or a collective investment trust or a separately managed account, can be mutual funds. It could be ETFs. It could be individual securities. But what is probably most common are underlying mutual funds. ETFs are getting utilized a lot more, partly because you can get, in the case of passive, you can get market exposure at a very low price, right?
58:40And so every basis point that you're paying is a basis point that's not going to your returns that you're saving for retirement. So it's not necessarily a race to a bottom, but cost really matters in that target date space. Have there been any change? I saw one big change a number of years ago. For a long time, target-based funds. And by the way, target-based funds for descriptive, for those of you that are listening that are like, what is this guy talking about? Essentially, it's something like this. If we have a target date fund, if you're 30 years old and you look at your retirement at age 65 just as a number, that's 35 years from now.
59:19What happens is that that would be a, quote, unquote, 35-year portfolio until you retire, starting off with maybe a high amount of equities, rotating ever so gently throughout the years to a point where you get very little risk by the time you retire. Just from a very easy-looking standpoint. That's how it was in the beginning. It was easy to understand. What happens is that you would stay in that. You did not have to move because as you got closer and closer to retirement, it would just do its thing naturally. There was an advent of a risk-based target allocation fund that would change based on not only age but risk factors.
1:00:02It's kind of a multifaceted way of constructing the portfolio, right? Is there anything else new on the horizon for this at all?
1:00:16Most likely not. What we've seen, and we've had outside of the US and in some other countries, we've had target date funds that have three separate and distinct, or had, we no longer have them, three separate and distinct levels of risk tolerance. And the idea there is that you and I could be roughly the same age, and therefore our high-level kind of profiles would have a very similar level of risk tolerance. But we could have different situations from a financial perspective. We could also have a different attitude towards risk. And the examples that I would use, I could see my wife in a casino with her friends, and they would do very different things.
1:01:10And some would be very conservative, some would be much more aggressive. And it gives people an extra layer of flexibility for those who want to take on more risk, who are comfortable taking on a little bit more risk or less risk to opt for the more aggressive glide path or the aggressive fund, if you will, or the more conservative. What we have found is that most people will default to what's in the middle. And so the asset gathering in the more conservative and the more aggressive ones was not anywhere near that of the moderate funds. And so generally what we found and what we ultimately did, this is a couple of years ago, is just defaulted everybody back to the moderate fund.
1:01:58That makes sense. And play a little bit further up or down that glide path if you want to take on a little bit more or a little bit less risk. I hear you. Tom Nelson, thanks for joining us. I really appreciate it. Tom Nelson, Franklin Templeton Funds. Make sure to check out all the things they have to offer. And I appreciate all the wisdom that you've provided us today. Thanks. It was great. Thank you, Andrew. Thanks. A lot of information there, a lot of discussion about all sorts of things from macro environment, from economic indicators to consumer confidence in the AI trade. Tom Nelson was great.
1:02:29Thank you so much for that. Another great discussion with another great guest that we had this week. And, of course, rolling down into the end of April, we have more great guests coming up. We have a whole host of great people. Wes Gray's coming up in the next couple of weeks. Plus, plus, plus. It's going to be good. Make sure to keep your dial pointed to the Disciplined Investor Podcast on Apple Podcasts, Spotify, YouTube. Amazon. It's all over the place. Make sure to stay tuned and be here next week as well. I look forward to seeing you then. Thanks.
1:03:10This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principle and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz and Company Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements.
1:03:48Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement. Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures as well as a copy of our form CRS. Advertisement are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates of Horowitz and Company.
From the publisher
10-10-10: 10% Down, then 10% all and 10 days to fixed all that was broken.
Key Reversal Indicator breaches an important level.
Employment, Inflation and eco still looking good.
Our guest this week that will discuss all of this and More is Tom Nelson ,SVP and head of Asset allocation at Franklin Templeton.
NEW! DOWNLOAD THIS EPISODE’S AI GENERATED SHOW NOTES (Guest Segment)
Tom Nelson is a senior vice president and head of asset allocation portfolio management for Franklin Templeton Investment Solutions. He is a member of the Investment Strategy & Research Committee.
He is a portfolio manager of a number of funds offered for sale in various jurisdictions. He is lead portfolio manager of the Franklin NextStep Fund series, the Franklin VolSmart Allocation VIP Fund and numerous model portfolio programs. He is portfolio manager of Franklin LifeSmart Retirement Target Funds, the Franklin Fund Allocator Series available in the United States and several custom institutional portfolio mandates.
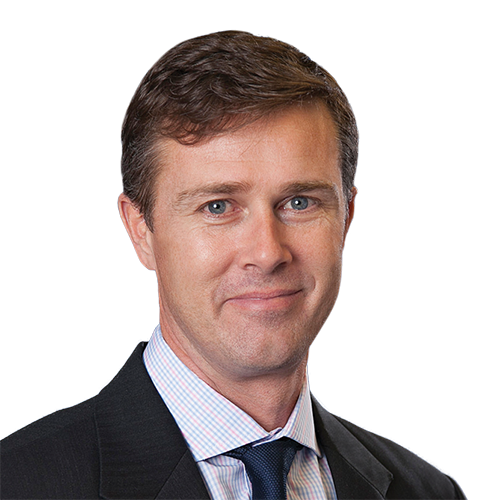
Mr. Nelson joined Franklin Templeton in 2007 and co-founded the firm’s quantitative research services group upon joining the company. He moved to Franklin Templeton Investment Solutions in 2009. Prior to working at Franklin Templeton, Mr. Nelson worked for Bloomberg LP from 1991 to 2007, where he was most recently manager of the Americas market specialist teams.
Mr. Nelson holds a B.S. in accounting from the University of Delaware. He is a Chartered Financial Analyst (CFA) charterholder and a Chartered Alternative Investment Analyst (CAIA) charterholder. He is a member of the CFA Institute, the New York Society of Security Analysts and the Chartered Alternative Investment Analyst Association.
Check this out and find out more at: http://www.interactivebrokers.com/
Looking to invest in The Disciplined Investor Managed Growth Strategy?
Click HERE for the virtual tour.
Stocks Mentioned in the Episode: (EWY), (NVDA), (JPM), (BAC), (TSMC), (AMZN), (WFC)