
In short
The Disciplined Investor episode argues that inflation, rising yields, and high energy costs are driven by long-running fiscal spending and weak “confidence,” and warns investors not to rely on fund names/labels. It also discusses how financial journalism has changed (fragmentation, speed, verification) and how Reuters uses AI tools while maintaining verification standards.
Guest backgrounds
David Gaffin is U.S. Breaking News editor at Reuters (nearly two decades). He previously served as U.S. energy editor and U.S. deputy markets editor, covering the 2008 financial crisis and the 2020 oil market meltdown. He won a 2015 Lieb Award for articles on the growth of stock buybacks.
Key claims
Fund “labels” can hide different index methodologies and exposures (even between similarly named ETFs). Market stress is linked to fiscal deficits raising bond yield pressure. Polling may skew toward people willing to respond, and AI should assist but not replace verification.
Notable examples
EEM vs SPEM emerging-market ETFs—MSCI includes South Korea (developed vs S&P classification), so EEM can outperform when Korea/semiconductors rally. Fidelity Contrafund’s “contra” label allegedly obscures its large-cap growth orientation. Reuters AI example: combining California gasoline inventory Excel lines to find whether inventories hit the lowest level in ~24 years.
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOCurrent Economic Landscape
0:58 to 1:30
Discussion on inflation trends and rising oil prices.
“Total PPI was up 5.4 % year over year, up from 4.8 % in July.”
Analyzing Inflation and Spending
2:07 to 4:48
Exploration of inflation, government spending, and economic implications.
“I'm here to tell you what's going on because don't let anybody tell you anything differently.”
Understanding Investment Funds
4:48 to 7:01
A critical look at mutual funds and ETFs, emphasizing the importance of knowing what’s inside them.
“We don't have any checks and balance in terms of what we're spending.”
Case Study: Emerging Market ETFs
7:01 to 13:20
In-depth analysis of two emerging market ETFs and their differing performances.
“The mutual fund and the ETF industry has done an absolutely brilliant job of creating these neat little categories for everything.”
Misleading Fund Names
13:20 to 14:00
Discussion on the potential confusion caused by fund names that do not reflect their actual strategies.
“The label on a lot of these is simply marketing.”
Understanding Fund Labels and Their Implications
14:00 to 19:41
Learn why fund names can be misleading and the importance of analyzing underlying investments.
“That describes what the manager's doing.”
The Evolution of Financial Journalism
20:21 to 28:00
Explore how financial journalism has transformed in the past two decades.
“It's been a busy summer, as always, but it seems to always be busy these days.”
Challenges of Reporting in Real-Time
28:00 to 28:32
Learn about the difficulties journalists face when reporting fast-changing market information.
“And so it puts us in that difficult position of having to report on something that is coming from a place that may not be, you know, something that can be verified.”
The Role of AI in Journalism
28:32 to 30:10
Explore how AI tools are being utilized in journalism for efficiency and effectiveness.
“looping this last point about journalism today about AI, because AI clearly plays, I could tell you something, it is my, you know, my grammar and my spell check, right?”
Limitations of AI in Content Creation
30:10 to 31:31
Understand the limitations and challenges of AI in generating journalistic content.
“Because often, And, you know, when I've tried or I've experimented with the writing elements of it, I find it a little bit stilted.”
Show all 25 chapters
AI's Impact on Data Analysis
31:31 to 33:32
Discover how AI streamlines data analysis and enhances journalism but still requires human oversight.
“It can pick out errors, that kind of thing.”
The Dual Nature of AI in News Reporting
33:32 to 34:34
Examine both the benefits and pitfalls of using AI in news reporting and how it can affect trust.
“It often, perhaps your hunches are still something that are intuitive and better.”
Polling and Confidence in Elections
34:34 to 35:32
Discuss the current state of polling and its implications for public trust in elections.
“And so, you know, it has much that it can do that will streamline some things.”
The Fragility of Trust in Political Systems
35:32 to 37:28
Learn about how confidence affects the stability of political and economic systems.
“We have midterms coming up and polling is a big issue.”
The Importance of Confidence in Financial Systems
37:28 to 39:31
Understand how confidence plays a crucial role in financial markets and their stability.
“Republican Party, which is currently in power than a polling result of a popularity level of 33 percent, which is much more dire, as you would imagine.”
Market Valuations and Economic Indicators
39:31 to 41:20
Explore the current state of market valuations and the indicators affecting them.
“And then, you know, everything that ensued from there, you know, and you're right.”
Consumer Spending and Economic Trends
41:20 to 42:00
Analyze consumer spending trends in the context of economic pressures and AI investments.
“You know, it's a hard thing to say right now because there are a lot of things that would say to you that there are real things to be concerned about.”
Consumer Spending and Market Dynamics
42:00 to 43:34
Explore how consumer spending impacts market levels and company strategies.
“again, companies and for individuals and say to yourself, well, does the market really belong at this level, which is just a shade or two below an all time record.”
Debt and Technology Investment
43:34 to 45:27
Discuss the implications of rising debt and heavy technology investments.
“It's pretty amazing what that's happened.”
Inflation Trends and Economic Impact
45:27 to 46:52
Analyze current inflation trends and their effects on the economy.
“Borrowing costs cannot just be sort of waved away.”
Energy Costs and Economic Pressure
46:52 to 48:29
Understand the impact of rising energy costs on consumers and the economy.
“It's really – isn't it really just energy and food are the two major plays in this right now?”
The Straits of Hormuz and Energy Supply
48:29 to 50:23
Examine the significance of the Straits of Hormuz on global energy supply chains.
“There is a pain threshold and we are well above four dollars a gallon on retail gasoline.”
Potential Energy Shock and Market Reactions
50:23 to 51:46
Evaluate the risk of an energy shock and its implications for the market.
“And that may be something that does create – well, I'll ask you.”
Future Trends in Technology and Economics
51:46 to 55:27
Discuss key trends in technology and their impact on future economics.
“And, you know, you've had these refineries shut down or attacked in, you know, Russia and Ukraine, which is refining supply and, of course, in the Middle East.”
Introduction to the Disciplined Investor
56:00 to 57:14
Learn how to connect with the show and access investment strategies.
“I stay in the office late in the studio that night.”
Transcript
Automatic transcript. May contain errors.0:00This episode is sponsored by Interactive Brokers. And we know that you research your investments, you analyze markets, you manage risk. But have you researched your broker? For the past three years, Interactive Brokers' individual clients averaged an annual return of 24.3 % compared to 23.1 % on the S &P 500. IBKR's lower trading costs, competitive rates, efficient execution, and access to over 170 global markets help investors keep more of what they earn and put more capital to work. Over time, the broker you choose matters. Interactive Brokers, member SIPC. If you care about performance, find out why the best informed investors choose Interactive Brokers at ibkr.com slash performance.
0:53Visit ibkr.com slash performance.
1:29Total PPI was up 5.4 % year over year, up from 4.8 % in July. Yes, we have inflation. Oil rocking higher. WTI breaks above 100. And asking, do we really know our funds? Our guest today is David Gaffin from the Reuters Breaking News Desk. All this and much more on episode number 990 of the Disciplined Investor Podcast.
2:06And yes, we have inflation. This is Andrew Horowitz. I'm here to tell you what's going on because don't let anybody tell you anything differently. The fact is, we all know yields are up, oil's up, up, up a lot, and it's more expensive right now than ever than it's been before. In fact, we saw that in the last month, Labor Day, we saw that diesel was the most expensive that has been on any other Labor Day in history. And for all of us, I think the problem we have right now is that it's more expensive than ever. And it's not just one administration's fault. The fact of the matter is, when you look at what's going on, actually, I'll go so far as saying that if we're looking for blame, it's probably the fault of every single administration since the great financial crisis.
3:08much of what's going on right now is, I think, deep-rooted in this populism type of situation that's been going on in terms of politics. It's been on the rise. Everybody wants a piece of the action. And governments are, I mean, they're more than happy to just say, sure, let me give you some money. Let's appease our constituents. They want to spread the wealth, right? They want to give out to make everybody happy, even if, and here's the funny thing, even if they don't have it. I mean, just look at the comments this week from a few of the people in our current administration when they talked about giving$5 ,000 to everyone if the Republicans win the midterms.
4:01Hello? Where are we getting that money from? I mean, it's another trillion dollars that's going to be added on to the debt. What do we got now? 41 trillion or something? So what's another trillion? But this is going to weigh on us. The cost of capital, the cost of servicing that debt, and that is why bonds are struggling right now because no wonder this week when the 10-year yield clipped 5%. I mean, does anybody have any other thoughts on why that is? The spending is out of control. And that's not going to stop anytime soon. Are we really all going to get$5 ,000 a piece? Maybe. Probably not. Taxes aren't going up.
4:55We don't have any checks and balance in terms of what we're spending. so with that, prices are going to probably continue higher, and with oil going up, I think we, again,$100 per barrel on WTI, all of this that's going on right now, I don't think there's anything that really, if you look back on what's gone on over the last 15 years or so, that you would say, well, that makes no sense. Everything makes sense. the amount of spending, the lack of taxes to pay for that spending, all of this is going into a giant bucket and causing a major problem for the fiscal responsibility side of the House. And therefore, what that does is it creates lack of conviction for people desirous of buying our bonds.
5:49And when you have that lack of conviction, lack of confidence, it causes people to bid down those instruments. And that's when yields go up. 5 % on the 10-year is pretty unbelievable. Have you seen the housing companies? Have you seen Lenars and DH Horton? And have you seen all these companies that are involved in the housing market right now? Their stocks have been obliterated.
6:18And that's going to continue to happen with housing prices as rates stay high. And unless we see one of a couple things, inflation subdue, the economy slow down precipitously, or maybe a change in the spending habits of our current administration, we're going to continue to see rates on the highs. but today I want to really focus on something before we get to our guest as I had mentioned who's coming up it's David Gaffin I want to focus on something that I think you really need to hear about or maybe you need to understand that's probably a better way to look at this and that is a question do you really know your funds do you really know your funds Because I think one of the biggest mistakes investors make is assuming that they know what they have simply because they recognize a name on a label.
7:31The mutual fund and the ETF industry has done an absolutely brilliant job of creating these neat little categories for everything. We have large cap and small cap. We have value, emerging markets, dividend income. Some of those may be a little bit reasonable to assume you understand what you have inside of your fund. But the problem is that those labels don't always tell the story. In fact, this is something that I've really focused on. We really stay strict to a methodology here at Horowitz & Company when we're looking at building a portfolio and we want to understand what's inside of that portfolio because we want to have a specific sector covered in our allocation.
8:27But that doesn't always happen when you're just building a portfolio haphazardly because sometimes the funds can be signaling that they are a particular investment in a specific sector. And two funds could actually appear identical but produce dramatically. I mean, incredibly different results because they're not actually investing at all in the same thing. In fact, they're totally different. And one of the things that I looked at just recently and I said, well, that was a head scratcher. What's going on there was two emerging market funds. These are ETFs. One of the symbols is EEM and the other is S-P-E-M.
9:15EEM, Emerging Markets, and S &P, the S &P Emerging Markets, right? Both are considered Emerging Markets ETFs. And basically, you would think, well, let's look at these. Which one would be better to buy? And let's find out because they're both supposedly ETFs that are investing in Emerging Markets. But in fact, they're entirely different. Maybe you would look at them and say, well, I'll just pick the one that has the lower fee structure. Because after all, again, they're both emerging market ETFs. So what could possibly be the difference? We have the same category, the same objective. Seems like they're generally both investing in the same part of the world.
10:04But in fact, under the hood, they're surprisingly different. When you look at EEM, for example, that one, it follows the MSCI, that's the Mortgage Family Capital International, that's what that stands for, Emerging Markets Index. However, SPEM follows the S &P Emerging Markets BMI Index. Wait, that's right. There's multiple indices out there. And when there's multiple indices, you have to realize that if one is following this one and one is following other, what are the differentials? Because on the surface, it may appear to be insignificant. It may be a little technical detail. But that single decision changes what qualifies entirely as an emerging market.
11:03because here's the rub. This is really kind of fascinating. When you look at the MSCI index, they include South Korea as an emerging market. However, S &P says that South Korea is actually a developed market. Okay, so what's the difference between South Korea being in and South Korea being out of an index? Well, if EEM, that classification, has a meaningful positioning in South Korean companies because they have the South Korean exposure. And we know things like Samsung Electronics, SK Hynix are ripping it up this year. And Korea, South Korea, has been an explosive market to be invested in. While generally SPEM, the S &P Emerging Markets Index, does not.
11:59We're talking about an enormous differential in performance. I mean, think about that for a minute. Two funds can advertise themselves as emerging markets investments, yet one owns Korea and the other one doesn't. That could be an enormous distinction in times like we are now. Maybe sometimes it doesn't matter as much, But when you're building a portfolio based on the idea that you are including emerging markets, this creates an entirely different investment thesis. It may be what you want, but it's just different. And it could also explain pretty easily why there's a performance divergence in your portfolios compared to what you thought it is.
12:49So EEM has, when I say substantially, you can look this up. Go look this up because I think you'll be pretty surprised. EEM has blown past SPEM. And again, that's the technology heavy Korean index, which has a lot of the semiconductor stocks in there. So if an investor only looked at the fund name, they've concluded, well, both funds are an emerging market. That's fine. But they really didn't. Because in that case, the index determined the outcome. The label on a lot of these is simply marketing. But the index methodology inside of a passively invested investment, like an ETF, specifically the ones we're talking about here, that's what actually drives performance.
13:37Now, this phenomenon, I don't think what we've seen over the years, I've done a lot of studying of this. It's not specific to just and limited, really, to emerging markets. It's actually all over the investment landscape.
13:55And what we found is many investors really don't pay a lot of attention to this. They just look at the name and think, well, I'll just buy that. That describes what the manager's doing. That's fine with me. I'll go along with it. But sometimes the name is actually less descriptive of what happens inside the fund. And sometimes it's completely useless. You know, there's funds like, you know these. Take the Fidelity Contra Fund as a good example. One of the, clearly one of the largest and most successful mutual funds in existence. But have you ever thought of like, what is that? What does a Contra Fund really do?
14:41Is it a value? Is it growth? Is it large? Is it small? I mean, there's so many questions to ask. Is it contra? All right, contra. Let's go with that for a second. It's contra. It's contradictive. It's contraintuitive. It's what is it? So that name actually tells you nothing about what the fund actually does. The reality, contra fund has historically been a large cap growth oriented investment that the portfolio manager has a flexible, what they call flexible mandate. But you're not going to know that by just reading Contra Fund. And this is the same thing when you look at other types of either ETFs or actively managed mutual funds.
15:28You'll see things like Opportunity Fund or Strategic Fund. You'll see Select Funds. I'm trying to think of some other ones.
15:44There's dozens of other ones probably out there. But what happens is the name, it may sound impressive, and it's very marketable, right? That's the thing. I remember back in the day there was a GT Investments, and they had all sorts of interesting and very marketable names for their underlying funds. It was like, oh, that sounds good. You know, the GT, or whatever it was called back then, I'm making this up, but the GT Global, you know, fast-track growth fund or the technology enhanced. Again, these labels, they may tell you some of the things that are going on, but may not. And then you have to wonder, how does this actually sit in my portfolio?
16:28Is it giving me the diversification that I need? Is it giving me the growth factor that I need from a growth fund? Is it a growth fund? And I think what really matters the most here is that when you build a portfolio based on assumptions that you think is diversified and you think you have this exposure to various parts of the world or a specific sector that's concentrated and you want to use that for maybe a diversifier inside your portfolio or you're using this for maybe a buffer. you have to look under the hood and discover exactly what's going on because not only do we have the potential for this being something that is not exactly what you thought it was, but maybe the underlying investment process is not what you think it is either.
17:19And we have something we call style drift. Style drift where the actual way in which the investment is actually performing is not what we anticipated it would be from the perspective of a sector that we have identified that to be. And what we've learned over the years is that successful investing, there's a lot of things involved. There's so much involved about it. But when you're building a portfolio based on indices, sectors, diversification, specific allocation, mean variance, optimization, you need to understand what's going on more than just the ticker symbol and the name. What countries do you own?
18:05What sectors? There's things like factors these days. Which benchmarks or indices are they following? What's the index methodology and all this? because the idea that you're just going to follow along on a fund name, that's amateurish. That's kindergarten-style investing. The holdings are the investment. And if there's one lesson that I think we should take away from this entire discussion is don't buy the label. Buy the exposure inside the fund. know exactly what you're paying for and exactly what you own. Because sometimes two funds could look identical on the outside and have entirely different investments on the inside.
18:55And you're left a scratch in your head for a while saying, how come the portfolio hasn't performed the way I thought it would? Something to think about. We're going to get to our guest right now, David Gaffin coming right up. Before we get to our guests, let's talk about interactive brokers. You can trade your portfolio with the power of prediction market probabilities. That's right. With interactive brokers, trade prediction markets on election, climate, and economic outcomes right alongside stocks, options, and bonds. Prediction market prices reflect probability. And correct predictions receive$1 per contract plus earn interest on your position.
19:38Prediction contracts are not suitable for all investors. Visit ibkr.com slash predictions. And our guest today is David Gaffin, and he is the U.S. breaking news company's editor at Reuters, where he's worked for almost two decades. He also did stints as the U.S. energy editor and U.S. deputy markets editor and has been a business journalist for more than 20 years. In that time, he's covered the 2008 financial crisis, the oil market meltdown in 2020, and was named for a Lieb Award for a series of articles on the growth of stock buybacks in 2015. Let's get on with Dave. So, David Gaffin, how are you?
20:23It's been a while. It's been a while. Doing well. It's been a busy summer, as always, but it seems to always be busy these days. Yeah. But, you know, a lot going on, as you can imagine, or as you well know, the markets are not dull. You know, the world is not dull. You know, it keeps us on our toes. Yeah. You know, it's funny. It's like, you know, if you want a job in this world that is never going to go away, the number one job is an orthopedic surgeon because people don't stop doing dumb things and getting hurt. The second thing is being in your position because there's no shortage of news ever.
21:00Ever. Yes, exactly. Yeah. And there's always triage one way or another, which is, I guess, similar to orthopedic surgeons. Yeah, exactly. So I want to talk to you about that. I want to start our discussion with the discussion about financial journalism and how, you know, things have changed. So, listen, you've been covering markets for years and you've watched the information landscape completely, at least in my opinion, completely transform over that time. So I guess from where you're sitting, how has the job of financial journalists changed over the last, let's say, 15 or 20 years? You know, it's funny because you feel like you're just constantly on a hamster wheel trying to keep up with whatever is new in the next latest development.
21:48From a news perspective, I think the heavy hand of different governments in both the markets and in business in general is a very new and not always welcome development. There's this sort of feeling that this invisible hand that guided everything, that that's not really the thing that people think about anymore. They think much more about government involvement, taking stakes in companies, directing investment one way or another. And I suppose it was inevitable after a long period of just let the market do what it wants that things would swing this way. But I know that it's a definite challenge and it causes CEOs to change their communications and how they interact with people, be it chief executives of other companies or just of nations in general.
22:36So that's probably more from the coverage perspective on what we're seeing out there. From our end, it always feels like there's this ongoing growth of media properties and, you know, for good or ill, that are very much, you know, designed to cater to a specific niche audience and kind of tell that audience what they want to hear. And I would argue probably that that's more in the political realm, as you would expect, and it's a little bit less in the business realm because, you know, business is, you know, always focused on just is this going to make me money? And that does not change. But, you know, there are people who are, you know, want to kind of cater to those elements and want to hear from just their special, you know, sort of outreach as to, you know, what's good and great rather than necessarily, you know, the more general approach.
23:28media just is getting more fragmented by the year. And it's leaving very few properties that people really broadly trust. I hope and think that we're one of them. But it's definitely a very, very different kind of thing from 20 years ago when the business press was, of course, still very well established, but just the same. You had a few big behemoths and those were it. And then you had a lot of little blogs and now it's all over the place. It kind of runs the gamut. So, you know, you talk about properties and Reuters used to compete with newspapers and television and a handful of wire services, right?
24:07That were out there, AP, et cetera. Today, you're competing with X, formerly known as Twitter, YouTube, podcasts, sub stacks, blogs, which is kind of sub stack is a new blog. Right. And and and and something else, which I find. interesting because, you know, we have Google alerts on our names, our names of our show. And lately we've been getting hit with all these unbelievable summaries of our podcasts that clearly were AI generated and automated. Yeah. So this is something that's gone on. Have you seen and clearly let's leave the AI generated point just for a moment aside and bring that back because I know that's going to be something.
24:49But the other things, right, Has that changed the newsroom and how you have to either, one, be the first two, right, really trying to get that scoop right, trying to get it fast, two, your time to, I guess the problem is going to be now there's a lot more, I don't want to say fake news. That's not really what I'm trying to say here. But, you know, the authentication of the news is a lot different than it was before, right, where you have to get. I remember a time when you had to have at least two names on the item, right? Now it's a name that does not want to be disclosed, which is just fine with everybody as long as you say that.
25:31So, again, going back, all these YouTube podcasts, all this, you know, ex-social medias, fact that the president, you pay$100 ,000 a month to get early information, how has that changed the newsroom? I mean, it definitely puts a premium on just reporting on what you would call like the second order or like the derivative effects of things happening. And you don't want to spread rumors. I mean, that was always the thing is like, are we just spreading a rumor? And how do we report on something that is a rumor when the reality is that if a share price or if an entire market is being seesawed as a result of something that somebody has reported out as a rumor?
26:15Well, then you do have to react to it somehow. And then this element of, you know, Wall Street trying to monetize and take advantage of, you know, a platform that will, you know, shovel the president's words to them faster than anybody else introduces an entire new level of, you know, questions about disclosure and, you know, what and who has what first, which was always the thing that people were trying to avoid when it came to the likes of, you know, company disclosure and things like that, that you could, you know, you would have to put things out there in a public way that everyone would see it.
26:50And the old way, of course, was, you know, business wire and public PR newswire, which were just press releases, obviously. And now that's changed to where, you know, disclosure can be fair through, I think, the likes of social media, but just the same, you know, what platform are they going to be on? Can everybody see it? I mean, it does change things, you know, dramatically, and you have to respond to, you know, the fastest stuff that's out there. And that, you know, is, you know, of great challenge, especially because, you know, our standards require that we have things verified and that we don't simply just say, you know, that the thing has happened and the chips fall where they may.
27:25Yeah. So there's more pressure today. There's more, is there, I guess the question then, is there more pressure today to be first or to be right? I mean, we always say, you know, we'd rather be right than first. I mean, that's always the thing that we have to do, you know, and, and that, you know, it, that doesn't mean that it doesn't tax us. It does at times, but we try to say, we have to have a handbrake here and we have to hold on and say just what is happening. And is this something that we need to react to? And look, if something that, you know, the president or anybody else says causes a particular stock or a particular market to move by substantial amounts, well, then we have to point that out, but then we have to contextualize it as much as possible and as quickly as possible, which is not easy because, you know, already, you know, the market is off and running.
28:16And so it puts us in that difficult position of having to report on something that is coming from a place that may not be, you know, something that can be verified. And that's always going to be the challenge. And it's only getting more challenging, I think. So let's go back in this looping this last point about journalism today about AI, because AI clearly plays, I could tell you something, it is my, you know, my grammar and my spell check, right? You know, you have to be careful. I'm like, you know, I put a paragraph in, I said, do me a favor, check this. And it comes back with an entirely different discussion, right?
28:49And I'm like, no, that's not what I wanted. I just want you to check grammatical issues, sentence structure, order of that. And maybe if there's, if you could maybe give me a word or two that would better explain this to make it a better flow, for example. But AI, pretty amazing. I don't think you'll disagree with that. And very handy when it comes to content. So where are journalists, where are you on the spectrum of hate it, love it, use it, no way? Yeah, you know, over here we have embraced it, you know, to a reasonable extent. It is not, you know, governing our lives, that kind of thing. Obviously, you know, the areas that you've already mentioned, grammar and spellcheck, certainly that comes into play, and that's more rudimentary.
29:38you can go to the point of where it puts together things like bulleted summaries of stories, because we do put bullet points on the top of stories. The same thing with generating headlines, generating short news stories, using it to vet claims that are in a story where you would send it through and allow it to do a spot check so that it comes back with questions about whether something may be factually accurate or not. And those, again, you have to have the handbrake on every single thing on some of it. It can be very, very good. We have built some tools that allow people to do things like crunch numbers in a way that are a lot faster than tapping through an Excel spreadsheet for hours on end or, you know, searching out documents or that kind of thing, the kind of thing where you're actually trying to actively cut down on labor rather than say, you know, through the idea of having it right for you or something like that.
Read the full transcript
30:34Because often, And, you know, when I've tried or I've experimented with the writing elements of it, I find it a little bit stilted. I find that it's kind of missing something. It is, you know, somewhat, you know, it is not necessarily inaccurate, although that happens at times. But it's more if you and I'm going back to date myself, the movie The Fly in 1986. Oh, Jeff Goldblum's character cooks two steaks. Brindlefly was his name. Brindlefly, yes. And he he cooks a pair of steaks for the Geena Davis character and sends one through his machine. And she judges the first one, just a regular steak to be fine.
31:11But the one that he sends through his machine, she spits it out and says it tastes synthetic. There's a certain way in which some of the things that it writes may not be inaccurate, but it comes across as synthetic to me. And it's sort of something that I can kind of pick out. And and that's more an alchemy that comes from being in journalism for a very, very long time. When it comes to, say, putting together bulleted point summaries, those tend to be relatively straightforward. It can pick out errors, that kind of thing. It can help distill documents. I have had success with that. I can give you an example.
31:45During this entire Iran war that's been going on, we've seen – Conflict, sir. It's a conflict. It's not a war. Please. It's a conflict. Well, then, there has been a you've seen the inventories of various fuel related products decline. And one thing we noticed is that a number of months ago that California's gasoline inventories were near five year lows based on a chart that's on their state's energy regulator website. Now, they have an Excel spreadsheet of all of their data going back about 23 or 24 years. And I wanted to find out if this was the lowest ever. The problem, of course, is that California gasoline inventories refers actually to three things.
32:26It's blended gasoline because California blends its gasoline so that you don't have the smog in the air. The components it uses to blend that gasoline and then the raw gasoline. Those three things are its broader inventories. And before this year, it used to divide it up between North California and Southern California. So now you have six lines in one Excel spreadsheet to create one line. I was able to upload it into, you know, one of our AI related tools and it crunched the numbers very, very quickly in a way that I could have done but would have been scrolling through Excel, hitting return, scroll, return, scroll, return.
33:04Yeah. That proved to be very useful. And using some spot checks, because I did check the numbers to make sure it was correct. I did verify that this was correct. And it took what would have been an hour and a half to two hours of labor and turned it into, you know, five minutes of labor. That struck me as a very good and useful use of AI. The story was still written by a reporter of mine, but, you know, just the same. That was a valuable effect. And we are finding valuable effects from, you know, the ability of AI to, you know, sift through databases, to crunch numbers, to find things like that.
33:40But it will not always do what we want. It often, perhaps your hunches are still something that are intuitive and better. It cannot call sources up on the phone. It cannot track down people. It cannot pound the pavement. But it can sort of help kind of flesh out ideas and thoughts kind of in your head in a little bit of a dialogue, as long as you understand that it is working with the limitations of previously published material. And we have notable prompts that say, please only use verified news sources like Reuters and some of our competitors and that kind of thing. So those things, and if it sifts through that or official government data or government statistics, has had valuable uses.
34:27And so I'm not going to be some sort of ambassador for AI here, but I'm not going to be a Luddite and an obvious detractor. And so, you know, it has much that it can do that will streamline some things. And then there are its pitfalls as well, which I'm sure that you've, you know, noticed as well. So that is a bit of an overview. There's some great things that it can do. And don't forget, it stole most of this data from us anyway, right? Yes. It stole all this. This is not like new stuff that's being generated. It's just being taken apart. Well, it's kind of like Brindlefly. It's being taken apart and then put back together on the other side is exactly what's happening.
35:07And by the way, I can't now get the images of his fingernails falling off and his fingerprints all coming off right now during one of the scenes as he was morphing into the fly that he will become at the end. Yes, exactly. What a great movie. That's what I'm here for. Metamorphosis and what kind of – it is a metamorphosis book put into a movie. So let's talk about polling though for a second. We have midterms coming up and polling is a big issue. There has been this idea that polling, well, that the whole election process, let's start with this, that the whole election process is a problem. That's the first of all.
35:46I think that's the first issue that from the start to the finish of what people say, what they do, what they do is not what they say. And then in the end, if the parties that are talking, the people that are talking, that are on the wrong side of the actual eventual election are just going to say that something bad happened, it was rigged and all that. Is there any value in the polling these days for you? You know, it's a tough call from what we have on our elections team. You know, the polls make you give you a sense of broader trends. You know, the question is, is, you know, how willing people are to answer polls these days.
36:28And as people become less and less willing, you risk in polling to over indexing to people more willing to pick up a phone or more willing to do answer these things online. And whether that skews you towards a populace that tends to be more urban and more educated and overstating then some of the opposition that exists to the president at this particular time. That's not to say that he's popular. Our polls continuously find that he is not, and most others would seem to agree. The question is whether his approval rating really is around where we have it, which at Reuters Ipsos was the most recent, I think 34 % or so, which is not a very high number.
37:12And then there are others who have come up with the range of 40 percent or so, which isn't what you would call good, but it is certainly something that suggests a potentially different outcome in the midterm elections or at least a less dire one for the Republican Party, which is currently in power than a polling result of a popularity level of 33 percent, which is much more dire, as you would imagine. And I do agree with you as far as people, the discourse now is a lot around this was rigged and that was rigged. And my fear of that, of course, goes to the point where if after a time you have for years people determining or saying predetermining that something is rigged, at what point do people in power decide to take steps to actually do things that are on the level of actual rigging?
38:03And you run the risk of going from a place where, you know, associate, you know, excuse me, assorted cranks would say things to it being the broader, you know, feeling amongst people. And then you lose trust and then you open yourself up to a lot of very bad outcomes that we have seen throughout history. Listen, the bottom line of all this is that all of our, I think our political system, our economic system, our financial system, and you go on down the list is all based. I've said this a thousand times. It's all based on confidence. You know, the full faith and trust in something, nothing is backed anymore.
38:39It's all backed by the theoretical confidence factor. And you lose that in any linchpin area of the bigger picture, right? The economy, the politics. If you lose that in a place totally, then the whole thing starts imploding upon itself. The weight of the confidence factor becomes so one huge or maybe one or two sides of the house pulled out, it is not going to stand any longer. That's a big problem. That's my two cents on it. That is a big problem. I mean, the more one of the, well, somewhat recent examples, of course, would have been the financial crisis when, you know, banks no longer became confident that they were going to get their money back, that they were lending overnight.
39:27Right. You know, which was the absolute then collapse of, you know, the overnight lending system. And then, you know, everything that ensued from there, you know, and you're right. I mean, and the financial system in some ways is always based on confidence, but there are a lot of other things that are based on certain levels of confidence and trust that have to be considered. Yeah. Let's talk about market valuations for a second. That's another thing that we trust and that we like to look at. And you are, you know, a lot of stories, right? By the way, if you don't know this, I'm a big Reuters fan.
39:56Thank you. That is my, on my, I can show you my apps on my phone. It's right there. That's the first thing. Seriously, right? I'll show you right here.
40:04David Gaffen:Maybe if I could open up my phone. So right here in my financial section, the first thing is, there's Reuters. Excellent. I don't know if you can see that right there. Yeah, I can see it. But that's the first place that I go to. And then I try to fill in around and see what else is going on. But basically, that's the first place, you know, along the top, along the side, along looking at whether it's market-based, whether it's a world-based, whether it's, you know, health-based, whatever it is, whatever I'm looking at. But clearly, the number one place I go to. Because, by the way, this is not a plug for you guys.
40:38You're not paying me and everything. But I'm just going to tell you, it seems to be one of, there's probably two or three others I can mention, but one of the least affected by outside influence and trying to get to the news. That's as I see it. Appreciate it. Thank you. We work on that. We work hard on that. So anyway, we're talking about valuations. We're talking about market valuations. We're talking about pricing. You talk to a lot of people. Well, I guess the question with this very hot topic on Wall Street that's being asked is, are markets expensive? Or is it like, well, no, because look at the forward earnings on what's happening.
41:17So is the expectations, what you're hearing to what's actually happening, is there a lineup or is there a major chasm between the two? You know, it's a hard thing to say right now because there are a lot of things that would say to you that there are real things to be concerned about. And the price of diesel at$6 a gallon and oil at$107 right now it is on the international Brent benchmark. With bond yields where they are, with mortgage rates going up, once again, you have to look at those things that are directly – that affect the earnings and the costs for companies and the borrowing ability for both, again, companies and for individuals and say to yourself, well, does the market really belong at this level, which is just a shade or two below an all time record.
42:11And yet then at the same time, consumer spending seems to continue to kind of roll along. And that may be the result of the fact that about half of US consumer spending now all comes from the top 10 % of earners who are a little bit more buffeted from the likes of higher energy costs than some other people are. And, you know, you do see a substantial spend right now that is going on throughout the technology industry that is part of this AI build out. Substantial, may I interrupt? Substantial is a kind where it is epic. It is historic. It is never going to be matched at this level before this, at this compressed time period, right?
42:48You know, it's like all of a sudden everybody said, okay, this is what we were waiting for. We had this money sitting on the balance sheet for all this time. We didn't know what to do with it. We were buying companies here and there. We were paying dividends. We were buying back our stocks. This is what we were waiting for. And it's like we're going. Not only are they doing that, but they're issuing massive amounts of debt on top of all that. And it's pretty much an upside down market from what it used to have, which was a cash cow, a la Apple, a la Google, and then name the rest, Microsoft, et cetera, with a good amount of shareholder benefits, dividends, buybacks, et cetera, and clean balance sheets to let's go.
43:32Yeah. You know? That's for sure. It's pretty amazing what that's happened. And that, to me, is good and bad, right? It's good because if, in fact, this whole thing plays out, they need to do so. They need to spend this kind of money. Well, I don't think they need to spend this kind of money. This is absurd about some money, but OK, let's go with it. You know, but at the same time, when this deflates a bit, when all of a sudden we have the infrastructure built and there's no longer any further money going in from the massive hoard of cash that they had, what's going to fill that in? That's a question I have.
44:14Yeah, that's a really good question. And I think that's the question that's kind of remained on everybody's mind during the entirety of this build out is kind of the, are they giving us a return on investment that we expect? Is the spend turning into something that's just not just a spend, but something that realizes actual returns, that realizes revenues to these companies in particular? There are, of course, those who look at the likes of the NVIDIAs of the world and sort of see them as the, you know, the pickaxes and shovels of this entire thing, which may be they very well may be. Obviously, their valuation has gone into the stratosphere, as has some of the other gigantic hyperscalers, as you would put it.
44:54And so certainly, you know, there are a lot of people that look at this and they say structures whereupon, yes, they're taking on a lot of debt, but they don't believe it has reached a level that is as concerning just yet. And the market just sort of rolls along as it were because of this heavy, heavy directed tech and business spending. And then, you know, the reasonable performance from the consumer. And then that's just all enough, even though, as said, you do have some real concerns that people have with the rise in interest rates. Borrowing costs cannot just be sort of waved away. And the impairment that we see in the energy markets that also now looks somewhat, well, not permanent, obviously, but it's definitely more than just, you know, ending tomorrow.
45:42You know, it's not no longer a tentative kind of, you know, this will be over soon sort of thing. The market is rethinking that now. Yeah, we have, you know, this is adding to the inflationary story. There's a lot of money being pushed in. There's a lot of building going on. It's creating residential housing is a big problem. We see interest rates hitting above the, right at the 5.5 % level on the 10-year. The 30-year and mortgages are the highest they've been since forever, or a long time, not ever, but a long, long, many, many, many, many, many years. Not reaching the levels we saw in the 1980s, but still constraining us because housing prices are so much higher.
46:21That's causing a drawdown. If you haven't looked at some of these companies in the building area, it's kind of a little bit shocking where they've been and where they are now. Inflation has come down a bit, but yet not as much as we would have thought. We saw a PPI print of 5.4 % year of a year. That was high. This week? That recent one. Yeah. The idea that inflation has been defeated, I don't see it. It's still there. And it's not because of any particular regime. But how much of this particular inflation story right now is linked to, I guess, two things, right? It's really – isn't it really just energy and food are the two major plays in this right now?
47:09They seem to be the two major plays in addition to what you've already said about housing. And then I have not looked lately, but I don't get the sense that medical costs are declining in any kind of real way either. You know, those are the ones those and education seem to be kind of sitting out there as kind of the big ones. You know, certainly, though, the day to day on food prices, some of which had come down, but then there are still, you know, high prices for things like cattle and other other related agricultural commodities definitely are sitting out there. The energy costs continue to rise and are ending up somewhat embedded in U.S.
47:47costs right now, specifically around the likes of travel, the cost of things like harvesting and planting because of the fact that diesel prices are as high as they are. And they are at a record and right near about$6 a gallon, which is the most ever. And that is a real pinch in terms of cost. Right. We are not as energy. I don't. What's the term? I think energy intense in terms of the economy and that people don't spend as much on their budget on energy as they used to. I mean, you know, that 1970s energy shock was such a thing because people spent more on gasoline as a percentage of what they could spend.
48:25That's not the case as much anymore, but just the same. There is a pain threshold and we are well above four dollars a gallon on retail gasoline. That's not nothing. And a lot of people commute and they commute long, you know, long routes to get to work. And people will be forced back to work. And we also have the most expensive gasoline prices in history on Labor Day. Yes, that is correct. And we have cars like the F-350 that have 60 gallon tanks. And that means that if you're going to fill up to quick calculation,$6 diesel, throw that into an F-350. That's$360. That's what it costs to fill up a little bit.
49:01Well, my boat's a bit more expensive, but nonetheless, it's like filling up a boat. And the only thing you could do with that, there is something, you know, it's funny. What can you do with that? You can plead with your place of work and say, you know, listen, it's out of control, this cost. And instead of that, can we just do a remote, can I work remote? They may say yes. That is a possibility. you know but I guess this this energy thing what's really troubling me is that I look and I hear the commentary about the Straits of Hormuz or not they say they're open but they say they're under our control by the way if I can make a quick announcement and plead with the people in charge if in fact the Straits of Hormuz are under our control can you let boats go through them because they're not all you have to do and you've done this I'm sure is look at the AIS tracker I've told people about this before, but do it.
49:53You just have to do this. Go look at, look up in Google, look up AIS tracker, uh, straight of Hormuz. And you'll see what's happening there is there is boats, a lot of boats over here. There's a lot of boats over here, but over here, there's no boats going through. Not so much. Not so much boats going through. And, um, that the problem is, and we talked about this at length on the last show, and I have a lot of detail in this, But the salt caverns in Texas and in Louisiana are starting to show a real problem with the low inventories that we have right now. Yes. And that may be something that does create – well, I'll ask you.
50:32Are we in for an energy shock? You know, we're still sort of sitting around waiting for it in a lot of ways. I mean certainly, as I've said, the costs have gone up to the point that it's a real pain point for a lot of people. Hormuz is not open. and one of the things I've been saying within the length of this whole thing, because it takes time to refill inventories, both government and commercial inventories, and this has been a drawdown that's going for months now. The thing I say is that every day the Strait of Hormuz is closed is a day the Strait of Hormuz is closed, and we are roughly 10 million barrels below the normal of what used to go through there, and now the Saudis have rerouted a bit to the other side, which is now being threatened as well.
51:17There's been some demand destruction. The Chinese are notably using less. And there's been a bit more production than expected out of the America's hemisphere. Those things have offset things a little bit. But just the same, the market, I think, for a long time had this kind of ongoing assumption of this is the worst it's going to be and in a few months it's going to be better. That was kind of JP Morgan's recent take on it. And the market at this moment is rethinking that. And you see where futures prices are going, because they see the tightness that has existed in some of the products markets.
51:50And, you know, you've had these refineries shut down or attacked in, you know, Russia and Ukraine, which is refining supply and, of course, in the Middle East. And that has caused, you know, some of the reason that we see high diesel prices and high jet fuel and high gasoline prices. We want to refill the petroleum reserve, but that takes time too. That requires we have enough to use. And I think, by the way, one of the things that's happening right now is the amount of reserves that we've used for things like refining and shipping over to Europe, which was pretty much out of fuel about two months ago.
52:31And all the things are being used to suppress it so it looks better. I don't know. It looks to me like there's a lot of shenanigans going on, which is not unusual for our government. but shenanigans going on to try to cover up a giant pile of crap with some, some, some fine chocolate. Let me ask you this in closing. Sure. What, what do you think is one of the most, over the next six months, what is, what is your team? What are you focusing on? What is, you know, I know you focus on the here and now and what's happening right now. That's important of course, But I know this somewhere on a whiteboard or something or in a Slack conversation internally.
53:14It's like, you know, these are the priorities we need to be watching for. What are those? You know, there's always quite a few things that are being bounced around in terms of ideas in the newsroom. Obviously, you know, AI remains of great importance. And, you know, the big societal changes that are being brought through, not just, you know, the use of it as a technology, but, you know, as a use, you know, and a, excuse me, a user of the likes of water, of power, of land, of resources as well. And, you know, the way in which, you know, that technology is kind of shaping, you know, the landscape politically and the landscape, you know, societally as well.
53:53You know, people may not necessarily be opposed to it. And, you know, certainly they're trying to hope that their kids don't use just to cheat on tests. But, you know, there are questions of, you know, where is all of this being situated? What is the, you know, the resources that is using that is sucking up? And is that, you know, disadvantaging some people? And do you feel like that's, you know, advantaging only a very small group of people that that remains of paramount importance? And then the ongoing political dynamics with the sort of slow emergence of China as a more recognized world and economic power and how the United States deals with that too.
54:38I mean, the United States has a lot of advantages still as an economy and as a structure and as a republic. And certainly with a lot of the businesses that are located here, you know, the number of largest companies in question. But there's that whole AI race that we see that is becoming, you know, paramount because of what China is doing to try to, you know, take advantage and to try to gather a leading position there. You know, those things remain, you know, that at the top of the list, along with other technologies that are, you know, remain, of course, of great importance, be it electronic, you know, electric vehicles, self-driving, you know, the proliferation of weight loss drugs.
55:20And now I'm getting into a little bit of a laundry list, so I won't do that. But those are some of the things on our minds. So just to restate, there's no shortage of stuff that's going to be happening. Absolutely not. We didn't reach the end of the news, did we? No, no, no. There's no webpage that says the news is finished. Please go outside. Thank you. We are closed. We are closed. Yeah, exactly. Great stuff. David Gaffin, Reuters. Appreciate you coming on as always, man. It's good to be here again, Andrew. It's always good to talk to you. All right, thanks. That was pretty good. I like that.
55:51Good discussion with my good friend, David Gaffin. That's going to wrap it up for this edition of the Disciplined Investor Podcast. Make sure to listen to DH Unplugged each Tuesday. we put that out. We're live actually at 9 p.m. on Tuesday nights. I stay in the office late in the studio that night. Also, if you have any questions towards the end of the year, you want to discuss, for example, how do I figure out if my mutual funds, if my ETFs, if my portfolio has overlap and it actually is doing what it should be doing? Well, you can contact us. Go over to thedisciplinedinvestor.com. That's a good way to do it.
56:30Plenty of ways to contact us over there as well. You can also check out our long, short strategy. I sometimes bring this up and really mention this because right now with some of the things that are going on with the market, the TDI managed growth strategy, you could see a video on the website. There's a full walkthrough behind the scenes. Look at the TDI MG managed growth strategy, the disciplined investor managed growth strategy over on the disciplinedinvestor.com. Go there, click on the strategies button on the top navigation bar, and then you'll be able to go through and answer a couple of questions.
57:03It will then direct you over to the virtual tour where you can see about a four or five minute video on this. Make sure to take a look at that. Other than that, I'll see you next week. Have a good one. This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz and Company, Inc., an investment advisor registered with the U.S.
57:38Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements. Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement. Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions.
58:12Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliate support.
From the publisher
Total PPI was up 5.4% year-over-year, up from 4.8% in July.
Yes, we have inflation.
Oil rocking higher – WTI breaks above $100+
Asking: Do you really know your funds?
Our guest this week – David Gaffen, Breaking News editor at Reuters.
NEW! DOWNLOAD THIS EPISODE’S AI GENERATED SHOW NOTES (Guest Segment)
David Gaffen is the U.S. breaking news companies editor at Reuters, where he has worked for almost two decades. He also did stints as the U.S. energy editor and U.S. deputy markets editor and has been a business journalist for more than 20 years.
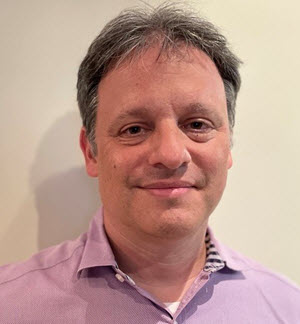
In that time he has covered the 2008 financial crisis, the oil-market meltdown in 2020, and was nominated for a Loeb Award for a series of articles on the growth of stock buybacks in 2015. He lives in New York with his family.
Check this out and find out more at: http://www.interactivebrokers.com/
Looking to invest in The Disciplined Investor Managed Growth Strategy?
Click HERE for the virtual tour – https://tinyurl.com/tdimg1
Stocks Mentioned in the Episode: (EEM), (SPEM), (LEN), (DHI), (SKHY)