
In short
Crowded AI/semiconductor positioning and leverage risks; how markets can ignore fundamentals until “everyone exits the boat” at once. Discussion also touches on sentiment/positioning indicators (DeMark exhaustion, market internals), credit-spread widening, and rotation away from mega-cap leadership. Guest also highlights selective opportunities in energy, consumer brands with easier earnings comps, and China internet/AI exposure.
Guest backgrounds
Thomas Thornton is founder of Hedge Fund Telemetry. Former portfolio manager, senior trader, and technical analyst at Level Global Investors and Galileo Capital. Writes a long-running daily market note for hedge fund managers; focuses on sentiment indicators and technical exhaustion signals. Passion: Formula One racing.
Key claims
Great themes (AI) can still be dangerous when expectations and leverage become concentrated. South Korea’s AI/semiconductor leverage led to mass margin calls and forced liquidations; similar “crowded boat” dynamics can hit elsewhere. DeMark/market breadth suggest no broad oversold condition yet, but downside exhaustion could appear if weakness continues.
Notable examples
Dell’s late-1990s “indefinite growth” expectations; South Korea margin-call wave (about 1.2M leveraged accounts; ~300–350k liquidations); Situational Awareness Fund meltdown (~$35B lost); Archegos (2021). Levered ETF collapse (e.g., 3X SK Hynix/KKuru down ~69% from highs; reverse splits). Suggested trades: energy majors (Exxon/Chevron), Nike/Lululemon/Starbucks-style turnaround comps, and China internet (Alibaba via KWeb/FXI; claims Alibaba owns major open-source LLM stakes and has Quen AI).
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOThe Crowded Trade Phenomenon
1:56 to 4:15
Discussion on the dangers of crowded trades in the investment environment.
“I'm Andrew Horowitz, and here we are with another great week of information, a great guest coming up, and I'm really excited to talk to them.”
Historical Context of Market Speculation
4:15 to 6:26
Exploring historical market behavior and the implications of investor expectations.
“Now, to be clear, the artificial intelligence move and the things that are happening out there, it's real.”
Current Trends in AI Investments
6:26 to 8:13
Analysis of current AI infrastructure spending and investor sentiment.
“And what's caught my attention recently is a discussion about ROI, return on investment.”
Risks of Leverage in Investment
8:13 to 12:10
Examining the risks associated with leverage in speculative markets.
“is that the boat may be getting a little bit crowded.”
The Importance of a Diversified Portfolio
12:10 to 14:00
Emphasizing the need for disciplined investment strategies and risk management.
“Oh, this is not a new story either, right?”
The Art of Building a Well-Constructed Portfolio
14:00 to 17:19
Discusses the importance of discipline and diversification in investment portfolios.
“It's two different discussions entirely.”
Upcoming Topics and Guest Introduction
17:29 to 20:00
Introduces the upcoming topics and guest, highlighting discussions on taxes and strategies for 401k investments.
“And let's bring them on because I want to talk about a few things.”
Interview with Tommy Thornton: Market Insights
20:00 to 28:00
Tommy Thornton shares insights on market trends, semiconductor stocks, and the impact of crowded positioning.
“And so I held on to a fairly small 1 % marker type position in a few, SanDisk and Micron, and that didn't feel great.”
Opportunities in Crowded Trades
28:00 to 29:33
Discussion on identifying long ideas and short opportunities, based on crowded positioning in the market.
“So I think we're starting to see some opportunities to get long ideas and pick off shorts when you see it with crowded positioning.”
Lessons from the Past: The Dell Experience
29:33 to 31:33
Reflecting on past market experiences and the importance of slow entry into crowded trades.
“And that lesson has taught me that, you know what, when I go into these shorts or these crowded trades, this is me, you tell me what you think.”
Show all 20 chapters
Market Leadership and Investor Behavior
31:33 to 32:58
Analysis of changing market leadership and the shifting focus of investors post-COVID.
“I mean, they're peaking out pretty hard.”
Dependence on the Stock Market
32:58 to 34:42
Examining the risks of the U.S. economy's dependence on the stock market and implications for retirement.
“And I think there's a lot of the people that have no idea even what these companies do.”
Risks of Holding Investments During Downturns
34:42 to 37:17
Discussion on the psychological and financial challenges of holding stocks during potential market drawdowns.
“the stock market wasn't designed as a retirement account proxy.”
Market Communication and Fed Strategy
37:17 to 39:56
Critique of current Fed communication strategies and the implications for market stability.
“As much as that sounds like that will never happen, it always happens.”
Inflation and Price Pressures in the Economy
39:56 to 42:00
Analyzing the factors contributing to inflation and its impact on the economy and consumer prices.
“but I will say, I think the Fed is boxed.”
Market Indicators and Sentiment Analysis
42:00 to 46:34
Explore the current market indicators, sentiment, and pricing pressures affecting stock performance.
“PCI came out 3.3 % on a year of, PCE came out 3.3 % year over year on an annualized basis last week.”
Inflation Concerns and Economic Insights
46:34 to 50:28
Discuss the potential impact of inflation numbers and changing consumer behaviors on the economy.
“So when you hit that DeMarc low, that becomes a point where the exhaustion signal, because there are exhaustion signals.”
Investment Strategies and Stock Picks
50:28 to 56:00
Identify attractive investment opportunities and analyze major brands and sectors for potential growth.
“Or people, I feel that a lot of people have been turned off to a lot of the economic things.”
Alibaba's Growth and Opportunities
56:00 to 59:06
Explore Alibaba's diverse business model and its potential for growth in various sectors.
“And Alibaba also has their Quen model, which is their AI model, that is going to be in all the iPhones in China.”
Warnings from Market History
59:06 to 1:02:03
Understand the risks posed by market cap concentration and historical market trends.
“I'm going to say this, and it might seem pretty obvious.”
Transcript
Automatic transcript. May contain errors.0:00This episode is sponsored by Interactive Brokers. You know, world events, they unfold in real time and now you can trade them. With IBKR prediction markets, trade election, climate, and economic outcomes alongside stocks, options, and bonds, all on one integrated platform. These are simple yes or no contracts priced to reflect the market's view on probability. If your prediction is right, you'll receive$1 per contract and earn interest on your position while you're invested. IBKR prediction markets turn market expectations into actionable trades. Prediction contracts, of course, are not suitable for all investors.
0:42Learn more at IBKR.com slash predictions. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of the Disciplined Investor Podcast.
0:59Thomas Thornton:This episode of the Disciplined Investor is sponsored by Horowitz and Company. If you're looking for a portfolio manager, look no further. Horowitz and Company, from seed through harvest, cultivating financial success.
1:19Gold and silver ripping. jobs numbers telling many different stories. A good lesson from Crowder Trades. And our guest today is Thomas Thornton, founder of Hedge Fund Telemetry. All this and much more on episode number 985 of the Disciplined Investor Podcast.
1:55And welcome to the Disciplined Investor Podcast. I'm Andrew Horowitz, and here we are with another great week of information, a great guest coming up, and I'm really excited to talk to them. But before we do that, I think there's a couple of things that are going on in the markets that are really interesting. Things that are, I would say, reminiscent of times before. In fact, there's some things that are really becoming pretty interesting. And when I talk about that right now, it's about this idea that there's so many people that are involved in certain momentum trades that it can be a bit concerning.
2:30Because, you know, I put this to a bit of an analogy and talking about boats and talking about where we have a situation where we are actually on a boat. And I talk about that in relation to where we are with the investment environment. Because the most dangerous part of the crowded trade isn't when everyone is actually buying. It's when everyone decides to head for the exit at the same time. Same thing on a boat. And lately, there are these signs that investors, I think, have become a little bit too comfortable standing all on the same side of the boat. Now, over the years, we've watched this phenomenon.
3:16We've seen investors become just captivated by transformational ideas. The internet and fiber optics and EVs, cryptos. Remember the 3D printing craze? How about those SPACs? Now, each started with this legitimate idea and usually a pretty powerful theme that underlined them. And the problem wasn't the idea or the technology. The problem was that the expectations ran far ahead of reality. Analysts projected endless growth. Investors, they were all excited. What did they do? They extrapolated out returns far into the future. Stock prices moved as if success was, I mean, guaranteed, right? It was like, well, no problem.
4:07Let's just keep on pumping money. And truth be told, truth be told, that is starting to feel kind of familiar. Now, to be clear, the artificial intelligence move and the things that are happening out there, it's real. No question about that. The technology is changing the way businesses operate, changing the way we operate. And there's going to be winners. There's no question about that. But markets don't price what is happening today. They price what investors will think will happen years from now. Right? We know that the markets are an amazing discounting mechanism. The problem, again, I keep on mentioning this, is when expectations become too optimistic, even good news stops being enough.
4:54And we saw that with a variety of the earnings in the last week or so. Now, many of you have heard me talk about this idea about what happened years ago in the markets back in the year of 2000, maybe in the late 1990s. Dell computers, analysts were predicting and projecting revenue of like 30 to 40 % earnings in revenue growth year after year after year. And investors said, okay, that's great. I'll accept that. I like it. These assumptions are awesome. But if you extend those growth rates out long enough, if you think about it for a second, the outcome seems pretty ridiculous. The conclusion becomes absolutely ridiculous because each one of us would eventually need like four Dell computers on our desk.
5:44And that's probably not going to be too possible. So the idea that we have this extraordinary growth that we have that would go through the process and we think of it being indefinitely seems a bit absurd. And that's the risk with any great story. The technology may be real. The opportunity may be enormous. But when expectations get too far ahead of the reality, investors may not think about this, but the market is eventually going to probably bring us all down to earth. And what's caught my attention recently is a discussion about ROI, return on investment. The last several years, we've seen companies have been spending at just extraordinary pace to build AI infrastructure.
6:43We have the data centers, the chips, the networking equipment, power generation, cooling systems, software development. They've all fueled a spending cycle that is measured right now in not billions, but trillions of dollars. And investors accepted these expenditures because the assumption is pretty simple, right? Demand is going to continue at an extraordinary pace. And I think, I think that conversation is changing. Some companies are beginning to suggest that maybe there's excess computing out there We heard from a variety of companies like Facebook, etc. saying, you know what, we have excess computing capacity right now And we're going to make it available to others And while that may not at first seem too significant It raises an important question I think that we all need to ponder Because if a capacity is becoming available was, follow me here, was too much capacity built to begin with.
7:58And markets are beginning to ask whether this historic spending boom that powered many Aon-related stocks are moving from acceleration towards maturity. Is there any one message that the market seems to be sending right now is that the boat may be getting a little bit crowded. And again, I'm not suggesting that AI isn't important. Obviously not. In fact, let's be clear, it's transformational. No question about that. And rather, I think it's important to understand that so many investors have become, I think they have now the same conclusion that is great. And what they did is they concentrated their bets in the same places.
8:46the signs of speculation have not been limited to Wall Street. In South Korea, investors became so convinced of this AI opportunity that they went to leverage to amplify returns. They concentrated their best. They went out and they borrowed money like crazy and a handful of technology names to invest in, like Samsung and SK Hynix. And the latest reports that came in indicate that more than 1.2 million leverage accounts faced margin calls. Faced margin calls. Like somewhere between 300, 350 ,000 accounts eventually were liquidated in a matter of like a week. Because when we saw the prices turn lower, right?
9:30When the markets turned down, we saw SK Hynix move lower. We saw Samsung. We saw all the chip names really take a whack. The Korean market went from its high down about 40%. That was a big issue. And with that in mind, you have to wonder, you know, is there more or is this just going to snap back very easily? And think about that for a moment. Just for a second, I want you to think about this. Korean investors, they weren't simply buying stocks. And they weren't. What they did was they were borrowing heavily to increase their exposure to experience even more enormous gains than they already got.
10:16Again, there's been reports that 50 - and 60-year-olds were borrowing against other assets, their homes, to really ramp up their returns. And the belief was that this AI demand would continue almost indefinitely. And technically, any pullback, it's going to be temporary. Now, history tells us, we know that, right? History tells us when investors get complacent and when they begin taking these extraordinary risks because they believe the theme is unstoppable, that's a time to be cautious. then we saw another warning shot just after that with a hedge fund meltdown. This guy, Leo, Leopold Ashenbrenner, Ashbrenner, I think his name is, his firm was the Situational Awareness Fund, basically forced to unwind public stock portfolios after suffering significant losses after facing margin pressure.
11:23It's estimated that$35 billion,$35 billion went up in flames. Just poof, gone, done. The fund had become one of the, another poster child, a really high profile name in the industry. And as long as prices were rising, which we know this drill, we've seen it before. As long as the prices were rising, the leverage that was being used to increase gains was fine. But once prices moved the other way, that same leverage accelerated losses. And what did it do? It forced the asset sales. And what appeared to be, I guess, at the time, this wow, you know, this young 20-year-old with a brilliant strategy on the way to become, you know, the next big dame was another reminder that leverage cuts both ways.
12:16I mean, this is, what was it? Oh, this is not a new story either, right? Archegos Capital Management had a similar situation back in 2021.
12:33No, the AI story isn't over. I don't think so. In fact, it's far from it. What it may mean, though, is that we're entering into a phase that investors are becoming a little bit more discriminatory. They have to separate excitement from the economics, from the fundamentals. And the questions are becoming tougher. Because where are the profits? What is the actual return on spending? What's the actual ROI? How much demand really exists a la Facebook? and how much future success is going to be out there with what we're seeing already being reflected in the names today. And we've seen these patterns before.
13:21Great innovation survives a lot of these situations where we see the ups and downs, and when great innovation survives, great companies are going to survive. However, what you also know is that the excessive speculation, right, what we saw with the SPACs, what we saw with the 3D printing, what we saw with the homes back in 2008, 2007, etc., that speculation rarely does.
13:50So today as emotions rise and FOMO reaches this new fever pitch that we've been seeing, one of the most important principles I think right now for us as investors to remember is that the distinction between a compelling investment theme and a well-constructed portfolio. It's two different discussions entirely. because a theme can generate excitement and opportunity. But a portfolio, a truly well-crafted, diversified portfolio requires discipline, risk management. And really successful investing is not about chasing those popular idea on the moment. It's not. It's about this thoughtful process, right?
14:36It's about this process where you're going to balance opportunities and at the same time making sure that you don't rely on one single company or maybe even a sector for that matter or just one trend. That's probably the best way to describe it, to determine your financial outcome, your future. That's not a good idea at all. Again, I'm going to say it again. Yes, I believe. We believe in AI automation. We believe in the semiconductors that are going to be required. We believe in the infrastructure that's going to support them with the cooling agents, etc. And as a result, yeah, we're invested in many of these themes today.
15:17But at the same time, experience has taught us that these great stories and great investments are not, I mean, they are not the same thing. Markets have a way of carrying expectations to extremes. often long before the underlying economics have fully developed. We know that we see it in advance. It's like, wow, look at that move as much as it has. Why is that? And then we realize, well, look at the fundamentals are now matching. But that's why we try to remain focused, not just on the opportunity, but also on the valuation, the diversification, and the risk. Our goal as investors is not to avoid the DexPick thing.
15:57Why would that? It's dumb. In fact, we want to participate thoughtfully for our client portfolios without becoming dependent on any one single company or a theme or an outcome for that matter. My experience, that balance between this opportunity and discipline is what drives long-term success. That's the play. And none of that means investors should abandon AI or other technology or any other transformational ideas. is. It simply means remembering that when too many people end up on the same side of the boat, maintaining balance becomes more important than ever. Something to think about before we get to our guest today.
16:44Now, before we get to our guest, let me just talk about interactive brokers one more time because it's important because I know that you research your investments. I know you analyze markets, but have you researched your broker? For the past three years, Interactive Brokers' individual clients averaged 24.3 % annual returns, beating the S &P 500. Lower costs, competitive rates, and access to over 170 global markets helped investors keep more of what they earn. The broker you choose matters. Interactive Brokers, member SIPC. Learn more at ibkr.com slash performance. Visit ibkr.com slash performance.
17:29And let's bring them on because I want to talk about a few things. Next week, by the way, before we get to our guest, I'll mention, we're going to be talking a little bit about, I think we're going to touch on token maxing, possibly some of the things that are going on there. But more importantly, I want to talk about NUAs, Net unrealized appreciation. I want to talk about that because if you are working for a company and you have a 401k, let's say, with a good amount of company stock, not mutual funds, not investments, but the company stock itself, there is some unbelievably interesting ways in which you can save a ton of money on taxes and extend the potential for not having to take IRA-required minimum distributions?
18:18Technically forever. So I'm not kidding about this. We'll talk about that. So everybody that has a 401k needs to listen to next week's discussion because it's going to be a pretty interesting one. Let's talk about Tommy Thornton. He's a former portfolio manager, senior trader, and a technical analyst. He was with Level Global Investors, Galileo Capital. He's written a daily market note for a select group of hedge fund managers for years. And now he offers it to all investors with his company called Hedge Fund Telemetry. And his long-term focus on sentiment indicators borders, as he says, on the obsessive.
18:56So going to be pretty cool. He has a pretty active and exciting life passion following Formula One racing. and pretty interesting guy. Let's bring him right on and see what he has to say. Thomas Thornton, Hedge Fund Telemetry. How are you? I am good. Nice to see you. It's good to be on. Yeah. Been a little bit. Been a little bit. Matter of fact, last time you were on, I have this, April 5th was the last time you were on. At that time, you were, and I quote, lock limit short at that time, sitting on your hands. Confidence and courage was an issue. Oil and inflation was an issue. That was the things that we were talking about at that point.
19:40Yeah, a lot's changed. A lot has changed. You know, I will say, and truth be told, I did cover a lot in early April. My problem in Q2 was that I added back to some semiconductors, memory chips, and then I had to cut exposure in late May. And then they went up even more. And so I held on to a fairly small 1 % marker type position in a few, SanDisk and Micron, and that didn't feel great. But I added back in late June to full max 5 % position, and those worked out well because I covered both SanDisk and Micron. SanDisk was down 50%. So if you're, you know, if you've got a 1%, it goes up 100%. Okay.
20:38If you have 5%, it goes down 50%. You know, it's a win. So I'm pleased that I got those right. But it was the worst Q2 for me, partly because I look at just an overall market picture, and it was so narrow. I looked at everything on a relative basis, and everything was all semiconductors. It wasn't necessarily tech because the MAG7 didn't do that great, but it was all semis. And I think we're starting to see some changes. I'm going to interrupt you because I think there's something to be said about something here. And I think the lesson that needs to be discussed about this is markets don't always run on fundamentals.
21:25Markets, or stocks for that matter. and there are times where you can be right, but wrong on timing. Yeah, I'm 100 % in agreement. The thing about this that really, and I wrote about it a lot, was that the fundamentals in memory stocks couldn't be better. I mean, I used to work for a large hedge fund and one of our semi-analysts used to say, you buy Micron when they're taping a dollar bill to each chip and losing money. And then you sell them when, you know, everybody in the world thinks it's like a, it's not a commodity cycle anymore. It's, it's, you know, the greatest thing and it's going to last forever.
22:10Love that. So the fundamentals have been unbelievably good, like unbelievably good. 85 % margins for Micron. Well, I look at it. I look at that more so than the P.E. ratio on on something like this. The margins are probably going to peak. The problem I wrote about was that sometimes when you have crowded positioning, in other words, everybody is long the same things. And then you have leverage and then you have speculators that are not quite sophisticated. And I'll say that Koreans, I mean, we watched the Korean market go up and down. And I had put spreads on EWY, and I was short EWY from higher levels, which just recently got out.
23:00Probably another opportunity there if those pop again. But if you have everybody on one side of the boat, and the fundamentals are great, the boat's solid. But if everybody's on one side, that trumps the fundamentals. And that's what I think happened. And what happens more so is that when, as it happened with South Korea, they were heavily leveraged. They had single stock leveraged ETFs. They were utilizing only a few stocks. Everybody was on the same side. But when they started getting out, when all of a sudden the government came in and they said, you know what? We're going to change what we're doing here.
23:39You're no longer going to be allowed to leverage these single stock lever ETFs, right? A lever on a lever. And all of a sudden, everybody get out. When that happens, everybody rushes to the other side of the boat. Now, what's bad about that is I'm a boater. It's one thing having everybody on one side of the boat looking over and looking in the water saying, oh, that's interesting. Still, nothing's moving around too much, right? All of a sudden, when everybody flies to the other side of the boat, there's all of a sudden imbalance that happens. and it throws things out of whack and it creates a very uneven and a very precarious situation.
24:10That's what happened a week and a half ago or so in Korea where it wiped out, I think about 35 % of the under 35-year-old margin portfolios got whacked. Yeah, I saw Citi posted something about 300, well, I mean, it could be even more, but 360 ,000 accounts were liquidated and 40 % of those accounts were under 35 year olds. Now, here's something even worse. And I wrote about it like this is just a train wreck that's going to happen. It was like a slow motion train wreck. I read stories about 50 to 60 year olds in Korea that were cashing in their life insurance to go and buy the double levered SK Hynix double levered ETF that was in Hong Kong.
25:04Now, how about this? The problem that that ETF had by, you know, when it attracted$20 billion in assets is that it could no longer keep up with the leverage. So what they did is they went out and bought out of the money calls and the put call ratio, I posted it on X, you know, over a month ago or whenever. It was like crazy. The most absurd, you know, amount of calls versus puts. I mean, there was like 900 ,000 calls versus 2 ,500 puts. So that type of behavior was just an explosion, or I should just say a very thin membrane bubble that just bumped into something and it popped. It's devastating because I think that there's a lot of gambling type mentality like that in the US.
26:09I'm not saying it's as narrow and concentrated, but things could get dicey if, you know, we start to break some deeper levels and we really haven't yet. Well, we started to do just recently single stock futures just came out a couple of weeks ago that were reincarnated from the graveyard. And the other thing that's interesting is when you look at Korea, I think there's a lesson in that. I really do. I think there's a really good lesson to be learned with this. the idea that when you see it, you're like, oh, I want to play in that, you know, I want to play in that ocean, not realizing the perils that are the jellyfish and the man of wars and the sharks and the piranhas and the barracudas.
26:51It's like, OK, look at that. It looks like a great. I have no problem with that until all of a sudden there's blood in the water. And then things change pretty dramatically. But I don't think that looking back on it, that there's a surprise to anybody about what happened in South Korea with their 12 percent moves up and down on their markets. was anything more than a speculative bubble that had a pop. And if you look at the levered South Korea ETF, I think it's down 69 % from its high. And that's just a little bit of a move down. There was one, I think it is K Kuru. Yeah, Kuru, yep, yep, that's it.
27:28Like 3X levered, and they had to do a reverse split to avoid it going to zero. Yep. And it's still getting absolutely hammered. Actually, it's$14. And they did a split on it. But if they didn't do that, it would be a zero. And I think that my view is that there's a lot of stuff you can invest in right now. And there's a lot of good stuff rather than this get rich overnight or immediate thing to do. So I think we're starting to see some opportunities to get long ideas and pick off shorts when you see it with crowded positioning. I mean, the Bank of America Fund Manager Survey had three months in a row of the most crowded short or long, sorry, being semiconductors.
28:27Clearly. I saw that. And again, I absolutely barbecued myself on smaller size, but it's still it hurt like hell. The question is the braveness to get back in, though, and to go back to what your conviction is. I got to tell you something. I've said this before. You may have heard me talk about this, but there was a story back in 1999 ish where the baby right then, the love child of the markets was Dell. and Dell was going crazy. It was a 30, 40 % increase in revenue and earnings on a regular basis. And if you would have calculated and done that for a few more years and recognize how much they would have had to sell, each one of us would have had three to five Dell PCs on each of our desktops in life, including the counters in your bathroom, your kitchen counters and your coffee tables.
29:21And that was just not something that was sustainable. And that's, I think, primarily the lesson I learned with that stuck with me since, I don't know what year that was, 1998, 1999 or so, give or take, 2000. And that lesson has taught me that, you know what, when I go into these shorts or these crowded trades, this is me, you tell me what you think. You enter in slowly because they don't, that kind of momentum doesn't end quickly. People will come in the day after and buy because they think they got a bargain. And, you know, you keep on getting skewered. You said barbecued, but you get skewered.
Read the full transcript
29:57And after a while, you're like, I'm not doing that again. I'm not touching that hot stove again. But you got to stay with it, right? Well, I can tell you as a technology trader and a$5 billion hedge fund, there were a lot of times where we would short something, cover it, short something, cover it, and then short it again and win big. And sometimes you just have to, you know, inch it out there and see what you can do. And if it doesn't work right away, but if you have the conviction and you know, the signs of overvaluation or crowding or whatever, earnings that are going to decline, those are the things that you do.
30:41So it's not a, you know, this is something, something, somebody just sent me something about showing me the NAS or the NASDAQ in 2000 peaked around, you know, so it's about actually it was not NASDAQ 100, close to 5 ,000. And it went down 40 % in less than two months. Yep. Now, we haven't really seen that type of volatility. Right. And, you know, so I, you know, and some people are like, oh my God, the volatility is so bad. No, we haven't really seen that yet. Well, the VIX can't get above 20. Let's be honest. That's amazing. One thing I don't, I don't really watch the VIX that much. Well, it's kind of a broken instrument.
31:26Let's be honest about that. Yeah. I watch CDX credit spreads to see if they're widening. And if you see investment grade and high yield credit spreads starting to widen, and they have started to widen a bit. that's really the big tell. Look at Meta's CDS. Look at Oracle. I mean, they're peaking out pretty hard. And this all deals, last week we had on Chris Whalen. You know Chris, right? Great discussion about some of these factors that are going on. We saw the 30-year bond hit a high since 2007 last week. These are all happy. Now, here's my question to you. We see market leadership is starting to change beneath the surface, right?
32:09We saw things like healthcare doing really well. Staples starting to come up. A variety of utilities holding on really well as all this is happening. It tells me a story. I think I talked about this last week that there is a desire for investors to be invested. What I mean by that is it's not like, okay, I'm investing. I don't like things. I'm coming out. No, they're investing in like packs. It's like a wolf pack into the semiconductors. Then when the semiconductors come back, They don't really go to cash. They don't go to bonds. They go to other places. Like they're going to all of a sudden hit to the consumer staples.
32:42They're going to all of a sudden go into healthcare, right? And if they use it as a holding place, what's going on then? Is this a normal rotation right now? No, this is something that's been going on, I think, around since COVID. We're like nomads of traders will go from one green thing to another. And I think there's a lot of the people that have no idea even what these companies do. It gets into this crazy speculative moments where stocks that you've never heard of go up 200 % or they change their business profile to blockchain or AI or something, and they go nuts. And people just jump into these.
33:30That is just gambling. And, you know, I'll tell you this, when you're saying that people don't get out, that's a very good point. I think it's sort of that people need a dopamine fix and they're using this or gambling on sports or prediction markets or other things for that. You know, that's a real risky behavior. And I think that's just where we are as a society. One thing, though, this is important for longer term investors. You know, I'm friends with lots of smart hedge fund managers, a lot smarter than me. And Paul Tudor Jones said on a podcast with another friend of mine, he said the U.S.
34:25has never been more dependent on the stock market. And he said that, and there's a lot of ways to interpret it and the way to think about that. But I think it's really important because he's right. You have so many people are in passive funds with their retirement accounts. the stock market wasn't designed as a retirement account proxy. It wasn't designed for that at all. I mean, retirement accounts should have a mix of stocks, bonds, commodities, a lot of different things you can put in there. But it's become the de facto place where people have gone to invest. Now, the US is dependent on it because you need high stock market.
35:16It helps unemployment stay low. Uh, it, it's, it brings in money from foreign countries. Uh, but I think the dependence is really risky right now. Uh, well, I mean, it used to be, it used to be tough. We don't fall down again. If we went down 40 % in two months, like we did in 2000 and then rallied back 43 % within another two months in July, and then ultimately failed, you know, I think you'd lose a lot of people in the market. like you did back in 2000. But that was temporary. It was a different person. Right now, I think people are looking a little bit behind it, ahead of this. But one of the things they're not doing is people don't want bonds.
35:58I mean, there was a time when you could say reasonably that, you know, bond yields go up. And still to a point, we haven't been there. We haven't seen this peak out. You know, if we get, I don't know, pick a number, 10-year at 6%, I'm just saying, some people may be like, you know what? Cashing out a few things over here. The other problem you have is people are unable to leave their positions. I can't tell you how many clients we have with enormous unrealized gains inside their portfolio. That's a great thing, right? So I'm happy about that. We're able to do that. We're able to get to that point.
36:31But the problem is where to next? How many people have Apple in their portfolio, Microsoft to a degree, Meta, NVIDIA, you name it. Even with the drawdown that we saw recently, low cost basis, what do you do about that, right? Isn't that a big problem in the market? I get it. It's a problem. And you have a lot of these, you know, the corporate insiders that have huge gains as well. And they're just using leverage to live comfortably and not having to ever sell. That, you know, creates some issues as far as tax revenues. but are people going to, this is my thought, are people going to be able to live through a 50 % drawdown in the market?
37:16That's a good question. As much as that sounds like that will never happen, it always happens. At some point in time, it's going to happen. I'm not one of those, you know, doomers that's going to say, oh, you know, next week it's coming, look out, get out. But I wonder if some people are going to be able to hold on because you're starting to see some real pullbacks. I mean, the Micron and SanDisk, I mean, down 50 % from its peak high, still up huge. But if you go down even more, look out. I mean, everybody, I always love the people that Amazon reports and they say, well, if you bought Amazon on the day of the IPO, you would have X amount.
38:02And I like to remind people that you went up 6 ,300%, down 90%, and then up another 5 ,000%, and then ultimately down 93 % to the ultimate low. That's a hard thing to hold comfortably and say, I'm feeling good about this. It's really difficult. I mean, that's, of course, you know, splits and stuff like that, but you know, it's, it's, you know, the buy and hold, it's great, but it's, I think it's going to test some people, um, that are holding just because they don't want to pay tax. Right. I think that's a valid point, but it will test people. I do wonder, I mean, by the time we air this episode, we've probably been through most of the big, uh, technology earnings.
38:52We saw the first meeting, big flop for Kevin Walsh. I mean, it was interesting. I'm sure you watched it, read it, et cetera. His press conference, he said he's not going to have any press conferences unless he has something to say. They had nothing to say. And in his press conference, it was like, you know what? We're going to let the markets decide? It's like, what? Are you going to put that out there that you're going to allow the markets to decide? Therefore, they're going to test the hell out of you? And they did so, right? with the 30-year spiking, 210s got a little wonky. There was a lot of weird bond movement.
39:26We're seeing that and not follow through necessarily by the dollar. But those kind of conversations, if he continues with this nonsense, I am not a big fan of the communication strategy of the former couple of Fed chiefs. Not at all. But this idea of letting the markets tell us and lead the situation, like a free market for rates. Kind of weird, isn't it? Well, I think there are a lot of things that are weird this last couple of years, but I will say, I think the Fed is boxed. I don't think they have really much they can do right now. You know, I think you're going to see inflation remain sticky.
40:11It could go up a little bit more. You still have hostilities in the Mideast, and crude seems to want to hold elevated levels. It could go higher. You have crack spreads at unbelievably high levels. So it costs more money for diesel and gasoline out there. And that, I think, is hurtful for the economy. It's inflationary, obviously. But I think that if they raised rates, let's just say the Fed raised rates at the meeting, what was the purpose of that? Was that to control inflation, slow down spending? I think the only thing that I would have argued for raising 25 basis points would be simply to establish some credibility with the markets.
41:09I agree. He didn't do that. And I keep thinking, what's Trump's nickname going to be for him? I think it's going to be wishy-worshy. You know, wishy-worshy. Because I think he doesn't really have anything he can do. And I don't know what the Fed cutting rates would do. It didn't work for Powell because treasury rates are higher. And even they were higher even without the war and the latest bout of inflation that's coming in. And the second round of inflation is tough because people are still dealing with higher prices. So it's higher prices on higher prices is the problem, right? We got higher prices on a higher price base.
41:55So therefore, even a touch of inflation is that much more difficult. We saw the GDP deflator come out last week. PCI came out 3.3 % on a year of, PCE came out 3.3 % year over year on an annualized basis last week. And then we saw also the GDP deflator, 6.3%, I think it was. But what that was showing was a lot more underlying pricing pressure to the upside than we expected. And, you know, you look at some of the other numbers, really big question. So now when you look at all of this, you look at things and your process that I know of you, because you and I have been talking for a long time. You include sentiment indicators, you're in positioning, market breadth, and you use DeMarc, these exhaustion signals, the 13s, the 9s.
42:44Which indicators right now are giving you your strongest either warning or your strongest green light to do something? You know, I just did a deep look at market internals, and I really have not seen anything get oversold. And that's something I think is really important. That could be the percentage of stocks in the S &P above the 20-day or the 50-day. That hasn't gotten oversold. Those are really pretty simple stuff to watch. The DeMarq sequential had upside exhaustion signals in the S &P. The last one was 6-1 on June 1st. And you had one day where it went one higher tick. And then the market's gone sideways to down.
43:51The same thing happened with the NASDAQ. So at the beginning of June was when we hit highs, and we haven't been able to establish anything higher. Now, we've just been on the potential for a 13-week closing low for the NASDAQ. We had 12 weeks, so we'll see what happens. But that, I think, is important. People don't realize that there's been a lot of weakness out there, but sort of sideways. You know, there's been rotation, you know, the equal weight indexes hit new highs. So that's sort of positive. But I'm not really convinced that's what you want. You want the real market leadership to broaden.
44:43Wait, wait. Doesn't the equal weighted index reaching new highs talk about market? leaders broadening? Isn't that the actual definition? It does, but what you'd like to see is you'd also like to see the, you know, the MAG-7 and the semis and everybody else, you know, working together, not necessarily in any outside, outsized move, but just sort of together. It's either one or the other. Yeah, that's true. And that's been sort of this year. This year is the LAG-7, by the way. We call it the LAG-7. Yeah. I mean, on my screen, I'm showing the MAG7 is down on the year. And you can weigh that with heavy Tesla down 30 plus percent.
45:28That has weighed on it. Meta's down almost 20 % for the year. But you have, I mean, some others that are doing pretty well. But again, I think we're coming into a tough seasonal period. I think there's still a lot of risk. Well, we got to be talking about midterms, presidential cycles. Yeah, I mean, midterms, you always have seasonal periods with August, September, October. Those can be a little tricky. So far, I think things are holding in there okay. Again, this is on a delay, so things could be a little dicier. But I think it'll take time for really a bigger decline to occur. Now, the indicators you said, like, what am I watching?
46:17We're on the cusp right now of seeing some DeMarc indicators on the downside start counting down. So you're kind of at these, like, sort of holding place right now. But if we have any continuation lower, then those are going to start to come into play. And I'm watching those. But those are inverse indicators. Is that correct? So when you hit that DeMarc low, that becomes a point where the exhaustion signal, because there are exhaustion signals. Exactly. I don't think a lot of, listen, first of all, most people that are listening don't even know what the hell a DeMarc indicator is. Yeah, I question it at times too for me, but no, they're complex indicators.
46:56Very complex. And you have to know how to look at them. You have to look at them backwards sometimes. And he's a brilliant guy. Tom DeMarc, brilliant guy. I spent some time talking to him a number of years ago, but he's got a lot of different indicators. But the 913, the exhaustion signals, reversals. Oh, yeah. Uncanny how they work. It's weird. But I've used the indicators for over 25 years. I know when they work. I know when they're less effective. I know when to press. I know when to, you know, really get in, you know, get long. back in other periods like Liberation Day, we had downside exhaustion signals when everybody was saying everything was going down.
47:37And we got long at S &P 4 ,800. Of course, we sold out a little too early, but that's - Well, because you'd get the exhaustion signals on the other side because that made you move up. That's a natural process, but the point is at least you didn't get out. Yeah, I mean, I think that those, And that's kind of what I'm watching right now. If we break certain levels and start to decline and you can't get the president to taco his way out of it, I think that's the risk. I think the inflation number for July is probably going to be OK. I worry more about the August number because some people don't get this, but the data is surveyed on the 12th of each month.
48:25So let's say, let's thinking of the July data, it's surveyed on the 12th. So gasoline prices were almost at the low down from June 12th to June or July 12th, down about 8%. Since then, they're up about 8%. So next month could see inflation sort of pick back up. But I don't think - But they'll say it's just the food and energy, food and energy. We Nobody eats drinks or actually uses fuel. So it's fuel and energy that's not it. And we don't think about the fact that truckers use it. Or pay for houses or rent or, yeah, I'm waiting for the inflation number. Oh, they're going to reconstitute it. They're going to change it.
49:06They're going to change it. I'm telling you, they're going to change the, Warsh is going to go in and he's going to change. Mark my word, okay, the inflation calculation, because they want to get rid of that whole rental deal, you know, the housing equivalent costs. Yeah, that's not a big expense for people. That's nothing, right? Yeah. I think that there's a lot of ways you can just think about inflation. If you go to a restaurant and you're the one picking up the tab for your family, how does that feel after? I mean, it's sort of, I want to regurgitate sometimes what I just ate when I get the tab going out to dinner.
49:47It's expensive. Beef prices are higher. You know, wine, alcohol prices are more expensive. Everything has gone up. Everything has gone up. I know this also because I'm very involved with a club and we look at the pricing. The pricing of things, while the excitement has been that beef pricing has stabilized, that's stabilized at a ridiculously high level. When you go from tomatoes at$20 a case to$80 a case, and they suck, by the way. Horrible quality tomatoes. Avocados due to the taxes and tariffs. A lot of stuff getting crazy. But let me kind of switch gears here because we can talk about inflation because it's just one of those things that people think people just don't believe anymore.
50:30Or people, I feel that a lot of people have been turned off to a lot of the economic things. They're just numb to it. It's like, whatever, stocks go up, I don't care. The idea that making money heals all things, like we don't really care about what else is happening. But away from major technology, where are you finding the most attractive opportunities over the next, I don't know, maybe six months to 12 months? and, you know, where would you be comfortable with maybe taking the side of consensus? Or the other side of consensus. A couple of questions in there. I think banks are a little stretched.
51:10I bought energy pretty well, and I tended to buy just, you know, the big majors because I saw it was actually when things were pretty calm in Iran. And but I bought Exxon and Chevron and they're up, you know, nicely, like 20. Huge, huge. Those are good. You know, one like I'm starting to look for brands like this is sort of going back into the my view with, you know, old school type stock picking, looking for brands that have easier comps. So, you know, earnings comps get easier after they've been hard. and certain things that have been beat down pretty bad. You're talking about like the Nikes, the Chipoltes, those kind of names.
51:57I mean, Starbucks is a good example. They just reported earnings. Their numbers were great. Comps are good. They have a new CEO who was a Chipotle CEO and did phenomenal there. People really like him. And the stock's done well. I'm starting to look at, I'm in Nike as much as everybody just wants to go, oh, no. No, it's down 75 % from its high. They have a new CEO, new CEO. They're getting a new CFO who's a turnaround specialist who turned around Levi's. That's positive. The comps get easier. They've worn down the high inventories globally. They still have issues with China. But I think things are worth taking a look with it down 75%.
52:51The CEO bought stock twice. So did Tim Cook, a little higher than where it is right now. And this is in the mid 40s. And so I'm here at this price. I bought some Lululemon, similar story. Interesting. Pumps get easier later in the year. They've got new management starting in August, September. it's down again one of those that's down 75 % off the highs uh which by the way both of those two both those two are great examples of the changing preferences of the consumer and if you don't think that you look at chipotle as well which was the darling for years and you look at various brands that we don't even like remember claire's boutique remember that one oh yeah where's that nowhere gone.
53:39But you look at those kinds of things and there is, because of a lot of reasons, whether it's fashion, whether it's diet, whether it's the GLP ones, right? What's going on in the liquor industry, for example. And there is a changing habit of the consumer that is a very difficult thing to peg sometimes. But when you get it right on the long of the short, it could be glorious. Yeah, I'll tell you one other area that I've been buying, and I started buying in June, is China internet. And that's another one that people will roll their eyes and say, you know, God, but I think that the China internet stocks, Alibaba, JD, Baidu, and I'm looking at, I bought, you know, very simple, I recommended KWeb, FXI, those are up 15 % to 20 % off the lows when nobody wanted them.
54:35I mean, I had people say, are you kidding me? Why would I want to buy Alibaba at 95? Well, they came out and said their earnings are going to be better. It's also been, and I wrote about this and I put a very special report out on our big picture note that basically said Alibaba and Tencent and the biggest China tech names own pieces of all the open source LLMs, the AI models, moonshot AI. Nobody heard about that. And boom, it comes out. And guess what? Guess what? Nobody else here knows about Alibaba owns 35 % of this company and they just did a valuation of$35 billion. I think they probably put maybe, you know, 500 million or a billion dollars into it.
55:25That's a good return. So I'm kind of looking at stuff like that. And there's risk. You're going to have the US models complain, and they're going to say they're ripping us off. And they all look at each other's models. There's no doubt. The US models look at each other. They've already discussed it. They've talked about it. But the token costs are less in China. And I think that that's going to be the main driver, that if you can have something that works really well for less cost, with less expense for hardware, and upkeep and build out, sign me up. That's where I want to be. And Alibaba also has their Quen model, which is their AI model, that is going to be in all the iPhones in China.
56:14They beat out Baidu, which I thought was the company that was going to get that. That's another big one. So Alibaba is in the, it's not that far off of 100. I think this is a$200 stock. And I've traded this one along for many times on the long side. I actually got into this, into Alibaba, and I helped some friends get into Alibaba when it was a private company, when Yahoo had to divest. I remember that. It was$10 a share in the private market. And I helped some hedge funds place$50 million into it, which turned out to be pretty good after the IPO. But the thing is, this is a really good, diverse company.
57:01And Alibaba, here's the other thing. They're making chips. They're doing AI models themselves. They're doing cloud. They've got their retail. They've got banking. They've got so much across the board, and they're not taking one lane. They're doing it all. And I think China, their government, has the ability to do stimulus. I think that'll help certain areas that they have. Their economy is pretty depressed. Yeah, and if this becomes a war with AI versus, you know, U.S. versus China versus China, I think China is a pretty formidable opponent here. I'm going to be involved in those. So I hear you.
57:42I hear you. You know, somebody will say, Oh, it's so anti U S and all that. Hey, you know what? Capitalism. It's, it's, it is, it is U S right there. It's looking for where the best opportunity is and go grabbing it and making money. I just want to say, you know, I had somebody, you know, I was on another video at the end of June and I was saying similar stuff. I liked energy. I liked China internet and, you know, Tom's a terrible investor. And, you know, I'm short semis. You know, he's, he seems really depressed and all that. You know, you can't win at times, but because, you know, you can watch this a year from now, my position could change.
58:27You can watch this three days from now and your position changes. That's the whole point of being an active investor. But the point is sometimes you got to buy things that are out of favor. You know, if you, I don't watch CNBC, but I would imagine if you did, you probably have watched nonstop semiconductor coverage for the last three months. Well, thank God, because they're not talking about the Fed anymore. Thank God. I mean, they still got to sneak that in there. Or SpaceX. What a rug pull that was. We could save this for another time. I want to ask you one final question in closing, and that is, listen, you've been around a long time.
59:00You've traded crashes and bubbles and failures of major hedge funds you've been involved in. What is the clearest, because I know you have some negativity going on right now, but what's the clearest warning from market history that investors you think that right now are maybe ignoring? I think that is probably.
59:26I'm going to say this, and it might seem pretty obvious. But I think the market cap concentration in the S &P, especially with the AI optimism and the whole circular financing, it's different from the tech bubble. And I traded through the tech bubble at a hedge fund, and that was difficult, but we came through pretty well. But the thing is, there's another comma as far as how much they're going to spend and how much their market caps are. It's a lot bigger. So the risk is that when things go down, and let's say, I was just looking at a chart somebody sent me that in March to May in 2000, the NASDAQ went down 39%, 40%.
1:00:23percent. If that happens, that's a, that's a lot of market cap. And that's a lot of money that people will lose. So again, not to mention all of the borrowing they've done to build out these data centers that are based on all this. Speculation, short-term options, you know, inverse ETFs with$200 billion. And it's, there's all these things in there that you're going to say, where were the signs, you know, but that's really it. I think just, we're talking a lot about big market cap, big promises, big expectations of what companies are going to be able to raise. And I think that's really, that doesn't come through and that starts to deflate.
1:01:07It's going to deflate like pop in a bubble. Yep, I hear you. Thomas Thornton from Hedge Fund Telemetry will have all the information on the website, on the Disciplined Investor Show Notes for episode number 985. you want to tell people where they can get in touch with you and how to get in touch with you and what you got to offering. Yeah. I'd like to talk to you about that. I am in the process right now of rebuilding our website. And I will tell you, yes, I'm excited about that. That's my entire project tomorrow to work with my programmers. It's going to be quite good. It's going to have a lot of, you know, trade ideas, short, intermediate term core ideas.
1:01:46but you can reach me at info at hedge fund telemetry for a trial and you can either sign up as well and I'll give you 50 % off. If you use 50 off as the coupon, 50 off. I like it. 50, 50 off. Yeah. The coupon code. You get 50 % off. Awesome. Great. We'll make sure that people get that. All right. We'll talk soon. Thanks. Thomas Thornton, always a great guest on always a load of information. I love that guy. Just check out all the stuff that he has on hedge fund telemetry. I think you'll really enjoy it. By the way, quick update on my knee. Got it all taped up with this KT tape stuff, which looks kind of imposing, like I'm a volleyball player ready to go.
1:02:28But things are going good. Walking without crutches and getting along pretty well. Not too much pain, a little bit of swelling, but everything is good. So that's pretty good. Anyway, I want to make sure that you are there next week. We have some great guests coming up, And I want to talk about this NUA net unrealized appreciation and explain it to you, especially if you have a 401k withholdings of company stock. That's it for now. Thanks so much. I'll see you again next week.
1:03:01This podcast is intended for informational purposes only and does not constitute personalized investment advice. This investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz & Company, Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements.
1:03:39Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement. Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates of Horowitz & Company.
1:04:29We'll be right back.
From the publisher
Gold and silver ripping.
Jobs numbers telling different many stories.
A good lesson from crowded trades – Let’s not Tip The Boat…
Thomas Thornton, Hedge Fund Telemetry is this week’s guest.
NEW! DOWNLOAD THE AI GENERATED SHOW NOTES (Guest Segment)
Thomas Thornton is a former portfolio manager, senior trader, and technical analyst with Level Global Investors and Galileo Capital. Tom has written a daily market note for a select group of hedge fund managers for years and now has offered it for all investors with Hedge Fund Telemetry. His long term focus on sentiment indicators borders on the obsessive. Our growing team at Hedge Fund Telemetry is comprised of current and former buy and sell side individuals.
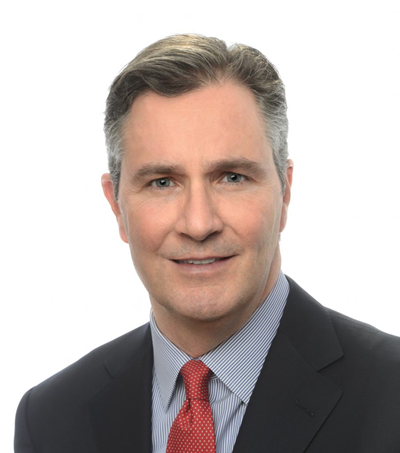
Hedge Fund Telemetry was first conceived with inspiration from Tom’s lifelong passion following Formula 1 racing. In the early 90’s, Formula 1 teams started to equip cars with sensors on every imaginable component and data was relayed wirelessly through telemetry to the pits to analyze and then instructions from the pits were relayed back to the driver so he could make changes to find the optimal balance for the car. It has always been the same way for Tom, as a senior trader at his hedge fund, he would get in early, collect data from many sources, analyze that data, and then communicate information out to his firm so his team could properly balance the firm’s portfolio. It’s now our goal to relay that same type of information so that one can also gain that edge.
Check this out and find out more at: http://www.interactivebrokers.com/
Looking for style diversification? More information on the TDI Managed Growth Strategy – HERE
Stocks mentioned in this episode: (SNDK), (MSFT), (BABA), (BIDU), (GLD), (LULU), (SBUX), CMG), (NKE), (JD), (KWEB)