
In short
```markdown The Disciplined Investor Podcast - Episode #952: Live and Let Live
Episode Overview
- Title: TDI Podcast: Live and Let Live (#952)
- Description: Delving into economic trends, market movements, and a special guest segment featuring Robbie Miles, CEO of Live and Let Live.
Key Topics Discussed
Economic Trends
- Inflation Insights:
- Recent economic data indicates inflation is lower than anticipated; November core CPI was at 2.6% vs. an expected 3.0%.
- Discussion on the implications of this data on market behavior, with a notable rebound following a dip in the market.
Market Dynamics
- Market Sentiment:
- Acknowledgment of the duality in market analysis: top-down (economists concerned about inflation and employment) vs. bottom-up (earnings reporting better than expected).
- A significant percentage of S&P 500 firms reported earnings above analyst expectations, leading to a mix of investor sentiment.
Corporate Governance and Concerns
- Oracle's Financial Practices:
- Discussion on Oracle's recent financial disclosures and potential areas of concern regarding transparency and management credibility.
- Investor skepticism regarding the tech sector's growth narratives, particularly around AI investments.
Featured Guest
Robbie Miles
- Background: CEO of Live and Let Live, a movement focused on fostering peace and personal responsibility.
- Mission:
- Advocate for a world where individuals coexist peacefully, promoting voluntary kindness while minimizing aggression.
- Current Initiatives:
- Focus on tolerance towards differing views, especially on divisive topics like abortion, and the importance of local governance to facilitate peaceful coexistence.
Conversation Highlights
- Philosophy:
- Emphasis on the universal golden rule across all major religions: treat others well and avoid aggression.
- Issues of Interest:
- Discussed various topics where reasonable minds disagree, promoting dialogue rather than conflict.
Investment Insights from Robbie Miles
- Sustainable Investing:
- Critique of the sustainable investing movement and its practical implications on portfolio management.
- Distinction between morality and stock price performance, emphasizing that ethical investing should not sacrifice returns.
Investment Strategies Discussed
- Fundamentals vs. Sentiment:
- The importance of understanding a company’s business model and incorporating macroeconomic indicators into investment strategies.
- Valuation Metrics:
- Discussion on using PEG ratio (Price/Earnings to Growth) as a significant metric for evaluating investment opportunities.
Notable Quotes from the Episode
- "Investing without fundamental analysis is like getting ChatGPT to write your essay for you."
- "The stock market is a device for transferring money from the impatient to the patient." - Warren Buffett
Concluding Remarks
- The episode closes with reflections on the year’s market dynamics and the importance of maintaining a disciplined approach to investing.
- Teaser for the next episode featuring another prominent guest in the investment space.
Stocks Mentioned
- SLV (Silver Trust)
- GLD (Gold Trust)
- ORCL (Oracle Corporation)
Episode Links
- [Listen to the Full Episode](https://podcasts.apple.com/us/podcast/the-disciplined-investor/id217999782)
- [Download Episode Show Notes](https://thedisciplinedinvestor.com/blog/wp-content/uploads/2025/12/TDI-Notes-and-Summary-Miles.pdf)
``` This markdown file summarizes the key discussions and insights from the podcast episode while providing a structured and accessible format for readers.
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Transcript
Automatic transcript. May contain errors.0:00This episode is sponsored by Interactive Brokers. And are you looking to trade gold or silver, maybe platinum or palladium, with low costs and global access? With Interactive Brokers, you can trade spot metals, futures, and options on major exchanges, all from one powerful platform. Get efficient pricing, deep liquidity, and institutional-grade tools right at your fingertips. Whether you're hedging or investing or diversifying, Interactive Brokers puts the world of metals in your hands. Member SIPC. Futures are not suitable for all investors. U.S. gold trading is available only to legal residents of the United States, excluding residents of Arizona, Montana, New Hampshire, and Rhode Island.
0:44The best informed investors choose IBKR. Ready to get started? Visit interactivebrokers.com slash metals and start trading smarter. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast.
1:06Robbie Miles:This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz & Company, from seed through harvest, cultivating financial success.
1:24The walls are coming down. The house of cards exposed. We have economic data, by the way. Late, but we got it. And that concludes the last full week of trading for 2025. And our guest today is Robbie Miles, CEO of Live and Let Live. He's back. All this and much more on episode number 952 of the Disciplined Investor Podcast.
2:05Wishing you and everyone you know a wonderful holiday. No matter what you celebrate or not. Maybe you do, maybe you don't. But basically, this is a time in the holiday season that we spend time with friends and family. And we have those arguments and that fun. We talk about things like what's going on in the world. And of course, we talk about money and some of the things we're going to talk about today as well. Some of the things that happened over the last week and some of the things we think are going to be seen in the future. And we do have something to talk about because last week we did see that inflation is, well, less than anticipated.
2:44Magically. Magically. It's a Christmas miracle, I tell you. They did some fancy averaging over the September to November period. And out came, miraculously, in November, the October CPI, which is missing, and the November core, which is 0.2 % on a month-over-month basis. That's annualized at 2.4%, still above the level that was concerned of 2%. And then the November core CPI on a year-over-year basis was 2.6%, and that was versus an estimated 3.0%. So markets after a day on Wednesday, which we'll get to in a second, imploded on a lot of news that was very concerning. And when those people that are fundamentally driven look at the numbers, what we saw in the news on Wednesday, they say, wait a second.
3:38You know, earnings are the mother's milk of the markets. But yet on Thursday, we have all sorts of excitement and a rebound, basically recapturing most, if not all, of the losses from Wednesday. due to the fact that we had a rather benign inflation number. So you have the economists, the top down, that are freaking out for a while there. Now they're coming back and saying, well, things are okay. We had the bottoms up that had a little bit of pain after a long time of saying things are really good. The fundamental side of things is actually confused. Not to mention that technically charts are still looking okay, A, we see a little bit of a reaction to the downside inside of a longer-term bull market, which keeps and holds the thesis that we are in an uptrend.
4:31So technically, we're in an uptrend with a little bit of a dipsy doodle, as my friend John C. Dvorak would say. Fundamentally, two sides of that from a top-down approach. We have some things that are concerning. We have the employment situation, the slowdown in manufacturing and services. We have the concern about what's happening with the sticky elevated inflation numbers. But on the bottoms up, all of a sudden, we were really pretty satisfied with the earnings beats that we saw. We saw that Faxit came out with, what, 78 % of earnings were ahead of, for the S &P 500, ahead of analyst expectations for last quarter.
5:11We're seeing double-digit year-over-year gains in growth. So things are pretty good. And then all of a sudden, we have a lot of this coming out that's pretty outstanding with CapEx expenditures. And we're going to talk about that. And what the real story was, what happened on Wednesday, we've got to get to. House of cards, we called it, maybe. Well, if you've been listening, I've been moaning. I've been groaning about this whole Oracle situation, which seems to be like forever. It's probably been the last four or five months. Definitely the last four months. They have definitely pumped up and now dumped the AI trade.
5:52Now, not in all areas, but pretty much the most speculative side of the entire AI trade was really put to rest recently as some of the new and improved numbers and realities came out from many companies, and in particular, the OpenAI commitments and Oracle with their loans, etc. But new out this week was some really concerning information about the post-conference call, the post-earnings call, and management had a lot to talk about. But after that, a day after, there was a debt and financial commitments note put out, levels that were not even on the balance sheet as of the last update. And the question then was, wait, what are they trying to hide?
6:47Why is it that we have this enormous number of lease payments, this enormous number of debt that was after the earnings announcement and after the conference call, trying to put that out of the hands of investors and analysts? And things got a little bit chunky right there. So the question is, again, what are they trying to hide? And now that some of the financing is in question for Oracle's Michigan data center, there was a natural fallout. Now, fast forward a day after all that information came out about Blue Owl, which is a very, let's say, concerning lender, private debt type of company. many are saying that well the markets misinterpreted that that wasn't like a last minute thing at 3 45 p.m on on Wednesday this is an early day look at what is going on and the commitments that Blue Owl is possibly pulling out of this particular financing and Oracle will have to go somewhere else to get the financing and okay Oracle has plenty of places to get it but the question then remained again why is this happening now maybe it's because Blue Owl has their own trouble, as we saw, but something is definitely a little bit off.
8:18And what that really is doing is evaporating the credibility of the entire money spend with AI, artificial intelligence, and the build-out of the data centers via CapEx that has been underpinning the AI trade and the tech trade for however long it's been. So where do we go from here? So some of the errors come out of the markets. And in general, we look at the S &P 500 with 38 % of the S &P 500 being the top 10 stocks and, I don't know, 65 % of the NASDAQ 100. And that's why that got hurt on that Wednesday with, again, the comeback at the end of the week to a degree.
9:02So I think that we have a little bit of concern That's probably going to be in a lot of people's minds Many don't want to sell by the end of the year Because of the capital gains on the growth that they had Which has been extraordinary on many of these names Maybe waiting until January Something to think about But this is still a long way to go with this technology And we still don't know the true potential Of how it will be actually monetized I think we're entering the next phase of this trade, and that goes from enthusiasm and excitement and just unrestrained and unbridled bullishness to a dose of reality.
9:44So I think that's a major part of where we are right now Is that we're in an inflection point of people trying to understand Where all this money is going to And do they want to continue chasing this particular trade If in fact there are some holes in the dam And is this oracle canary in the coal mine a one-off or is it the entirety of what's going on? And that's something that investors are going to have to deal with moving forward. Now, next up, before we dive into a discussion today any further, I want to take a moment to zoom out a little bit. I wanted to think about decades and bubbles and crashes and recoveries and everything else in between.
10:38Because one thing has remained constant through all this. It, it's the wisdom of those who've studied money and looked at behavior, behavioral finance, and have been knee deep in the markets long before any of us. and I wanted to, I pulled out a bunch of, I would call them what, timeless financial quotes and sage advice on investing. They're short, but I thought it was ending towards the end, we're getting towards the end of the year here and through the holiday season. It would be good to go through these because these aren't just clever lines. What these are are battle-tested principles that are forged through the experience and success and a lot of mistakes that go into this.
11:36So let's kick things off with a few of these quotes, the kind that remind me of why we stay disciplined and thoughtful and informed and why that always pays dividends. So first up, you got to talk about what would Warren Buffett say, right? I want to talk about this one. He says, be fearful when others are greedy and greedy when others are fearful. That's kind of the blood in the streets discussion, right? Buy when there's blood in the streets, which he's done over the years. Remember during the financial crisis when Goldman Sachs was going under and he issued a$5 billion note bailout basically to them at some, at that time, exorbitant rate.
12:15Everybody's like, what? How is that going to happen? And he made his money back and did really well with it. Now that item there, that buy when there's blood in the streets or be greedy when others are fearful, that's always a question, right? Because markets can extend a lot longer. Markets can move a lot lower for a period of time and it can move a lot higher for a period of time. So if you're fearful when others are greedy, maybe you get out too soon. When you're greedy when others are fearful, maybe you get in too soon. And that brings us to what John Mayer Keynes would say. The markets can stay irrational longer than you can stay solvent.
13:02If, in fact, we are in a situation where markets are seemingly up, up, up, up, and you decide you want to short that market, and all of a sudden it continues up another 20%, 30%, that's not going to look good on paper, is it? And you may, in fact, get blown out of a position, forced to cover, and that is going to maybe take its toll on your portfolio. And going back, there's a few of these from, there's like two or three of these that I picked up from Warren Buffett. Risk comes from not knowing what you're doing. Not knowing that, in fact, things can go against you in the wrong way. It is a risky proposition.
13:44If you know what your limits are, what your ranges are, if you know, in fact, where your risk tolerance lies and what your greatest out-of-pocket loss may be, risk could be averted to a degree or at least lessened.
14:04Then we got Benjamin Graham saying, buy not on optimism but on arithmetic. tick. Talking about, in a way, of course, the greatest value investor of all time, right? Wrote the book on it, Value Investing, Understanding the Fundamentals and Not Necessarily the Momo. Now, we would have some kickback on this from our momentum traders, right? We have plenty of those that have been on the show over the years. The idea that you want to, you know, get on that train and ride it for as long as you can. Get off when things aren't looking good. Plenty of people I've talked to over the years that have this advice for you.
14:43But what we're talking about here is looking at the arithmetic, looking at the underlying, picking up the hood, checking out the engine, seeing if that car is sound, and then making a decision to buy it, not just seeing it in the street that it's all pretty, looking good, and everybody's swarming around it. Maybe the engine is dead.
15:04And by the way, that comment that I made about the time to buy is when there's blood in the streets is actually been associated with Baron Rothschild. Now there's another one. Formal education will make you a living, but self-education will make you a fortune. Jim Rohn. Self-education, that's what we're doing here. That's what we're doing on this podcast each and every week. We're getting disciplined. We're learning. We're learning from the best investors that are out there. We're talking it through. We're understanding it. We're making commitments. We're then acting upon them and then staying in the course.
15:39keep educating yourself at all times. Sometimes the best is a self-education. And a self-education sometimes may mean making mistakes. Sometimes the best education is a mistake that you won't do again. Something to think about and I think something to live by. So what else do we got here?
16:08Phil Fisher. The stock market is filled with individuals who know the price of everything but the value of nothing. Think about that. They know the price of everything but the value of nothing. Back to what we'd say that we'd have some of the greatest value players out there, right? Some of the players that look at that like a Benjamin Graham, looking at understanding what the value actually is. And then you have things like what the great late John Bogle from Vanguard would talk about. Time is your friend. Impulse is your enemy. So there's a lot of themes that are building upon each other here.
16:46The idea that impulse or the shiny car, the new shiny penny, the momentum play, you know, what's happening here and now versus time in the market, not timing the market. Underlying fundamentals matter. The economic backdrop matters. Not always. There are times it doesn't. And it seems like over the last number of years, with the Fed intervening on a regular basis and stimulus coming out of every single area of the government, that it doesn't really matter as much. When CapEx from these companies is so exorbitant that nobody cares about any of the other things that are going on. But you know what?
17:27You talk about understanding what you have and understanding what you want and understanding the stock that's out there. Peter Lynch would say behind every stock is a company and find out what it's doing. These are the people who talked about, you know, buy what you know. Think about all the things that you know and sometimes take a moment. I'll give you a little advice here, something I want you to think about. Sometimes you don't think about what you know that could be a really great opportunity. If you loved early days Starbucks or you say maybe you were the first with an Apple iPhone or maybe you think about, well, you know what?
18:04I'm changing over to, you know, DirecTV from Comcast or whatever's going on. And think about the things that maybe aren't so obvious as opportunities. There's something. Think about how maybe, you know, you prefer Uber over Lyft and maybe a lot of people are talking about that. So there's a lot of different ways to get to the same place And sometimes in investing, what is comfortable is rarely profitable Rob or not He talked about that, Robert or not He said, you know, maybe it's not the most comfortable being in something But it is going to be possibly, the opposite would be, more profitable And that really deals with the risk and standard deviation and risk return profile.
18:56But these are the things that we look at when we talk about our money. Because money is a terrible master, but an excellent servant, P.T. Barnum. And I think when we sum all this up, it's all about risk. Warren Buffett talks about that. Warren Buffett talks about the stock market as the device for transferring money from the impatient to the patient. Again, time in. Like we talked about John Bogle, time is your friend. Talk about the idea of maybe self-educating and also at the same time looking at the value of something or looking at what the company does like Peter Lynch, find out what the stock is doing.
19:47or Warren Buffett. Risk comes from not knowing what you're doing but understanding more about what there is. So all these things, I think, come together in a really nice, tidy type of way of thinking of things by the greats. And I think these are things that we could really utilize in our best efforts to make sure that we are doing what we can to become and stay disciplined investors. Now, before we get to our guest, Robbie Miles, this is an interview, by the way, that we did about, I guess, about a month and a half ago. And it's been something that we've been trying to get on because we've had so many guests and we were backed up and we had some that were scheduled.
20:35And this is really interesting. You're going to love it because some of the things he talked about are actually coming not only true, But I mean, wait till you hear some of the things he's talking about. Pretty cool. And the rationale of where it's going. So I'm going to keep you in suspense of that. I think it's going to be really interesting. But I want to talk about interactive brokers. Because investing is seeing the bigger picture. But sometimes the connections between all aren't so obvious. We talked about that a minute ago. That's why interactive brokers created connections. With connections, you can explore related stocks and ETFs, futures, options, and even forecast contracts all in one place.
21:17Discover trends, compare companies, and uncover the opportunities that are there across 160 global markets. You know, the best informed investors choose Interactive Brokers. Interactive Brokers is a member of SIPC. The risk of loss in online trading of stock options and futures can be substantial. Learn more about all of this at ibkr.com slash connections. Now, I'm going to tee this up a little bit. Robbie Miles, he was a portfolio manager for many years. He's now the CEO of Live and Let Live. We'll talk about that and have him explain about that because it's about a big picture. But also we get into a discussion, and I ask a lot of questions, and I have a lot of things on the docket to talk about with regard to where things are going, whether it's about technology, whether it's about bonds, whether it's about more broadly.
22:06And I have to ask about the whole sustainable issue, the ESG, because that's something that he was very much involved with for a while. So let's get right to it. And our guest today is Robbie Miles. And, well, instead of me doing the introduction today, I thought I would let him do it since he's at a new position. Robbie, how are you? All the way from Hawaii. Hey, Andrew. Yeah, I don't sound like it, but I am in Hawaii. Yeah. Yeah, it's great to be on again. We could have the Tiny Bubbles music Don Ho play in the background. Tell me now, I know you have left your position. You used to be with Allianz, and you were in charge of the sustainable portfolios there.
22:45You're now a CEO at a nonprofit called Live and Let Live. Tell me about that. Yeah, Live and Let Live is a reconciliatory force in the world. I was invited to run it by the guy who founded it, Mark Victor, and it was the biggest compliment anyone's ever paid me. I so believe in this mission to reconcile the differences of a very polarized society around one thing. Well, I guess two things. One thing being don't aggress. No one wants to be a victim of a crime. So let's agree on that. And then the other is let's treat each other well, but not because we're forced to, but because it's the right thing to do.
23:22And that is a universal philosophy that's featured in every religion. It's the golden rule. And we've codified that first part, don't aggress, quite carefully to say which bits are clearly an aggression and which bits are clearly unclear. You know, many issues in the law are continuum problems. So we shouldn't fight about an absolute right answer, but just recognize that reasonable minds disagree. that's the path to peace. We need to tolerate differences if we're going to co-inhabit a peaceful world. And I think we need to co-inhabit a peaceful world because the world is getting more complex. It's the complexity stacking on itself.
24:06And there are some big kind of scary challenges. I'm generally an optimist. I think we'll face these challenges as well. But we can't ignore that there is a global aspect to our community now. Someone can cause a risk in a faraway country that affects us, even if we have a totally different set of rules over here. So we need to think about reconciling globally around something that is universally simple, like don't aggress. Okay, I got that. That's a big, that's big. That's all encompassing. What are the crimes? What are the things? What are the areas that you would be folk? Give me example of something.
24:45Yeah, so a good example of something, if I was to smoke a joint, put some marijuana in my body, that might be bad for me. We might even agree that's immoral. It might be a bad use of my brain, but there's no victim. I am doing that to myself. So to lock me in jail for that would be an initiation of aggression. So it's the people that lock up people for victimless crimes that are initiating the aggression. So we need to stop doing that. We need to stop punishing people where there are no victims. And there are hundreds of these examples. Another good example might be if Bob and Bill want to contract to work for each other, and Bob offers Bill$10 an hour, and Bill's happy to pay that, but that$10 an hour is below the minimum wage threshold.
25:32If a third party comes in to punish those people, it's the third party that's aggressing, not Bob and Bill. So both these, by the way, sound like less government to me, those two examples. Yeah. So this is where a lot of us did have some sort of a libertarian background, but we're really different to libertarians in a few ways. One of them is that libertarians are orientated to freedom and we're orientated to peace. So the freedom part is the don't aggress, but we voluntarily add be an excellent human or kind of be decent to each other, because it's really important. If we're going to get rid of the social welfare system because it's based on coercion, what are we going to replace it with?
26:17Are we going to replace it with independent people, silos with, you know, armed fences saying, don't tread on me? Or are we going to replace it with voluntary kindness? We're pretty clear that it has to be the latter if this is ever going to be appealing to people. So in some ways, what our main focus is, is creating a community of people that are demonstrating this voluntary kindness, elevating each other, enjoying each other's friendship. And again, this is big. It seems almost too large for me to consume right now, so I'm going to try to continue breaking this down a little bit. It doesn't necessarily revolve around a particular item, social or country or socioeconomic.
27:04It sounds like it's item for item You know, what things can we do to make I mean, the old world a better place Obviously, that's something big You know, but is there a particular Is there something that you pick up on That you are currently working on? And then who does the financing? This is a charitable organization I'm assuming you have a portfolio that you run there too to keep the charitable funds active so there's more in the future, right? So let's start with the first question is, what particular item are you focused in on now? And then we can talk about areas that, how the operation works.
27:45You're definitely right to identify that this is a huge mission. Our motto is aim high, fall short, do well. So the goal is world peace and we'll fall short of that. But if we can move the world to a more free, prosperous and peaceful place, then we've done our job, even if it's slightly incremental. Our focus at the moment is identifying those areas that reasonable minds disagree on. And those are going to be topics that we're not going to concede that our position is wrong. There are many, many hot button issues in the US right now. For example, I'm kind of hesitant to talk about it because it's so divisive, but abortion, there are extremely strong views on either side about the right of choice for the mother and the protection of the life of the baby.
Read the full transcript
28:40And it's going to be pretty unlikely that either side ever reaches agreement with the other person. The person who is pro-life is never going to be pro-choice. The question is, can we tolerate each other's views? because if we can't tolerate each other's views, then we have what we have today, which is an endless cycle of lawfare where the red party comes in and imposes their morality on the blue party who then come in and do the same. And we're stuck in this cycle forever and the law gets ever more complex. But aren't we stuck in a cycle and you would have to break the back of religion. I'm not talking about just abortion because my God is better than your God has been a fighting point since when?
29:21Since ever, right? Isn't that always been the case? My team's better than your team. We gather around. And that has to do with the same thing with all sorts of things. It doesn't have to be just religion. It can be a lot of different fundamental values. And people get, they feel good holding on to certain things and threatened by people that have an opposing view. Totally, yeah. And so we need to recognize that that threat can be solved by letting local communities decide. So if one is, again, if one is pro-life, one can live in a pro-life community and everyone around that community can agree that pro-life is the right answer.
30:05They don't have to even concede that they might be wrong on that, but they have to tolerate. they have to recognize that other people do disagree and and tolerate that tolerate their views if we're going to stop the end of cycle of warfare and i reckon i take that as a good trade because if we don't do that it's not like everyone's going to be pro-life anyway you know it's not like it's not like you're by by kind of entrenching ourselves in our righteous positions we're going to actually solve anything but we can continue chipping away and trying to change minds But on the religion thing, I think at the heart of every religion is love.
30:42And in Christianity, it's love thy neighbor as thyself. But that kind of golden rule does feature in all the major religions. So if we can recognize that common thread of religion, then we don't have to decide which one is right. Again, I could be a Sikh and be devout Sikh and never be convinced by Taoism. But the same with the Taoist can be all in on Taoism. But as long as we can agree not to aggress against each other, then we can co-inhabit the world peacefully. And that's really the key. And there are nine forms of aggressing, which probably is too much detail. But if anyone's interested, www.3l.org has a bit more information.
31:25And then on the investing side, luckily, we've got a very generous founder, Mark Victor, who's currently donating enough for me to work full time on it. And I'm trying to avoid the temptation of getting too sucked into markets because I'm totally addicted to looking at markets and I love it. But as you say, it's a big project I'm working on now, and I'm trying to focus on the big project. So are you managing the portfolio for the charity at all or just your own stuff these days? Just my own stuff. And what I'm trying to do is demonstrate these community values by basically just sharing my trades on our membership platform for free.
32:06So that it's basically like, you know, many, many people offer a newsletter. I'm just offering mine for free. All right. But you're still in the thick of things there. You're still, I mean, you're working like everybody else does, but you're still in things with, you know, producing information and doing the research in the areas that you need to, to make appropriate decision making on a trade or not a trade or a sector. You're following things closely. Yeah, I mean, I was very, I was all in. I mean, I had a huge imposter syndrome as a portfolio manager. So I worked extremely hard and that only finished in June.
32:44And so naturally, there's an afterglow of insight that I'm making the most of. But I would guess that that slightly dims over time as I focus more on the project of telling the story of why I live and let live. And then you hire people like me to manage your money. So anyway, but let's talk about some of the things that you did observe recently with regard to markets. because you wrote me an email. We talked about a variety of things. And you have been a reluctant bull, which I, by the way, I don't think you're alone there. I think that most people out there are, I don't care if you're professional or you're an amateur or you're just following along.
33:28People have the sense that, you know, I'll go along with this because you can't go against this trend. It's so strong. But at the same time, I may not like it. We've seen this before in many different areas. The most hated bull market in the world was like back in 2000, it was called 10, 2011. I mean, it was like, no, this can't be the case. It can't be coming back. Same thing with the post-COVID. But what did you see differently this time? I always break it down into different fractal layers. And the biggest fractal layer, the kind of long, the mega history is always one of the improvements. So to be bearish is really to not understand, to be bearish permanently is to not understand the trajectory of history.
34:15Things do seem to get better. And then the one level down from that is almost like, I would call it like the tide, which way is the tide going? And there I'm a bit more cautious. The tide seems to be indicating that we have some structural problems, some structural addiction to money printing. And right now, that addiction is kind of helping risk assets as liquidity improves. The US dollar has been weak, helping liquidity. And interest rates have not been so high that they are debilitating. So it's in some ways a bit of a Goldilocks period now where the Austrian economists see it as a crack up boom.
35:01But I would say that right now, some of the indicators point more towards a disinflation rather than inflation increasing or even staying stable at these higher levels. May I interrupt? Is that focused on the US or is it the world? Where are we talking? I'm usually focused on the US. Okay, gotcha. I think they kind of lead the world. So in the US, the housing market seems like it might be showing some size of stagnation. And then wages, particularly in service areas, have been increasing, but at a decreasing rate. And then the third pillar of what causes inflation would be the underlying commodities.
35:46And the oil price at$64 is not particularly inflationary. That's a decline year over year. So I would say that all of that's pointing towards a slowing down of inflation, which could give way to disinflation. Deflation is a big, big word, so I'm not going to go that far. But generally, I would say that I observe this kind of reflation narrative to be very strong right now. And I think that's also underpinned by huge optimism in AI. and I share the belief in some of those long-term promises of what AI might bring to the world. But I then layer on this basically behavioral analysis. And to me, it seems that the bullishness is a little bit over its skis.
36:34And if we do start to see this disinflation, then I think actually bonds would be a more attractive place to be than equities, even though long-term, I think there could be some irony in calling it the risk-free rate and treasuries. I'm going to switch this up for a second. I'm going to do a hard right turn here. I am going to do a, from where we are and where the markets look right now, because I want to come back to that in a minute, but I want to do a post-mortem of you running money at a major firm. Can we do that for a second? I'd love to, yeah. So you were running, when we first met, you were running, well, first it was, my concept was ESG-ish, right?
37:16That conceptually of ESG-based analysis, research, pool of assets. But you're also, it was more sustainability, right? Which I don't know if there's a difference in that much, but can we take me back to some of the research you were doing back then? Because that was very hot for a while because people were like, well, okay, this is a great little tool to use. And by the way, the way I got to you, let me just give this one more point. I attended years and years and years ago, I think, I don't even know, it was years before it became popular, a luncheon that I was invited to because I was kind of intrigued with this whole ESG thing.
37:56I was like, what is this about? I need to understand it better. and was invited to this portfolio managers and I had lunch and we talked about, you know, the idea of using an ESG-based process because the research has shown that ESG companies that do environment and social and governance and all this other stuff, they have better ways of, they're a better run company essentially, right? They have better values. And in the end, the stocks do better. That was the concept initially. And I was like, okay. But then I found out that a lot of these companies were developing these ESG indices and then selling them.
38:37And then it was kind of being fed on by the people that were investing in the ETFs, the indices, the passive investors. And then it kind of blew up a little bit with like, is this really, this is just crap. I mean, that's what a lot of people ended up saying about a lot of this. All right. I'm going to throw that all back to you. Give me some thoughts on all that. Yeah. Yeah, Andrew, I feel so grateful for the last 11 years of working in investment management, because to me, it's like being in the crow's nest of the global economy. And you're looking out over all the things that matter to people's lives, and they just show up as numbers on a screen.
39:15But to try and form internal imagery that brings together all those numbers and paints a scene of where we're at and how to allocate capital accordingly has been such a joy. But I would say that the sustainable investing story or theme has been bumpy. When I first started out, I was very much bought into this idea that if you increase your awareness of pretty much any topic, you're likely to have more useful inputs that improve your ability to respond appropriately. And sustainable investing really means looking at issues that don't show up so clearly on a profit and loss or a balance sheet. Things like employee satisfaction.
40:03I find things like glass door reviews really useful, both as a stock picker and as a consumer of products in the market. If there's a company with miserable employees, I'm kind of minded to expect a miserable service and similarly a miserable stock price. There's a company called Equibridge, which is looking at the reputation of businesses in the minds of the customers that use them. I think those kind of data points, again, they don't show up on a profit and loss, but that's extremely valuable. So I always like those alternative inputs to broaden out a holistic investment case. But I think where sustainable investing has gone wrong is the myth that morality shapes your stock price performance.
40:56It's somewhat true sometimes. But if I say that I don't like fossil fuels and therefore I exclude them from my portfolio and I think my portfolio is going to go up, there's some errors there in the logical thinking. because just because you don't like fossil fuels doesn't mean people aren't going to use them. I mean, the UK at the moment isn't using any of its own fossil fuels or very little, and it's importing fossil fuels from basically enemies. I mean, it's totally ridiculous. And it's all stemming from this idea that fossil fuels are evil. But somehow, if we just ignore them or get them from other people and rather than get them ourselves, that should solve the problem.
41:40And it's kind of like a child putting their hands in front of their face and now assuming that no one can see them. Yeah, their hand in their ears and say, la, la, la, la, la, I don't hear anything, right? So, but the thing that's the funniest part of it is that the manipulation of the process, so therefore you have these certain scores, let's call it, that went into the input to figure out if this company gets a nine ESG score, right? You follow me? And so what do you do? Well, we're polluters. But we're buying carbon credits, so we net that out. It's like, wait, but you're still polluting, right?
42:16This whole idea of, I guess it's called greenwashing. That's what they called it in the end because I questioned this from the beginning. I'm like, I don't understand. You have all these things going on in the company. They know what it takes to get into that index. They're smarter than all these other people. They'll figure out a way to financially engineer, engineer, buy carbon credits, do something to offset, somehow to make it look like so they can fit themselves in, in order to get themselves in there so they can ride the wave. That's what happened in the end, didn't it? Yeah. And also, I think this is a great allegory in general of why regulations tend to bolt the gate after the horse has left, or shut the gate after the horse has bolted.
43:00Because early on, again, we had this recognition that more awareness of more inputs should eventually pass through, should lead to better results. But of course, then other copycats jumped on the bandwagon and said, oh, we're sustainable too. Just like, you know, I'm Brian too from Life of Brian. Everyone was sustainable suddenly. And actually, of course, they weren't. They were just chasing the gravy. And so the regulator then comes in and says, okay, there's clearly people who are being disingenuous with this stuff. So we're going to mandate what it means to be sustainable investing. and of course they've just been focusing on some other random policy in healthcare or education and suddenly they're now all knowledgeable on sustainable investing except of course they're not and now the whole industry, the innovators and the laggards are all required to focus on the regulators' way of doing sustainable investing and that's where it got really ridiculous like we found one of the most sustainable turbine companies in the world people are going to use turbines, even if you don't like fossil fuels.
44:03And we weren't allowed to invest in them, even though that was directly channeling capital to companies that were really pushing forward human efficiency. And there were many examples of really great sustainable companies that we could no longer invest in because of very arbitrary, broad brush policies that we had to comply with to basically stay out of being fined or worse. And that's where The industry got very unappealing. Not to mention what it actually costs companies. I have people that I know that are in management of publicly and private, but publicly traded companies. They had to put in so many strange human relations, HR, people-related oversight, and certain people of various backgrounds into the firm, whether they liked it or not, certain amount of women, certain amount of men, certain amount of people of color, certain people.
45:03It was absurd. And the management of that, because those people who came to the firm as a required part of the inclusion into the various sustainability indices, they knew it. and basically took advantage of it. So I think actually in the end, this is my thought. You may disagree. I'm not saying it was a good thing. This is not a good thing. So just bear with me. I think it actually cost companies more money than it was really thought to in the beginning because companies ended up backing into it rather than just getting what it was. In order to, as we said. And in the end, I think that everybody realized this, and I don't know where that is, and there's probably people.
45:52Look, there's no vice funds out there. There are funds that say, you know what, you can't have Rick's Cabaret. You can't have alcohol, tobacco, marijuana stocks. There's funds that do that, and maybe they're successful, right? It's possible. I'm not saying they're not. But as an investor, Robbie, do you think now that we should limit? Would you limit yourself today? Today, would you limit yourself to not buying that turbine company? Absolutely not. No, I never wanted to limit myself. I was always spending, I mean, even myself as an investor, I felt a real obligation to my clients to deliver great performance.
46:34You know, these were pension funds, people that really depended on that money for a good retirement. I took it very seriously. and to not be able to buy companies that I thought were going to go up and then watch them go up that would have been like, you know, some of these companies, my process was always trying to buy companies that were great for the investor and great for society. And the great for society one was just a very simple investment thesis that if it is great for society, people are going to demand it more. Well, of course, right, right. And so you have this positive feedback loop.
47:10but in general the big problem with all of this stuff is trying to solve morality via the stock market it doesn't work like that if something is backwards yeah if something is again if something is aggressing we need to stop it via the law and this is where you know allocating capital in the stock market is not going to stop pollution but laws that stop pollution would so that's why i think sustainable investing has become worse than useless because it gives a false sense of security that these problems are being solved where they're absolutely not right and it was bastardized in the name of making money that's what it was in the end it was all about making money like these companies are better because you'll make more money with them it wasn't because oh you want to be with these companies because they're actually good companies because they're terribly inclined they're good to their employees that you know this whole laundry list of of real real things that may have been the things that were the original thesis behind all that.
48:07So, all right, we beat that to death, but I'm glad we talked about that. Talk about the process. How do you find a company that is good for society? I had a, yeah, I had a framework that I was really proud of that basically saw energy as the foundation of all economic activity. So everything in the economy is energy transformed. So that process is three parts. You take the energy from the environment in some way, it could be solar panels, wind turbines, nuclear, whatever. And then you convert the energy into some sort of a useful thing via basically industrials and all those kinds of companies.
48:50And then you have all the consumer facing companies that is using that converted energy into some product that people want. It could be healthcare, it could be food, food, water, that kind of stuff. So seeing it as this life cycle, I then found 40 themes that matched onto those three general areas and tried to think about what was enhancing the energy efficiency, like the least amount of energy wasted between the harnessing and the use of that energy and maximized the benefit to the end consumer. And that was really helpful in identifying which companies were creating positive change. So I want to talk about some of the things you sent me.
49:36And in particular, you said this. I'm going to quote you. It says, investing is properly about fundamentals. Investing without fundamental analysis is like getting Jack GBT to write your essay for you. It's possible, but there's no substitute long term for understanding how businesses work within their ecosystems. So let's break that down. Okay. Fundamentals, one of the most important parts in your opinion of finding a company that will have long-term profitability. Is that a true statement? Yeah. So generally, I was an investor that didn't like to identify as one particular type. So just I'll definitely answer your question.
50:13But in some ways, this focus on fundamentals is like the Ben Graham approach. It's a combination of the Ben Graham approach and the Silicon Valley approach. It's like the value and the growth investor. And then trying to find companies that meet that. What I synthesize it as, and many people do, quality growth at reasonable price was always what I was trying to find. GARP. Yeah, so I'll go into that. So quality, it does include things like the governance. you know is the is the agency risk between the management and the shareholders well checked by a chairman and a board who are actively trying to get the most out of that management team but it also includes things like the historic returns and margins again i talked about equity the the employee and customer satisfaction and the overall competitive competitive advantage the portus by forces all that stuff and then the the growth is the second component of the fundamentals.
51:10And then it's basically an extrapolation of historic trends. And, and again, whether it solves society's problems, which is why I had that 40 theme thematic lens. And then the final bit, the reasonable price. This is much more art than science. And this is where I think you have to have a macro framework, a lot of the a lot of the people I used to work with, didn't like thinking about macro, because it's very difficult. And they thought it was a waste of time. But from my perspective, it's really important, even if you get it wrong, to try and figure out the macro backdrop. Because otherwise, what context is there for the valuations you're paying?
51:48Is 30 times PE for NVIDIA expensive or cheap? Well, it kind of sounds expensive, but then you compare it to everything else and the time we're in. And if you have that view, you would have - And their growth, and their growth potential. Exactly, yeah. So looking at the context to the growth, the peg. Let me bring you back peg. I love a peg ratio, by the way. People, if you haven't looked at peg ratio as a tool, because on TV, on the radio, everywhere you hear about, well, it has a 30 PE ratio, which is a little bit higher than its peers. Which, by the way, means, Robbie, back me on this, means nothing.
52:23True. Zero. Yeah. You know, you talk about, somebody talks about a bank. Oh, the bank's got an eight. I'm like, we don't look at banks with PE ratios. We look at maybe price to books or something of that nature, but there's other things. Anyway, the PEG ratio, which is price earnings to growth, if actually – NVIDIA just has a number. It doesn't matter the number as an example. 30 times forward PE, but yet it has a 40 % growth rate over the next five years. That's the estimate. It actually is below one when you do the division, growth versus the PE. And it actually makes – it's cheap. So anything under one is – well, one is fairly valued, right?
53:05Below one is undervalued, theoretically, and overvalued is over one. Yeah, the third thing you have to factor in is the quality. So something like Costco always looks ridiculous on a peg. It's got like a peg of six or something. A peg of six you would just not touch with a barge pole. But then, again, you would have historically been wrong to not touch it because people just love Costco, and they're very willing to keep coming back to that company, and it's a safe haven in a recession. um so so sometimes people i mean i'm not willing to pay six peg for a costco but some people are and you know they've probably got it more right than me but i would generally say a peg below two is interesting a peg below one is compelling um and and then the quality has to be layered on on top let's go back to this governance issue so you mentioned something it was really interesting and just flashed not only flash it like it it it was a bang right to my head you talked about you know is the chairman and the CEO, are they aligned?
54:02Are they doing the right thing for the company? So back when we're looking at things like that as a top level, one of the areas that we look at for sustainable investing, good investment opportunities, long-term good for society, Tesla, they can't pass that. Yeah, Tesla's one of those things. So there's, annoyingly with fundamentals, there's usually a rule to prove the rule is not valid and it will occur. There's usually an exception to every rule. The Silicon Valley approach to stewardship, the Stanford University approach to stewardship is much more about empowering the CEO. And I sympathize with that.
54:40If you have a visionary CEO, you don't really want checks and balances to slow them down. You want them to be visionary and act on it. And Tesla is one of those companies with terrible corporate governance. But it's one of those companies that's going to work until it doesn't. And when it doesn't, you look into the share pledging that Elon Musk has done, which can be very recursive on the way down. If the share price goes down such that Elon Musk has to sell his shares that he's using as collateral for loans, then that would put exacerbated pressure on the downward selling. And we haven't seen that play out.
55:18He hasn't let that happen. He makes sure that shares are propped up all the time somehow. Right. Yeah. So, you know, we never invested in Tesla, but I always respected the company. And it clearly was wrong not to invest. It was one of the best companies. We got some other good ones. We played NVIDIA better. But the corporate governance was basically the reason that I did find it a bit difficult. Because he just has so many friends on the board. And that's nice. Again, it's great. You're putting that very politely. Friends, yes. His brother. His brother. He's got a brother and everybody else who just would do what he wants.
55:53Why not? They make plenty of money by doing so. I wonder what actually a, I got to look this up, what a Tesla board member makes per year. I mean, is it 500, you think? Yeah, look that up. I've got no idea. It's got to be a lot of money and something you don't want to give up. Let's kind of just sashay over to the area of macro. So one of the things about macro is for a long time, many years ago, many, many years ago, I was under the impression, assumption, belief that macro led. Macro led. Economic conditions were such that we have to really put them into my calculus when it comes to, do I want to buy the stock or stocks or the market or whatever?
56:42This is how I'm going to create my portfolios, my asset allocation, my positioning in equities, bonds, real estate, whatever. Lately since, when I say lately, since 2010, there seems to be less of a reason to do so because the amount of money that's being pumped into not only the United States, but countries around the world is such that it's masked the problems with macro. How do we reconcile that today and utilize that? or should we just throw it away and not even deal with it anymore when it comes to our thinking? I think we have to incorporate that liquidity pumping into the macro as probably the most important macro component.
57:29So I agree with you that macro leads. I would say, if anything, what leads macro is sentiment. And we are a herd animal. And this is where I find technicals very helpful. Because if you look in the wild, a herd of gazelle, the time when they're most relaxed is when the lion is in the grass, eyes fixed on the weakling and ready to pounce and they just haven't seen it. Then they peak relaxed. The time when they're most stressed out is actually when the lion is least dangerous. The teeth are already into the weakling and they're not chasing anyone else. But the rest of the herd is still terrified.
58:08if you can start to be able to predict whether the herd the human herd is generally complacent or fearful that i think is the most important thing to to get a sense of which is why i like elliot waves and you can i don't know whether there's any science to this but i see elliot waves in in macro indicators i see it in in even like liquidity charts like global liquidity um so that's that's like an open-minded approach that may be completely debunkable but um that that's that's the way i i looked at macros just synthesizing all these things again more is more was was my approach rather than kind of less is more yeah i mean because there seems no end in sight by the way and the the idea of having debt i remember when we had uh greece and the pigs, right, with, what was it, over 100 % of GDP to debt, debt to GDP, I should say.
59:05And it was like, ha, ha, ha, ha, look at those guys. They suck. I've never invested money over there. And now where are we, right, here in the United States and around the world? It's interesting because Japan is now starting to back off. They actually talked about increasing interest rates once again. And the Bank of Japan just not too long ago talked about how they're going to stop, or not stop, not stopping, the slowing, the purchase of ETFs and reach in the market. So that's something of interest there. But the world has become addicted on this idea of excessive amount of stimulus. In fact, company upon company upon company are doing it on their own these days.
59:44The concept of circular and vendor financing. So how great would it be, Robbie, if you and I, you're in business, and I give, well, we are, right? So I give money to live and let live and you give it back to me in the form of payment for advertising, let's just say or whatever, okay? No, better yet, I give you a million dollars, okay? You give me back$250 ,000 a year for the next four years and I take the money off of my books and I put it as income. It looks good for the world and then my stock price goes up. Not a bad deal, right? It's a good deal. It reminds me a bit of NVIDIA and OpenAI. Yeah, Microsoft and all the other companies that they put on to go onto the Azure.
1:00:35And then Microsoft and, I mean, Google and companies out there too. This is kind of what's going on. It's like, I explained it on a show recently. I said something like, it's like eating your own arm and thinking it has nutritional value. Which it does. You know what I mean? After a while, it's not going to work out so well. Yeah. So I don't know what your stance is on that, but that's something that's interesting what's going on in the world. And that probably would have been identified under one of your criteria. It should be when it comes to quality of earnings, right? Yeah, exactly. That's where I would say that there's no substitute to understanding the business model.
1:01:17And there are those that go super deep on each company. And sometimes they can kind of pat themselves on the back for that. But then there's all the companies they didn't look at. So it's either quality or quantity or some combination of the two. I preferred a slightly shallower deep dive than some of my real deep diving peers so that I could look at more companies and try and triangulate the truth. So the quality is really a never-ending thing. But just on your point with Japan, I think because of politicians not wanting to lose elections, there is a real aversion to recessions. But recessions do play a role.
1:01:56They clear out the dead, the inefficient companies, and then the fresher companies that are more resilient, more useful, thrive and come through. And if we are not going to, if we're going to just prevent winter from ever coming and just keep pumping all this money, we'll eventually reach some intractable problems. The thing I worry about long term is actually when the commodity leg of the inflation stool does really start booming. And we've seen gold and silver pointing to that maybe happening. But at some point, I predict oil and gas will be at least double, maybe treble what it is now. So if it's 65 now, I could see it well over$150 a barrel because not immediately.
1:02:45and I wouldn't be surprised if it went lower first, but at some point, there is a finite supply of oil and gas. And as much as we wish we were moving away from it, we don't really have substitutes for things like air travel or plastics, not cost efficiently. So that's when the central banks in Japan and the rest of the world, they may want to raise interest rates. They may want us to do more quantitative tightening, but I don't see a way for them to long-term, which makes me very bearish on government bonds long-term and more bullish on things like gold and silver. Yeah, good stuff. Well, all the way from Hawaii, Robbie Miles from Live and Let Live.
1:03:27I like to say mahalo, Robbie. Mahalo. Now you live in there now, by the way? No, I'm living in Palo Alto. Oh, all right. Just a stone throw away. But coming to us today from Hawaii. That's great. That's good stuff. You know, we'll have all the information on Live and Let Live over on the episode. for this episode over on thedisciplineinvestor.com. Robbie, thanks for coming aboard. Appreciate it. Thanks so much, Andrew. Always a pleasure. Thanks. That was prescient. I mean, that was some great stuff right there, talking about not only the markets, but again, going back and looking at the ESG and all that.
1:03:58Thanks for joining me this week. Next week is going to be, I think, the last episode of 2025. The last episode of 2025. So that's something that we need to look at and say, wow, it's been an unbelievable year of great guests and great discussion. So we are going to end it. I'm going to tease you a little bit with one of the greats, one of the greats coming on next week, talking about the world of investing that also analyzes the greats on his own. Some of the most famous people he's been involved in. So we're going to tease it up for next week. Thanks for joining me this week and every week. I'll see you again real soon.
1:04:45This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz and Company Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements.
1:05:23Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement. Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliate support.
1:06:13We'll be right back.
From the publisher
The walls are coming down – the house of cards exposed.
We have economic data – late but we got it.
And that concludes the last full week of trading for 2025!
And our guest – Robbie Miles, CEO of Live and Let Live
NEW! DOWNLOAD THIS EPISODE’S AI GENERATED SHOW NOTES (Guest Segment)
Robbie Miles is the CEO of Live and Let Live – Live and Let Live is a global movement committed to building a freer, more peaceful world. As part of the Live and Let Live community, you’re surrounded by individuals who share a passion for personal responsibility, non-aggression, and being good humans.
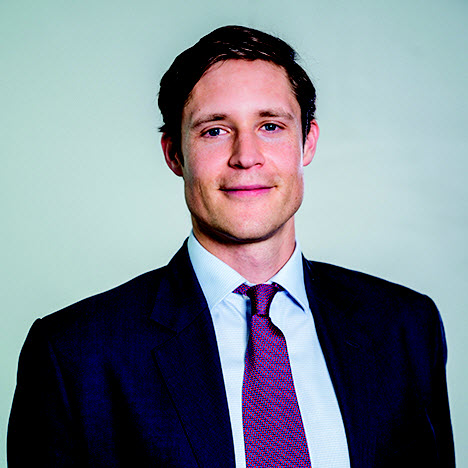
Here, we connect, collaborate, and grow together — exchanging ideas, supporting one another, and taking action that aligns with our shared values of peace, freedom, and human flourishing. Whether you’re here to learn, contribute, or lead, there’s a place for you in this movement.
Check this out and find out more at: http://www.interactivebrokers.com/
Stocks mentioned in this episode: (SLV), (GLD), (ORCL)