
In short
The Disciplined Investor Podcast - Episode #942: Modern Disciplines
Episode Overview In this episode of The Disciplined Investor, host Andrew Horowitz discusses several pressing economic topics including government shutdowns, market bubbles, and healthcare sector developments. The guest for this episode is Tom Nelson, Senior Vice President and Head of Asset Allocation at Franklin Templeton Funds.
Key Topics Discussed
- Government Shutdown
- Discussion around the impact of a government shutdown and uncertainty regarding its duration.
- Market Bubble Concerns
- Examination of current market conditions compared to historical bubbles, particularly the tech bubble of 1999-2000.
- Consideration of valuations and profitability of companies, with a note that many current companies are not profitable, similar to the bubble times.
- Healthcare Sector Boost
- Analysis of the healthcare sector's performance and its recent improvements.
- Guest Introduction: Tom Nelson
- Overview of Tom Nelson's professional background and roles at Franklin Templeton.
- His insights into market dynamics and asset allocation strategies.
In-Depth Discussions
Market Dynamics and Mechanics
- The conversation highlights market mechanics, including the consistent influx of capital into the market through 401(k) contributions.
- The importance of understanding the drivers behind market movements and the potential impacts of employment rates.
Asset Allocation Strategies
- Nelson's perspective on the current macro environment and asset allocation strategies.
- Importance of a balanced approach to investing, focusing on diversified asset allocations.
Federal Reserve Policies
- Discussion of the Federal Reserve's approach to interest rates and its impact on the economy.
- Nelson articulates concerns about predicting the future economic landscape and the Fed's historical performance in these predictions.
Valuation Concerns
- Both Horowitz and Nelson discuss how high valuations could lead to lower future returns, suggesting a return expectation of about 6.5% for a traditional 60-40 portfolio over the next decade, which is below historical averages.
Corporate Earnings and Financial Engineering
- Concerns about the quality of corporate earnings, particularly regarding stock buybacks and vendor financing practices.
- Discussion about how these practices may be distorting true corporate profitability and the implications for investors.
Global Markets and Economic Outlook
- The episode explores global economic conditions, particularly focusing on the performance of international markets versus the U.S. market.
- Nelson emphasizes a broadening growth outlook, noting that emerging markets could provide better returns compared to the relatively expensive U.S. equities.
Key Takeaways
- Government Impact: The potential impact of a government shutdown on markets and the economy.
- Market Bubbles: The need for vigilance regarding current market valuations in comparison to historical bubbles.
- Asset Allocation: Importance of a diversified investment strategy and understanding macroeconomic indicators.
- Interest Rate Predictions: Challenges associated with predicting future rate changes and economic performance.
- Earnings Quality: The significance of assessing the quality of earnings and the consequences of financial engineering on perceived corporate health.
Conclusion The episode concludes with insights into future guests who will be featured on upcoming podcasts, reinforcing the commitment to provide valuable insights for investors. Horowitz encourages listeners to remain disciplined in their investment strategies and highlights the importance of thorough analysis in navigating the complexities of the market.
For further information and resources, listeners are directed to visit [The Disciplined Investor](http://www.thedisciplinedinvestor.com).
Disclaimer This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principal.
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Transcript
Automatic transcript. May contain errors.0:00This episode of The Disciplined Investor is brought to you by Interactive Brokers. And here's a question for you. Will a Fed leave the rate unchanged at the October 29, 2025 meeting? Well, the yes forecast recently traded at 38 % and the no was at 61%. With Interactive Brokers forecast contracts, you can trade on future events like climate change, the economy, politics. You can choose yes or no. And if you're right, you get paid. It's that simple. Explore trending data, spot the trends, and make your predictions for October 2025. Trade forecast contracts and interactive brokers and earn a dollar for every correct prediction.
0:40Plus, you'll earn 3.83 % APY on your investment with an interest-like incentive coupon. And you'll get$3 when you start trading forecast contracts, which you can use for any purpose. Forecast contracts are not suitable for all investors. Go to ibkr.com slash forecast and start predicting today. The last day for trading this contract is October 29th. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast.
1:17Tom Nelson:This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz and Company, from seed through harvest, cultivating financial success.
1:35The government is shut down again, but how long this time? October, usually a bit rough, the bubble is in question, and the healthcare sector gets a needed boost. Our guest today is Tom Nelson, Senior Vice President and Head of Asset Allocation for Franklin Templeton. all this and much more on episode number 942 of the Disciplined Investor Podcast.
2:13Hey, Tanner Horowitz, how are you? And they thought it couldn't last. Well, talking about the market and the amount of movement we've seen. Who knows where it's going right now? Hi, welcome, especially to all of our new listeners, building this great community. As I mentioned, I'm Andrew Horowitz. I am host of this. I'm also author of the book entitled The Disciplined Investor. It's an audio book as well. I'm also the co-host of DH Unplugged with John C. Dvorak. We talk on Tuesdays and we have a lot of fun on that show. Let me tell you something. It is a lot of fun. We do a lot of thought discussion about most of the recent news that's out there and what it really means, how to uncover what it really says and go a little bit in a different direction than most will be going with just looking at headlines and talking about things like simple PE ratios and looking at just very, very, I would call it simplistic technical indicators.
3:12No, we go a lot further to try to understand what it really means. So if you haven't listened to DH Unplugged, I really encourage you to do so. So here we are. We're feeling good, right? I mean, markets, generally speaking, you know, but a little bump here and there and a few things going on, but, you know, they're cooperating. What can go wrong, they were saying. That's what they said. What can happen? You know, it may not happen until 27. This is a new time. We're under a new regime. The president wants the markets to go up. We have the fact the Fed is cooperating. What could happen wrong? What could mess this glory up?
3:46And don't get me wrong, there's a lot of positive drivers out there. But one thing that I've been noticing, and you got to start listening with a little bit of a different ear sometimes when you read and you start absorbing what they're saying, you start thinking about what they're saying on the radio, on TV,
4:05podcasts, there's all of a sudden this discussion that has come out, these comparisons to bubble times. In particular, we're starting to hear all this about the tech bubble of 99 to 2000 and, you know, not to worry because it took two years for it to burst. And this time's different anyway. Back then, companies weren't making money. You know, we had all these companies that were pie in the sky and hopefuls that were getting funded and they're coming out in IPOs and they got all this money to do something, but they were not profitable. And that's not the case today. Wait, what? What? Of course it's the case today.
4:46The fact of the matter is we have many companies, a lot, that are getting funding. Maybe they're not the crazy peep out web band and the names that we heard back then, but there's a lot of different names and very similar circumstances. There will be winners and losers. And look, while the investing is hot, why not take advantage of it? There's several companies that we've had in our portfolios for our clients that are not money winners, makers, but money winners, right? The stock winners. Hundreds and hundreds of percent they're moving without the prospect of any near-term revenue or profitability.
5:25Either one. But they have something. So what about these quantum companies, these AI companies? Remember, OpenAI is scheduled to lose, what are they telling us, tens of billions of dollars a year? But what they're doing is they're pledging hundreds of billions to fund other companies and these partnerships. And we're looking at all this with two pairs of glasses right now. I think you have to look at it with two pairs of glasses is because if you look at it with just one, that being fundamentals, you would not be having a party right now. If you did it with just technical, maybe you would have gotten into some of these.
6:08They've been extra extended, so you may have been out, but yet it will hopefully get you to a place where you can get in earlier than you would if in fact some of these things play out. Stay in until something goes wrong. Wondering how these valuations are being held up and then saying, well, I'm not investing in that. You missed Netflix if you did that, right? You missed, how many other companies could we mention right now, actually, if you wanted to, about Amazon? You missed Amazon for years. You missed it. And the list goes on. Palantir. You missed, I mean, I could probably just sit here all day and start thinking about company after company that you missed if you were just looking at fundamentals.
6:50And there's nothing wrong with doing fundamental analysis. I think for what we've built for our clients, a combination, you know, the quanta, funda, techna, where we look at filtering system to find stocks and meet certain criteria, but then also look at fundamentals, but also look at technicals. And then have a sidebar of let's just look at technicals for just certain opportunistic investments. Utilizing all three at a time in totality or individually is probably the better way to skin this cat, so to speak. And remember something. Many people are sitting firmly between both camps, between the idea of the valuation is too hot, but yet the technicals are good.
7:37And that creates a lot of churning. And in a sense, a higher trend as the market mechanics are still at work. We talked about this idea of market mechanics at length a few years ago. I'll just remind you of it. Because maybe it would be like, uh-huh, you know, now I remember that. And if you didn't hear about this before, you should listen. It's very simple. Why do markets continually move higher? Why is it when you look for the chart over many, many years of time, they go from bottom left to top right? What is this, what is it that people, well, first of all, it's a great money-making machine.
8:10No question about that. Companies learn to adapt. They are profitable. They make money. You buy the best and you, you know, do your thing. But there's more to that. The mechanics of the market, particularly when we're talking about things like 401k plans. People are putting money in every single paycheck, whether the market is up or down. They don't look at it and say, well, you know, the market is not looking so good right now. I'm going to hold back on my weekly deposit to my 401k plan because I'm worried about the market. That's not how it goes. Now, they may make some adjustments. You may do it too in your 401k plan from time to time.
8:50maybe take a more equity position, less equity position, more bonds, more commodities, who knows, whatever it is, maybe just let it sit like most people do, by the way. Most people, that's what they do. But you don't stop depositing into the 401k. The mechanics of the market are very simple. There are millions of people every single day that are putting money into the markets. What you have to worry about is when the employment rate changes, when all of a sudden we have a spike and unemployment, that's a lot less people working. When a lot less people are working, what happens? Two things when it comes to 401ks.
9:22There's less money going into the 401k on a regular basis because they're not getting paid. The second thing is they start taking their money out of their 401k. Now, they may have reinvested if there's enough money, but what if they need that money? What if they need that money to live? They start taking it out. So there's something to be said about the mechanics of the market. there's always money moving in. That's the principal driver. That's one of the reasons why the markets have this propensity to move higher.
10:00When we look back on September, it's a couple of weeks into this already, but I was thinking about this, and yeah, we had a good September, right? S &P was up 3.5%, the NASDAQ up 5.5%, Dow up 2%. One of the best Septembers for the S &P 500. October is coming. Now, everybody knows that October, well, not October, it's here. It's not coming, it's here. Everybody knows that October is a questionable month for a lot of different reasons. But okay, maybe it won't be. Listen, so far, there's been some corrective action we've seen. And some of it's scary, depending on what stocks you have, what positioning you have, what your asset allocation looks like.
10:40But at the same time, there's been this pop back relatively quickly. Five days down, you know, just turns right around. V transaction, boop, right back up. Is that going to happen now? I can't tell you that. But the breadth is something that I've been watching very carefully. And to transfer it between very narrow and then wide, and very narrow and wide. But the narrow is starting to get a little bit questionable. Something we'll probably talk about with our guest today. I also want to talk about vendor financing for a bit, something that's gnawing at me still. So let's move into that section of our discussion today.
11:23Before we do so, got to talk about interactive brokers, and I want to make sure that you're not fooled by zero commissions on crypto trades. Some brokers add a spread to the price you pay, and you got to know that. But at interactive brokers, there's no hidden spreads, and you'll pay much less than you would pay at, let's say, Gemini, Robinhood, or Fidelity even. Keep more in your pocket and trade crypto for less coin at Interactive Brokers. Now, trading cryptocurrencies involves risk and is only for individuals with high risk tolerance and the financial ability to sustain losses. Compare other brokers' fees and see how much you can save at Interactive Brokers.
11:59Go to ibkr.com slash crypto. And our guest today is Tom Nelson. He's a senior vice president and head of asset allocation portfolio management for Franklin Templeton Investment Solutions. He's a member of the Investment Strategy and Research Committee. He's been on before. He's a good friend of mine. He's in charge of the things like the Next Step Fund series from Franklin, the VolSmart Allocation. He's a portfolio manager of the LifeSmart Retirement Target Funds. So, Tom, you have a lot on your shoulders. Yeah. Yeah. Sorry to remind you of that. Yeah. Thanks. You're trying to forget. I know. Not to mention the fact that you picked up the daily writing for Franklin, the market overview, trying to be succinct, but yet bring in some life into what could be sometimes boring topics.
12:55Agreed. Yeah. So you're doing a good job at that. Thank you, sir. Well, let's talk about a few things. We could talk about the markets. We could talk about what is going on right now. But we do that a lot. I thought what we'd do today is change it up a little bit and talk a little bit about kind of the big picture, right? The macro environment for most people, they think of economics. But there's a bigger picture out there of what's happening. You have to, I think, blend a few items. because while markets have been resilient to a lot of things, other things bother them. But let's get to a first top level view of your general macro outlook.
13:39And then we can take it from there. Yeah, sure. So and thank you for having me on. Always good to catch up on these. At a high level, we I would say we're modestly bullish today. First of all, the Fed has made it clear that their intention is to deliver a series of rate cuts, and that's into an economy that's on mostly solid footing and in some ways accelerating. Stocks really had clearly bought into that narrative. And the most recent Fed meeting really didn't do anything to undercut or change the market trend. Cyclicals are outperforming defensives. A lot of the risk on factors are doing well.
14:27The AI trade is staying well bid. Things are feeling a little bit tired. And so we would say that the degree of difficulty from here is likely higher. But it's hard not to be impressed with U.S. equities and how well that they have done. And so we do think that the path of least resistance for stocks is higher, maybe with some turbulence and a bit of a pause here. The Fed has just eased into strength, which if you use history as a guide, that provides positive returns with fairly high hit rates historically. But let me ask you a question. Let me interrupt you for a second on that, then bring me back to where you're going from that.
15:12The Fed cutting into a strong economy. Now, is that the equivalent of them? Do they ever raise into a slowing economy? Like, I mean, it seems to me that the economy to a degree, we saw a few weeks ago the ADP numbers and some of the other jobs numbers with like the initial claims over the last few weeks. I mean, okay, you know, strong week, strong week. It's somewhere, I would say, confusing, But yet nothing – there's no huge – it's not like we have a 5.5 % unemployment rate, right? You know, some were – so the Fed, they – I can't imagine because they don't. They don't – they spend all sorts of money, but they don't have a crystal ball, nothing better than you guys have at Franklin, to be honest.
16:00And, you know, what's with the rate cut? So the, quote unquote, dual mandate of the Fed is basically price stability and full employment, right? And so inflation has, while it's come down, and it's still above that kind of magical 2 % year on year level, inflation's come down to a point where it allows the Fed to start to ease. There are some concerns and we would be counted amongst those that are a little bit concerned that inflation could go higher from here. And then on the other side of the coin, so that allows them, I think, in some ways to ease. The other side of the coin is full employment, right?
16:51And we've seen some cracks in the labor market, some softening in the labor market. And to help prevent from a slowing economy, the Fed has the ability to ease interest rates. And then kind of behind all of this, and having said that, the economy is in pretty good shape right now, as I had mentioned, right? And so if you were to think about the neutral rate of interest, which is neither stimulative to growth nor stifling to growth, is below where rates are today. We, being the Fed, had aggressively raised interest rates in the face of inflation levels that were as high as they were since the 1980s a few years ago.
17:44And it's now time to bring levels of interest rates back to more neutral rates. And that's where the Fed is embarking upon the easing cycle today. It is much better for the Fed to be able to ease when they can than when they have to and when the economy is really sputtering. And so easing into a resilient backdrop is one that generally is pretty good for markets overall. But at the same time, we all know, or at least we all believe, and I think the markets believe, and everybody talks about the horrible predictive powers of the Fed, the inability for them to even know what's going on tomorrow, much less three months from now or six months from now.
18:35And we're all resigned and very happy with the fact that they're cutting because we believe that they think that the economy is slowing. But yet at the same time, we keep forgetting, wait a minute, we really don't believe that the Fed has the ability to predict. They're wrong consistently since time has begun. The only times they're right is almost like by mistake. So is this one of those things where we go along with the data and the information because it's the best we got? Like, you know, for years, everybody's like, oh, Chinese data. You know, Chinese data is no good. Chinese data is, as a matter of fact, it's suspect at best.
19:17but we go along with it anyway, don't we? Cause that's all we have. Yeah. So I don't know. It just seems to me, I know I bash the fed a lot and it seems that just when I'm getting a little faith that they're doing the right thing, they just go along and do something stupid again. And their, their job is really hard. You know, and they're, they're trying to kind of navigate through murky waters through, through fog. And there's a lot of talk about the outlook to be fairly foggy. And they're operating a tanker, which is really slow to move. And in many ways, I don't necessarily want to be in their shoes.
20:04But overall, it's something that they've done. I would give him a pass on a lot of things. And if you were to just take out Fed release days, the days when the Federal Open Market Committee released their meeting results and potentially changed interest rates, your returns would be a heck of a lot lower outside of those Fed days. And so in some ways, the market has cheered over the last several decades the work that the Fed has done. You know, it's interesting. I'm thinking, I don't know, call me crazy, but FedGPT, maybe we can have an AI version of this one day that can actually utilize a lot more information and a lot quicker.
20:50I mean, we have DocGPT, DocUGPT, and all these other companies are starting to freak out that they can be replaced. it seems to me that if it was just inputting data and not using overlays of emotion slash anything else, and particularly when it comes to this data with revisions, you would think that a machine really – I never thought of this until relatively recently – that a machine can come up with what the right interest rate is based on Outlook, even if you look at Taylor Rule or whatever particular way you're looking at it. I mean, right. It seems like that could happen. I don't see. That's going to be interesting.
21:29All right. So let's get back to macro. So U.S. stocks, you said I'll just remind you, refresh you. U.S. stocks, you said doing pretty well. U.S. generally speaking, right, you know, with with earnings and all that. You said that the U.S. macro backdrop actually pretty good. Generally speaking, there's pockets of things here and there. Yeah. And yet the dollar is weakening. Gold hitting records, you know, over the last six months. silver popping really well. As a matter of fact, I bought some silver. Did I tell you about this? I bought silver bars from Costco. I didn't buy the, I didn't buy the, the, the futures.
22:04I bought the silver bar. I'm like, ah, what the heck? So I bought, they have these, these 10 ounce bars at Costco. And I happened to look recently and they also have platinum bars. They have like, I think there's a one ounce platinum because it's a different, it's like a much different pricing for platinum versus silver. Right. So I have gold. I've had a few years. I have some silver, and I'm thinking about buying platinum. And then I round it out. I have some Bitcoin and Ethereum. So there I am. I have all those outside items. But pretty amazing. The central banks have been buying gold. Dollar's been going down.
22:38There's been, even though there's really good things happening in the U.S., there is this trade that's going on. And I'm going to throw this to you as more of a question, more than a fact. Or I should say, is this trade that's going on a get out of Dodge, get out of the U.S.? feeling? I would probably say no. Although if you were to look at the first three calendar quarters of this year, the first quarter was in some ways all about Europe. The second quarter terms of returns. The second quarter was in many ways all about the US. And the third quarter was in many ways all about Asia. And so if you were to look at the MSCI all country Asia PAC index, and that includes Japan, although with or without Japan really doesn't make that much of a difference, was up about 12 % in the second quarter.
23:48China was up close to 13 % in the quarter. And so emerging markets have done quite well. But what I think we've really seen is a broadening out of the growth on a global basis. And to your point about looking at different models and inputs, we're big followers of leading indicators, and we kind of map out whether or not they're good or bad, they're positive or negative, or are they accelerating or decelerating, right? Right. And most everywhere around the world, except for China, leading indicators. And I'm looking at one of our favorite leading indicators right now. They generally are positive month on month and they're accelerating.
24:38China being that that one loan departure, which has been weak. But China is now reaccelerating. And and when things are weak, when things are kind of bad and but getting better, that historically, using history as a guide, tends to be a really strong environment for equity markets. And so in some ways, there's no surprise that China is doing so well. But all across the board, there is a broadening out of growth. And the growth rates are obviously different, and the acceleration, deceleration is different. But for the most part, things are in pretty good shape. The U.S. has been leading the rest of the world really since the end of the global financial crisis.
25:28And as well as the U.S. has done, the S &P in the third quarter was up close to 8%, we'll call it. NASDAQ was up close to 9%. So those are numbers that relative to history are pretty darn good. It's good for a year. Yeah, in some cases it's catching up. And the global 60-40 portfolio in the first nine months of this year has outperformed the US 60-40 portfolio. And the extent of the outperformance is like the second best since 2009, since the global financial crisis. And so I would call it more of a broadening out than anything else in the US, relative to everything else, is quite expensive. And so when things broaden out, those markets that tend to be a little bit less expensive, all us being equal, will do quite well and marginally better.
26:22So let's talk about that. Let's explain that. And let's make sure everybody understands what a 60-40, because you and I talk about this jargon that, it's funny, by the way, just to let you know, everybody, Tom lives really close to me. We spend a lot of time together, actually. And we're doing our things. We're going on a boat or something. We're hanging out. And we just kind of sneak away and talk about this stuff like two geeks. You know, because our other friend's like, What are these guys talking about? They're talking about the Dolphins game or whatever, and we're just sitting here talking about, yeah, what do you think about the correlation matrix of U.S.
26:53to emerging market right now? Something like that. So what you're witnessing right now is no difference than our discussion, except that we don't have drinks in our hand at this time. My bourbon something and Tom's skinny margarita. But the 60-40 portfolio, 60 % equities, generally speaking, just that line and 40 % in fixed income, right? That's kind of conceptually? Yes. That's not really anybody does. Nobody really does that, that I know. I mean, usually it's sort of like 60-40 conceptually with equities, but not just U.S. It's a blend of equities. And then the 40 % fixed income may have some other things underlying that for buffers like alts and things like that, but you still consider it a 60-40.
27:38So what you're saying is the 60-40 portfolio this year, which has come into question for a number of years. Is it dead? You know, the headlines, you know, a couple last, is the 60-40 dead? And maybe that was a little bit too early to call the patient, you know, the time is over. So the 60-40 is up, and that is because of what? The main component being international and emerging? Yeah. Yeah, so the US 60-40 is called like 12%, and the global is like 12.5 % year to date, just at a very high level. And 60-40 is generally viewed as representative of an asset mix that is appropriate for investors with kind of a moderate level of risk tolerance, right?
Read the full transcript
28:33So you're diversified across equities and fixed income on a global portfolio. It's different regions and countries and sectors and styles. And ultimately, that diversification across the asset classes and sub-asset classes and geographies is, while there's no free lunch, It's kind of as close as you can get by smoothing return streams, investing in different asset classes that aren't perfectly correlated, i.e. they don't go up and down at the same time and to the same level without really sacrificing expected returns. And so you can lower risk without sacrificing returns. And to your point about where a lot of that return has come from, yeah, it's absolutely come from outside the U.S.
29:27And some of that has to do with the weakness in the U.S. dollar, right? And so when you invest in European equities and Japanese equities and emerging market equities, etc., you are receiving the returns to those markets. But when you are bringing your investments back into dollar terms, as the U.S. dollar is down, call it 10 %-ish so far in 2025 relative to key developed market peers, that depreciation of the dollar, which is very much a 180 from what we've seen over the last 10 plus years, has also been additive to portfolio returns in that 60-40 portfolio. As long, right, conceptually, as long as people know that they may have investments that are outside the U.S.
30:22that actually could be dollar hedged, and there are times when you want that and times when you don't want that. Yeah, and the rule of thumb is generally, and this can obviously varied, but without any views on currencies whatsoever, we would generally not hedge currency exposure in equities. And so you'll have some dollar versus foreign currency risk there and potential return. And in fixed income, we would hedge that currency exposure. And the reason being is that because currencies are more volatile than bonds, and generally similarly to lower volatility than equities, what you don't necessarily want is that currency to be the primary driver of risk and return.
31:13And therefore, you are hedging out or you're basically eliminating any currency impacts in your fixed income investing outside of your home currency. But you're leaving that for equities because it's just not necessarily the prominent driver of risk and return there. Right. So going back to the dollar for a second, rationales, reasonings, why the dollar is fading. I mean, 10 % on a currency in a year, and that's the basket we're talking about. There are other currencies around the world where we're either a little bit above that or below that. But usually a dollar that's soft is a recognition of concern about something about that country, right?
31:58It could be also that there is an idea that the Fed is going to be lowering rates. There's a lot of things that go on here. But it seems to me that the chaotic rhythm of what goes on here in the U.S. these days is creating a little bit of an exodus. And that's also creating a buy into things like gold, silver, and hard assets, which I want to pick up on. And by the dollar being down, it's also a tailwind to those assets. so is this something that we need to be concerned of and i'm going to mention one other thing and let you answer because a few weeks ago i had peter chiffon and let's just say that he hasn't strayed from his idea that the dollar is going to collapse you know the word collapse is used a lot uh dollar is going to collapse and the only thing you really should have is a big bucket of gold yeah and and gold is uh well you can come back to gold in a second but yeah completely agree on the dollar.
32:56It has been weak. It is certainly stabilized. And so a lot of that weakness comes back to a couple of different things. Traditionally, when there's kind of geopolitical risks and concerns, the dollar tends to be a kind of a safe haven, if you will, and will do well in periods of kind of geopolitical turbulence. What is going on this year with all of the tariffs and the trade negotiations and things along those lines has led to, if you were to assume that a large majority of trade is done, you know, trades of goods and services is done in dollar terms, if the amount of trade is reduced, then there's less demand for those dollars to complete those transactions.
34:00There are some countries that have taken offense to the trade policies in the U.S., and many of those countries have large reserves of dollars. They also have large reserves of U.S. treasuries. And when there's concerns, and so if you're kind of unhappy with us potentially selling down your dollars in response to that is something that we've seen some evidence of, probably less than what people would have expected. And then to the point of treasuries, We have some pretty large fiscal deficits, which theoretically could be very problematic going forward. Pretty large? Pretty large? Is that what you just said?
34:51Enormous. Enormous is probably the more appropriate word, but yeah. And if you're concerned about owning treasuries, you sell them you don't need the dollars in order to support those assets. And so there's been a lot from that perspective. and so that has caused some weakness in the dollar. So let's talk about some, let's get into some nitty gritty about asset allocation. There was a study a number of years ago that was done. It was actually a preeminent study in the area of asset allocation. It was post-Harry Markowitz and it was all about, it was actually done for pensions, right? It was called the Determinants of, what was it called?
35:35Determinants of Portfolio, now I forgot the name of it. Oh, that's so bad. It tells my age, you know, the determinant. Let's see. I'm going to look it up live. Determinants of portfolio.
35:55I think it was Princeton B. Bauer and hood. Correct. Terminants of portfolio performance. That's what it was. I was thinking, I was thinking volatility. I had performance. Anyway, It was done in 1986. It was Brinson, B. Bauer, and Hood. I don't know. Did I ever tell you that I spent an evening with William Sharp and I had dinner at his table? And there was another time that a couple of these guys, I think it was Hood. No, it was B. Bauer. It was B. Bauer. And I went head-to-head with B. Bauer asking questions about stand deviation and utilizing downside deviation versus this. and, you know, the bastardization of how he felt about the bastardization of his study, which was not to be this whole thing about selling asset allocation like a lot of firms did, you know, back in the day.
36:44But let's talk about this and let's talk about the importance of this asset allocation. And with regard to this study, right, this whole thing that talked about the most significant factor that accounted for and determined the portfolio performance was the asset allocation. That didn't mean that asset allocation meant this blah, blah, blah, blah, blah. It meant that that was a big part of it saying that, let me say it a little differently, that if stocks, the biggest determinant of a stock is probably the general stock market itself. That's kind of the same discussion here. The biggest determinant of your portfolio's overall performance and therefore risk and things like that is where you asset allocate rather than the security selection or market timing.
37:38Correct. Yeah. So these days, though, when we have a bit of a difference, I'm not saying this time is different. I'm not saying that. Whereas the assets out there, the broad sectors and asset classes seem to be moving relatively in tandem a lot, risk on, risk off, versus we'll move into utilities for safety. We'll move into tech if we really want to ramp it. I mean, there's some of that going on, right? But generally speaking, bigger picture stocks, fixed income, real estate, they all have a bit of a rhythm. So is this as important anymore? I do think that it is. And correlations will, they will change over time, particularly over short periods, right?
38:34But on balance, you're still going to get some diversification between equities and fixed income. And we've gone through periods, even this year, when they moved in the same direction simultaneously. And we've been through periods, which is a little bit more normal, when they tend to move in different directions. But if you were to look over longer periods of time and generally asset allocation portfolios and to your point on the paper that we're referring to, that was for pension plans. And pension plans have very long time horizons, right? And I think that the number was over 90 % of returns.
39:26And importantly, the variation in returns was explained by the policy mix or that overall kind of asset allocation mix. And so over long periods of time, certain asset classes will kind of come in and out of favor in the interim. but it's how much you have of the major asset classes, how much equities, how much fixed income. We can potentially throw real estate in there and other assets. But that is going to be the primary determinant of your risk and return. And to your point earlier about if you were to look it's kind of the average stock, it does have certain attributes that are, of course, specific to that company.
40:14The industry group that it's in has some bearing on the overall performance, if you will, kind of rising tides, lifts all boats, you know, slightly differently in different industry groups. They could be leaning larger cap or smaller cap and there are indices that track those that could be a little bit different. But the primary determinant over the long term of any individual stock is going to be the market return or the primary risk contributor. And so through asset allocation and in these portfolios that were analyzed from a pension perspective and similar to the portfolios that we manage on behalf of a whole broad swath of different types of investors.
41:02It's how much you have in equities versus fixed income at a very high level. 60-40, we talked about, right, is going to give you a very different return and variation in returns than something that's 20 % equity and 80 % fixed income, which is also going to be very different from something that is more aggressively positioned that's 80 % equities and 20 % fixed income. And kind of what we did, And what we always do is we start and sit down with clients and try to get an understanding of what their objectives are, what the constraints that they have against that, right? And we want to make sure that we meet the return objectives, the risk tolerance, the time horizon, the liquidity needs, et cetera.
41:51And all that kind of makes its way into that broad, high-level asset allocation. Beyond that, there is some value to be added from leaning into or leaning away from asset classes, from choosing the right managers. But at a very high level, it's going to be the broad asset allocation, the broad market exposure that is going to determine the risk and returns that you are likely to achieve over the long term. So one of the things you do is manage the asset allocation models and for Franklin Templeton inside the various, we'll call them targets. Is that the right word? Target funds, I guess. Target data, target risk funds, model portfolios.
42:35There's been, I'm not a, listen, for my clients, I'm not a big fan of that. But for those people who have a 401k plan, let's say, I think that's the perfect place for this is the 401k plans. You know, for people that really don't know, don't have the time to deal with this and really need to have somebody semi-watching over. I just helped a client recently with their 401k. We went right into their Fidelity 401k and we set up the allocation and put it on automatic rebalance on a semi-annual basis. The automatic rebalance part of it is something that, you know, people oftentimes rely on us to do for them.
43:16because we're doing a combination of not necessarily automated, called semi-automated. When it gets to a point that we want to move, it doesn't have to be every quarter or every semi. It doesn't have to be when something we want to move something, but then we could design the rest of the portfolio around it where most people don't have that ability. So the target date funds really take care of that, right? So it rebalances and then takes you from, let's say when you're young, from an 80-20 portfolio, maybe to a 40-60 portfolio by the time you're 75. Yeah. Or something like that. It will keep you in the market, right?
43:49So it'll keep you invested. And there's the old adage of time in the market is more important than timing the market. And so it keeps the discipline of staying invested, staying diversified. And based upon broadly someone's age and what their time horizon looks like, so as they get closer and closer to retirement, their time horizon is shorter, their ability to withstand potential losses is less, and the portfolios, these target date portfolios, will make allocation adjustments based upon where people are within their basically pre-retirement lifecycle. And it's kind of a great set it and forget it solution in terms of appropriateness and discipline.
44:42I had somebody I had a discussion with a few days ago and they talked about, listen, I'm going to be retiring and I just need to be making what I'm making now. I'm like, okay, so I'm not arguing with that. However, what happens five years from now when, in fact, it used to be that you get a raise every year? Is your money getting a raise? Your retirement fund? Well, I never thought of that. Well, the fact is that even if it's not, and you don't think about that, are your costs going to stay the same? Or the fact is that just a 2 % inflation is going to creep up in over 10 years. That's going to be, without compounding, 20 % more cost factor.
45:21And you didn't keep up with it because you felt, I'll just leave it in the CD because that's easy right now. Now, I'm not suggesting that people shouldn't have any safe investments. But if you think about it, we have to really look at the idea that an asset allocation model, whatever it is, whatever that number is, is not just until you retire, but it has to take you for the rest of your life. The worst thing that can happen is that your money is in a situation where you outlive it. Right. we want your money to outlive you. And a lot of people have to, I've seen it. I've seen it where people just live.
46:05They're like, you know, I don't know what happened. And, you know, they just, all of a sudden they're, they're constantly having to do things that unfortunately, there's just not enough money to do what they need to do. I'm not talking about the nursing home cares and all that stuff. I'm just talking about just money, you know, on their expense side. So the asset allocation model, How does one go about figuring that out, aside from going to a target date fund, aside from utilizing an investment advisor? Yeah, very good question. And on the target date side, they tend to be pre-retirement vehicles, if you will.
46:45Some of them will have an asset allocation that continues to evolve for X number of years post-retirement. but they're more saving for retirement and getting you to that point. Beyond that, there tend to be income-oriented portfolios because you're going from a scenario where you are trying to save and build a nest egg to one whereby you've got that nest egg built up, you want to basically retain it, but you also need it to be able to generate enough income to support you in those retirement years. And there are a number of income-oriented model portfolios that we manage, but retirement income type solutions or income portfolios that are designed to provide competitive levels of income.
47:45And the investor kind of needs to figure out how much ultimately they need. But the portfolio does throw off a certain amount of income with the desire to, depending upon the strategy, maintain a certain amount of principle or have that principle last for a certain period of time and then ultimately be liquidated after X number of years. But ultimately, you want something that is going to generate you income and is not going to do so with an inordinate amount of risk that you could be exposed to potential losses should there be market drawdowns. And so they tend to be a little more conservatively oriented.
48:32So what's your expectations on like a 60-40 portfolio in the next 10 years? Now, one of the things, let me set the stage, is that a lot of people are talking about that maybe we're ahead of our skis with valuations. And usually when you see these kinds of incredible runs of markets for a number of years, I mean, the last five years has been like, oh my God, that's enough. That's good. I mean, you could package that up for a lifetime of returns right there if you did it right. But what are we talking about and the expectation that you're looking and modeling for the next 10 years? Yeah. So last 10 years, global equity, global fixed income, this includes emerging markets, has returned about eight and a quarter percent.
49:12That relative to the last 25 years is kind of 80th percentile. So it's pretty darn good. next 10 years. And this is using return expectations that we develop. There's a number of firms like ourselves that have return expectations. They are mostly valuation oriented. And kind of the high level idea behind that is when markets are very expensive, you can expect forward returns over the next 10 years or so to be less than average, right? And when markets are quite inexpensive, you can expect returns over the next 10 years or so to be higher than average, all else being equal. Sitting here today, markets are generally not cheap.
50:10U.S. equities are not cheap at all. The rest of the world relative to the U.S. is less expensive. But overall, that 60-40 portfolio 10-year return expectation is about 6.5%. Not exciting to anybody. Nobody's excited about that. And that's a little bit lower than the last 25-year averages. That's the important part, though, the reality. We may not be excited about it, but the reality is that's what the numbers are. Yeah. And getting back to your question about whether the U.S. is done or the rest of the world is taking over from a valuation perspective, the rest of the world is cheap. And therefore, our return expectations are modestly higher for developed and emerging markets outside of the U.S.
51:00over the next 10 years relative to the U.S. Yeah. One of the things that I've talked to you about a little bit, and I know there's something that we're going to kind of probably have to keep talking about over time because there's a big question mark in my mind about the quality of earnings. And what I mean by that is that we have companies that are ponying up all sorts of money to fund a variety of different build-outs or product purchases. And the question is, where is that money coming from and how is it working? So when I talk about like vendor financing or circular calculations when it comes to financing and income, One of the things that we saw this last few years is companies like a Microsoft or you take even a Google.
51:52There's a variety of them, right? And what they've done is they've taken chunks of money, invested that in startups and other companies. Those companies are turning around and buying platform space with Microsoft. So Microsoft takes$10 billion, gives it out to these companies, says, you know what? You're going to develop your stuff. We want you to develop on the Azure cloud. Okay, fine. and it comes back as, I'm just picking a number out of the blue here, $7 billion comes back to Microsoft. So essentially and effectively, what Microsoft did was they took money off their balance sheet and turned it into their income statement.
52:32Interesting. How long does that last? Well, there's a lot of balance sheet assets out there. And what happens is it's growing because the value of their stock is growing so much too, it doesn't really matter because they have that capital use for other things. Then what you have is vendor financing, companies like NVIDIA. NVIDIA, what they did was they said to various players out there, you know, we're going to do this. You're going to buy our chips from us, like with OpenAI, big numbers. OpenAI turns around and says to Oracle, you know what, we're going to probably fund somewhere in the, somewhere about, you know, $300 billion over the next five or six years.
53:09Meanwhile, OpenAI is losing money every year. Where are they coming up with the money? Well, maybe it's part of the deal that Microsoft's given them. So there's this big circle jerk and vendor financing going on. We've seen this before. This is back in the tech bubble, not trying to freak people out here. But my question is, when you have your fundamental guys on the job there at Franklin Templeton, is anybody asking them to understand more about the quality of earnings and where they're actually coming from? because I think that's something that we need to be aware of. It may, by the way, it may be fine.
53:46It may be just, hey, that's good. Everything's good. Yeah. But is that something we're looking at? It's something that we, within my team, look at a little bit less because we're more asset allocators than folks that do this. I see more top down. Yeah, we're more top down. And so we'll leave that analysis to the fundamental stock picking folks amongst the other teams that we will then farm out money to. One of the themes that we have seen that we continue to keep a watchful eye on, and I think this is a very similar type of a scenario, is corporate buybacks. Right. And and the fact that the expectation for for the full year of 2025 and we're three quarters of the way through the year, those numbers are becoming much more clear.
54:47But somewhere in the vicinity of a trillion dollars of stocks is being bought by those companies that issue those stocks. And, you know, it's really a function of various uses of capital. And if you think that your stock has a better opportunity to deliver returns than opening a new plant somewhere or, you know, building out. Especially because you're the king of the stock return if you're buying it back and pushing the price up. Correct. And when you're buying it back, there are fewer shares outstanding. And under the same amount of earnings with fewer shares outstanding, which is the denominator of that equation, that will increase your earnings per share.
55:40To your point about quality, that might not be the greatest quality of earnings growth, but it is a big portion of earnings growth. And when they are buying back their stock, that is creating demand to buy that stock. And so if that were to go away, that would be a large net negative to the equity market. So Howard Silverblatt, who is the keeper of the keeping information and all of the data and all that for S &P 5, for the S &P indices, S &P Dow Jones Industries. I don't know if you know him, but he's been a friend of the show. He's been on for, I don't know, 12 years. He's been coming on the show regularly.
56:18He's actually down here in Florida, too. We should probably do a lunch. But the thing about Howard is I've talked to him before. I said, has anybody done an analysis that strips out and does a retroactive look at earnings without stock buybacks? And I can never get a really good answer. But don't you think that would be something to look at? Yes. Companies are very fond of saying, you know, we have here's our earnings on a constant dollar basis. or saying without extraordinary items or with this, or they give you all sorts of reasons and rationale, right? As long as it's in their favor. So why not look at some of these things to try to really get down on what the real earnings are?
57:08Wouldn't that be striking to see if companies are really adding that much to their earnings just from the financial engineering? Right. That was the word I was going to use. financial engineering is. And stripping out the financial engineering could be a very good way of understanding just the organic growth rates of the company. Yeah. And what's interesting is, listen, the stock buybacks, they call that shareholder-friendly types of transactions. I'm a shareholder. I like them to be friendly. I'm all happy about it. I'm not complaining. but you wonder when, you know, all of these things kind of slow down a little bit and then, you know, there's a big change that happens and all of a sudden, who knows what that pillar that is going to be the weak one that's holding this all up.
58:02That's something to think about. That's something to think about. All right, we talked about gold. We talked about Europe. We talked about EMs. We talked about 60-40, Brinson B. Bauerhood. We covered a lot of area with Tom Nelson. Tom Nelson from Franklin Templeton Funds. Always good to have you on. Thanks for joining me again. Appreciate it. Thank you, Andrew. Thanks. Well, that's going to wrap it up for another great show. We have so much coming up the next few months, all the way through, I think, January. We are booked with great guests. So make sure that you're here. We have Howard Lindzen coming up.
58:31We have Danielle DiMartino Booth with an insider's look at the Fed, Vitaly Katzenelson. And we have just a whole host of people that are coming up. So make sure to be there. Ross Gerber, Tim Knight, Howard Silverblatt. I mean, boy, the list is thick. Make sure you are a disciplined investor. Make sure you stay a disciplined investor. Make sure you go to thedisciplinedinvestor.com and see all the things that we have to offer you over there. Thanks for joining me. I'll see you again real soon. This podcast is intended for informational purposes only and does not constitute personalized investment advice.
59:06Investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz & Company, Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz & Company is properly registered or is excluded from registration requirements. Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement.
59:45Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates of Horowitz & Company.
From the publisher
The government is shutdown – How long this time?
The Bubble – how much longer can it last?
The healthcare sector gets a needed boost….
Guest: Tom Nelson, Franklin Templeton Funds
NEW! DOWNLOAD THIS EPISODE’S AI GENERATED SHOW NOTES (Guest Segment)
Tom Nelson is a senior vice president and head of asset allocation portfolio management for Franklin Templeton Investment Solutions. He is a member of the Investment Strategy & Research Committee.
He is a portfolio manager of a number of funds offered for sale in various jurisdictions. He is lead portfolio manager of the Franklin NextStep Fund series, the Franklin VolSmart Allocation VIP Fund and numerous model portfolio programs. He is portfolio manager of Franklin LifeSmart Retirement Target Funds, the Franklin Fund Allocator Series available in the United States and several custom institutional portfolio mandates.
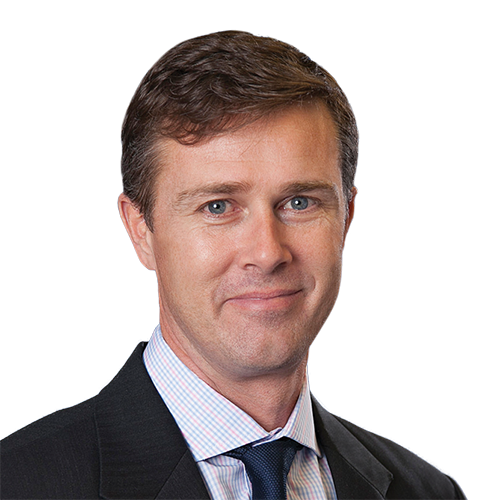
Mr. Nelson joined Franklin Templeton in 2007 and co-founded the firm’s quantitative research services group upon joining the company. He moved to Franklin Templeton Investment Solutions in 2009. Prior to working at Franklin Templeton, Mr. Nelson worked for Bloomberg LP from 1991 to 2007, where he was most recently manager of the Americas market specialist teams.
Mr. Nelson holds a B.S. in accounting from the University of Delaware. He is a Chartered Financial Analyst (CFA) charterholder and a Chartered Alternative Investment Analyst (CAIA) charterholder. He is a member of the CFA Institute, the New York Society of Security Analysts and the Chartered Alternative Investment Analyst Association.
Check this out and find out more at: http://www.interactivebrokers.com/
Looking to invest in The Disciplined Investor Managed Growth Strategy?
Click HERE for the virtual tour.
Stocks Mentioned in the Episode: (AMZN), (NFLX), (PLTR)