
In short
Market outlook amid “headline exhaustion,” valuation/multiple expansion risk, Fed-rate-cut debate, and how to recalibrate trading/hedging using sentiment + DeMark-style exhaustion signals.
Guest
Thomas Thornton, founder of Hedge Fund Telemetry. Background: former hedge-fund “sentiment provider” liaison; builds a sentiment system measuring stocks, bonds, currencies, and commodities on a 0–100 scale; uses DeMark indicators and technical internals; runs daily S&P 500 signal screening.
Key claims
Markets are frothy/overbought (sentiment around ~80 vs ~10% in April) and can turn; April’s volatility offered a timing window to shift from net short to net long. Valuations are stretched: Microsoft ~25x earnings to ~40x; Nvidia ~50x; S&P forward/trailing and CAPE rising (CAPE ~30–37). Leverage via single-stock leveraged ETFs and option-selling funds (especially put selling) could amplify a correction.
Notable examples
Uranium/URA up ~57% YTD; Nvidia bought under $100, sold around $145; Wingstop near ~100x earnings then declined; semiconductor leveraged ETF down ~30% after “DeepSeek” news.
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOMarket Overview and Insights
1:25 to 2:17
Discussion on recent market trends, earnings, and economic indicators.
“Horowitz & Company, from seed through harvest, cultivating financial success.”
Navigating Market Volatility
2:17 to 4:22
Exploration of market volatility and investor behavior amidst economic changes.
“We have a lot of headlines that are tiring and exhausting.”
Political Impact on Markets
4:22 to 6:04
Analysis of how political decisions and headlines affect financial markets.
“We survived yet another catastrophic situation.”
Global Economic Comparisons
6:04 to 11:12
Comparing economic conditions in the U.S. with other countries and the implications.
“and I think a lot of those will get extended if there's a good faith, quote-unquote, framework that goes on.”
Future Market Predictions and Fed Policies
11:12 to 14:00
Discussion on future predictions for markets and the Federal Reserve's stance.
“There are definitely people that live well.”
Federal Reserve's Rate Decisions
14:00 to 15:06
Explore the Fed's current stance on interest rates and market reactions.
“But the commentary was pretty clear that the Fed is in favor of waiting.”
Market Sentiment and Investment Strategies
15:06 to 20:03
Discuss the current housing market and investment approaches for uncertain times.
“But all these things don't add up to a rate cut right now.”
Discussion on Formula One and Racing
20:18 to 21:46
Engage in a light-hearted conversation about Formula One and racing experiences.
“So, you know, I know you're a big Formula One race fan.”
Data-Driven Investment Analysis
21:46 to 28:00
Dive into sentiment analysis and market indicators for investment recalibration.
“I've been in some very cool race cars with other people driving me.”
Understanding Market Movements
28:00 to 29:00
Learn about recognizing specific market indicators and when to adjust positions.
“you look at a variety of different indicators or just, just a chart for God's sakes, forget about being fancy.”
Show all 22 chapters
Position Sizing and Uranium Stocks
29:00 to 30:40
Discover the importance of position sizing and the recent success of uranium stocks.
“How do you know when it's like, all right, it's time to just cut and run?”
Navigating Market Volatility
30:40 to 33:20
Explore strategies for navigating market volatility and making investment decisions.
“We actually have a little bit better price because we bought more a little lower.”
Evaluating Stock Valuations
33:20 to 35:30
Understand how to assess stock valuations and the risks of multiple expansions.
“And of course, we've got a lot of tariff news.”
Using DeMarc Indicators in Trading
35:30 to 36:50
Learn how DeMarc indicators can aid in making informed buying or selling decisions.
“For example, I'm sure a company, Wingstop, and it was trading at nearly 100 times earnings.”
The Importance of a Disciplined Approach
36:50 to 39:40
Recognize the value of maintaining discipline in investment strategies amidst market fears.
“And every indicator in itself, again, you need other things to sort of correlate with it.”
Market Fundamentals and Current Trends
39:40 to 42:09
Analyze current market fundamentals and historical context to assess future trends.
“You just made the case for having a process, for having a discipline.”
Market Behavior and Leverage Risks
42:09 to 46:04
Explore recent market behaviors, focusing on leverage and its implications.
“And in the end, the fundamentals always do play out to come to levels that make sense.”
Risks of Current Economic Policies
46:05 to 50:06
Discuss the impact of U.S. debt levels and economic policies on the market.
“And they didn't cost$10 million versus, you know, $100 billion.”
Implications of Low Interest Rates
50:07 to 54:54
Analyze the consequences of low interest rates on housing and the economy.
“an independent uh i'm skeptical most politicians um the last president the last president this president um i am one of those that is concerned about the growing deficit in peacetime the out of control U.S.”
The Dangers of Populism in Economics
54:55 to 55:51
A cautionary perspective on populist economic policies and their historical failures.
“I mean, sadly, if you want the housing market to, let's say, prices to come down, more turnover, you have a recession.”
Economic Concerns and Market Volatility
56:00 to 1:03:00
Discusses the impact of economic policies on markets, referencing historical precedents.
“Number two, we're going to go back to Erdogan in Turkey or Argentina or Venezuela and what they did and the belief that lower interest rates will bring down inflation, which didn't happen.”
Hedge Fund Telemetry and Scams
1:03:00 to 1:04:23
Thomas Thornton shares insights on his work and warns about scams on social media.
“You can just find right on the front page there under the podcast.”
Transcript
Automatic transcript. May contain errors.0:00This episode is sponsored by Interactive Brokers, and I have a question for you. Will U.S. initial jobless claims exceed$220 ,000 for the week ending August 2, 2025? The Yes Forecast contract recently traded at 54%, and the No was at 44%. With Interactive Brokers forecast contracts, you can trade on future events like climate change and the economy or politics. You choose yes or no, and if you're right, you get paid. It's that simple. Explore the data, spot the trends, and make your prediction. Trade forecast contracts at interactive brokers and earn a dollar for every correct prediction. Plus, you'll earn 3.83 % APY on your investment with an interest-like incentive coupon.
0:49And you'll get$3 when you start trading with the forecast contracts. Now, forecast contracts are not suitable for all investors. Go to ibkr.com slash forecast and start predicting today. The last trading day for this contract is August 7th. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast. This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz & Company, from seed through harvest, cultivating financial success.
1:38We got new highs on some impressive earnings. GDP ramps up for the second quarter. PCE inflation ticks up slightly and the jobs number hit. And our guest today is Thomas Thornton from Hedge Fund Telemetry. All this and much more on episode number 932 of the Disciplined Investor Podcast.
2:17Well, hello there. We have deals. We have frameworks. We have pauses. We have delays. We have a lot of headlines that are tiring and exhausting. I don't know about you, but I am just like, all right, enough. Can we just chill out for five minutes here? Hey, I'm Andrew Horowitz. Thanks for joining me on this very balmy summer week. It is like record heat in places around the world. We have tsunamis that are happening and all sorts of crazy weather that's going on. No rainfall here to speak of, nothing major. We need Adam Curry to shake that rain stick on the No Agenda show. And it's been pretty dry here down in South Florida.
3:00But markets have been on the upswing. That's good news, and we are very pleased about that. The fact is that probably one of the reasons that markets have been in this bull mode is that all this deal and all this tariff talk, I think is seemingly coming to an end. I mean, once we had that big shock back in April, everybody was freaking out. I mean, the markets were rotating and moving like crazy thousand points up and down on the Dow 2000, 5 % on the Nasdaq. I mean, there was some massive moves in the VIX. What did it get up to? Like 60, I think it was, right? Somewhere around there. VIX is now in the 15 range, climbed a little bit off of those lows.
3:44I think we even clipped a 14 handle, and now it's approaching 16 again. But I think that people got the hint that, you know what, it can't be like that forever. It really also, I think, supercharged some of the buy the dip people that said, you know what, we don't get these opportunities too often. And it's not going to stay like this, these really heavy levels to the downside. And I think people right now are generally exhausted from all of it. So the idea that we're closer to the end of all this makes for a positive outlook. Right? We survived yet another catastrophic situation. And the more we do, the more it is ingrained and it creates this Pavlovian response to market downticks.
4:37I'm not talking about necessarily a simple downtick of 2-3%. I'm talking about, you know, when you have these big rushes down of 10-15-20%, people are like, wait a second. What we're dealing with here are companies that are extraordinarily adept at making money. I mean, if we know anything from the earnings that we saw, whether it was Microsoft Meta this week, I mean, companies do, you can take the list, there's a long list. They do a great job of beating analyst expectations. I think the numbers that we looked at this week was somewhere just shy of about 80 % of companies are beating analyst expectations.
5:21And usually you see the number that I go with is about 77%. In fact, those numbers that we're seeing, we're beating, the fact is if you dig down a little bit more, beating by a much lower margin. than we have, I believe it was on a 5, 10, and 20-year history. So we're beating. Companies are doing a great job at beating, but it's a much slimmer margin that we've seen. That still is a beat. Expectations versus reality is all that the markets are all about. Now, I know there's probably some truth to what's going on right now with regard to all the different deals that are happening, last-minute deals, the best deals ever, the extension of Mexico, because there was a note out that we get to August 1st or August 4th, whatever the first day that's going to exactly happen, that we're going to see, or that we saw, again, some of them are in play and some of them aren't, an automatic return to those crazy numbers for anybody that doesn't have a deal in place already.
6:35and I think a lot of those will get extended if there's a good faith, quote-unquote, framework that goes on. But generally speaking, I think people are excited about we're close to the end of this. Now, here's the problem with all this, because there's some truth somebody was talking about this week that our president likes to just simply throw hand grenades into a room just to see what happens, just to see, well, okay, what does it affect, and then fix it. So it's unclear what the next thing is. I mean, the damage that we can get from Mexico and Canada at the rates they are now, or is Trump going to put the screws back to China?
7:13Is he going to get more involved in the Middle East conflict, which he did this week, by the way, or even the Russian-Ukrainian war, which he did?
7:25There's a lot that is going on, and I think there is this headline exhaustion that we're seeing. In fact, I wanted to pull up, I know this sounds a little crazy, I'm going to pull up my Reuters app, my Reuters news app. You can do this with any one of these, it doesn't really matter. Find your favorite app that deals with news and just start reading. Because clearly there are lots of other things to talk about, right? But the truth is that if you look at the headlines, whether it's Reuters or CNBC or Bloomberg, it doesn't matter, any news outlet, Almost every story starts with a word or within the first couple of words, Trump.
8:02I'm just going to buzz through what I see here. Number one, let's see. Reuters. How Trump's crackdown on law firms is undermining legal offenses for the vulnerable. Second headline. Trump tariffs updates. Mexico gets extension. South Korea's cut deals. Next one. Exclusive. Trump's call broke deadlock in Thailand. Cambodia border crisis. Okay. Then there's something about tech in there. Wall Street. Let's see what else we got here. Let's get to the main one here. Okay, so the next one is, okay, Trump's envoy meets Netanyahu for Gaza aid ceasefire push.
8:38Zelensky movie, that's not one. South Africa, that's not one. But, I mean, really, Trump Mobile wants to sell you telehealth, car care, and insurance. This goes on. There's some things about Moderna, the rush to earthquake, a few other things. but you get what I'm telling you here. The fact is that it's all consuming. It's the Trump channel all the time. And whether or not it, I don't care if it's Trump, I don't care who it is, but what I'm getting at here is the government, our government. I mean, what happened to laissez-faire? What happened to Republicans being the party of less, smaller government?
9:20What happened to light touch? What happened to capitalism? A lot of things that are going on right now, I don't see as capitalism. I don't see it necessarily as anti-capitalism. But when we have price controls through tariffs, something's telling me it's not exactly what a true capitalist would be looking at. And therefore, we have problems because, well, we're setting up controls. Now, you may say to me, Andrew, Andrew, Hold on. Look at all these other countries, what they did. Okay, I get it. And you could even say, Andrew, all we're doing here is setting the prices at a level that's fair and therefore makes choice even more effective.
10:10Therefore, that's pure capitalism. Eh, okay, I can go with that. But yet, it seems to me that But we have gone through many, many years of these kinds of offsets where maybe the country that we are, as strong as we are economically, has done overwhelmingly better than most countries. And all you have to do is travel around the world and you'll know. We are the number one country from an economic standpoint, our way of living, our lifestyle. And yes, there is poverty. There's no question about that. Horrible, horrible poverty in the U.S. that needs to be fixed somehow, whether it's through education, whether it's through subsidies, I don't know, but something has to be done about it.
11:04But I'm talking about the totality of our general lifestyle and how we live here compared to other places around the world, particularly in Asia, India. I was just in India, let me tell you. There are definitely people that live well. Most people, not so much. up until a few years ago, they were struggling with having indoor toilets or toilets at all. And that's pretty interesting when we're concerned about them ripping us off.
11:39The truth of the matter is that we've created what we have created around the world for good reason, and it is to help us. We've created the manufacturing in Vietnam, Cambodia, Thailand, in China. Because it's good for us. We get cheaper goods. They get money. Everybody's happy. The idea that we're going to go back somehow magically and be the manufacturer of choice for the world is preposterous. I mean seriously it's dumb there's no reason to even think that we are the cutting edge of technology we are the people that you know are companies in the United States we bring the best of the best to make people's lives around the world easier, better and create affluence and money What we do really helps other countries around the world And I hope, I hope that this is not all going to put a major clamp on any of that I hope that it's not going to create and stymie innovation I hope that it's not going to slow down the opportunity for us to help other people grow For the benefit not only of them, the two-sided, right?
13:06a symbiotic relationship between their economy and our economy. It's going to take time to know. It's going to take years. And I'm not going to be sitting here trying to speculate. All I can say is that the next few months will be very telling about what we're going to see in terms of rates. I think that we talked about this a bit on the issue plug, but now that we see the PCE numbers come out this week, right, some inflation on that metric keeps on creeping up a little bit. Also, we saw the FOMC meeting this week. That was pretty interesting when Powell was, I think, strong-fisted, for lack of a better word, maybe even hawkish.
13:55Now, there was two dissenting opinions on the no change vote that happened. But the commentary was pretty clear that the Fed is in favor of waiting. They're in favor of just saying, okay, you know, let's see. There's no reason that we have to be upset about anything right now. We don't have to cut rates. The data doesn't support it this time. But still the markets are holding on to some hope. Still pricing in the possibility that in September, Remember, we're only talking about a couple of months from now, there's going to be a rate cut. Now, the probability is lower now than it was before Powell started talking at 2.30 p.m.
14:36on Wednesday. But the eternal hope for a rate cut is still there. Everybody wants a rate cut. The idea that it's going to help out mortgages, I don't agree with that. Now, again, we talked about this on DH and Plugged in detail. If you want to go listen to that, myself and John C. Dvorak, This week, we talked about housing prices and the fact that we are at an all-time high when you look at the Case-Shiller numbers on housing prices, yet there's a slowdown in sales. But even though sales are slowing and the Case-Shiller shows all-time highs, I don't consider that a condition when you'll see rate cuts, nor the PCE on the rise, nor with a generally good labor market with some obvious holes and weak spots.
15:28But all these things don't add up to a rate cut right now. I know we want one. I know everybody's yearning for a lower rate, the idea that that's going to help out mortgages. The fact is, though, with what we're doing with the amount of debt that we are creating, by pushing down Fed funds rate on the short term of the curve does not necessarily or even correlate to something happening on the long end of the curve where mortgages are priced off of. So I don't know what anybody's thinking and all excited about that this is going to help the housing market. And by the way, why does it have to help the housing market anyway?
16:04The affordability is so ridiculous. People can't buy. And if you did reduce rates, the affordability gets even worse. Gets worse. So what are we thinking here? Makes no sense. Makes no sense. Getting very tiring, which we've talked about at length. Exhaustion has set in. we're at the end of our patience with this whole nonsense maybe just a little bit of just chill dude for five seconds let's see how it all plays out when I say dude I'm talking about the entirety of all the things that are coming down the pike from the government whether it's the Fed whether it's the White House whether it's Congress everybody needs to relax for a second the good news is that we got plenty of fluff froth that is built up and taking portfolios for our clients dramatically higher.
16:57And that's good, right? So even if we do a little bit of a move back, that's okay. Now, one other thing I want to mention, because a lot of you have been like, I'm not buying in, I'm not putting my money in here, I'm in cash. I am not, the market's too high. And you've been saying that for the last, how long? How long has it been? Three months, a year, five years? We talked about this so many different times and why a lot of people have come to us with our getting back in, right? Our one foot in, one foot out approach of dollar cost averaging, of actually setting you up so that you don't have to be freaking out and pissed off yourself anymore.
17:34It's enough already. Let it go. The anger you're holding for yourself that you didn't buy in and you missed out on, and you think that somehow it's going to come back as if it does come down by 10%, you're better off. You're still, you know, it's up 20 % in a year or so. you're still behind the curve. So it's time to get yourself a new plan. And if we can help with that, I'd be happy to do so. Take that weight, that anger, that guilt that you have not planned as best as you can for your family because you're afraid. Let us show you how we actually do this to get you in to a point that you're not freaking out because it's, yes, I agree, there's some high levels right now.
18:23But at the same time, with the idea that we can get you in in a way so that in 5, 10, 15 years from now, you're going to be happy with the results that, you know, if markets continue to do what they've done over history. Now, of course, anything could happen. The fact of the matter is, the other thing you need to look at, though, is when you consider the future you, looking back at the current you, what is that future you going to say? What does the you of today say the person from the before you from five years ago that you're still sitting on a wad of cash? Something to think about. Give us a call or at least go to our website or figure out a way to get in touch with us and we'll set up a meeting.
19:12I'll personally talk to you and we'll get you set, okay? Before we get to our guests, I want to talk about Interactive Brokers again for a second, because if you're looking to trade gold, silver, platinum, palladium with low costs and global access, that's something you thought of? Well, at Interactive Brokers, you can trade spot metals, futures, and options on major exchanges, all from one powerful platform. Get efficient pricing, deep liquidity, and institutional-grade tools at your fingertips. Whether you're hedging, investing, or diversifying, Interactive Brokers puts the world of metals in your hands.
19:47Interactive Brokers is a member of SIPC. Futures are not suitable for all investors, and U.S. Gold is only available to legal residents of the United States. But U.S. Gold is not available to legal residents of Arizona, Montana, New Hampshire, and Rhode Island. Visit interactivebrokers.com slash metals and start trading smarter. Okay, with all that, let's get right to our guest. Thomas Thornton from Headfront Telemetry. How are you? Thanks for coming aboard again today. Andrew, nice to be back. So, you know, I know you're a big Formula One race fan. I got to say, how about that Oscar Piastri? I mean, first place standings doing pretty good.
20:31I'm a big fan of Oscar. He drives for McLaren, which has the best team car this year. His teammate, Lando Norris, they're fighting it out for the championship. I think it's going to go down to the wire. It's very exciting. The interesting thing about Oscar is he's Australian, and he's very unlike most Formula One drivers because he is super low key. He does not scream, yell. He's the most understated guy, and he's just incredibly focused and an assassin in the car. He's incredible. So have you had the opportunity to get behind the wheel of, I don't know, even an old Pinto F1 version or anything, any kind of car with a wheel that was an F1 kind of speed?
21:24I have. I've done some in the past. Now, I'm not one of the Netflix drive to survive newbie Formula One people. I've been following Formula Ones since the late 70s. I'm 60. So I've been a fan for a long time, been to many races. I have seen a lot. I can't say that I've driven in anything that would be remarkable. I've been on some tracks. I've been in some very cool race cars with other people driving me. But I don't have the body and structure and guts to drive a Formula One car or anything like it. They are incredible machines and very taxing on one's body. I have a friend that does endurance racing.
22:15Oh, that's funny. And it's funny because when I first met him, he was telling me all about it. He says, yeah, you know, we're going to probably go over to, I think he said, like, Belgium, I think. Or somewhere, maybe it was Italy, somewhere outside of the United States. And, you know, he's going to bring his team and do it. I'm like, how are you going to get all those cars over there? He's like, no, no, we've got a whole set of cars over there, too. I'm like, oh, so, but he goes like 24 hours. And I mean, 20, that's a long, that's very taxing on the body, right? Well, yeah, I mean, he's, you're, you're switching off with several other drivers, but still, I don't think people realize the, the mental and physical tax that a body goes through in a race car, you know, with constant 5Gs back and forth and in front and back.
23:06It's a lot of work. This is why we don't have 24 hours markets, by the way, because that's... I'm happy about that. Yeah, exactly. Actually, I've seen a lot about that. Yeah. And people say, oh, we should, you know, keep the markets 24-7. You need to rest. And that's why I don't trade crypto because I analyze it, but I just don't need to wake up on a Saturday and go to my screens and find out I'm down 15 % in something. Or not be able to sleep is a better point. Yeah. Because it's moving around. I like the rest. Yeah. So you built your reputation around data-driven sentiment analysis to a degree, right?
23:42To a point. A reputation, I should say. So I kind of, there's a lot of, from the past discussions we've had, there's been a lot of times we've talked about the process, right? The things that you do from a, whether it's technical or fundamental, whatever it is that goes into the process. And you have indicators. And sometimes the indicators are flashing one thing, but the markets or stock or whatever you're investing in moves the other way. The question I have for you is, how do you as an investor recalibrate? I mean, as far as. Your indicator is saying, hey, go long ABC. Oh, OK. And it's like, oh, no, that's not doing what it's supposed to be doing.
24:36And you have to make a decision, right? Right. I've got one of those today, but I will say this. you know, everyone has their own process that they develop over the years that works. You take things that have worked and things that don't work and you ditch those. But one of the things I look at, as you said, I look at market sentiment. I was fortunate at my old hedge fund to be able to be the guy that could speak to all the major sentiment providers. and I figured out the best one and I used that on our site at Hedge Fund Telemetry. I find it to be really pretty useful because it measures market sentiment from stocks, bonds, currencies, and commodities.
25:24And the thing that I find cool is that it goes from zero to 100. So when it's at 90, that's a very overbought, frothy type market. Now we're around 80 % right now. That's very extreme. Back in April, we were at 10%. And that gave me some indications that the market was getting pretty close to a turn. Now, what I also do is I look at a lot of different technical indicators. And I'm a specialist with DeMarc indicators that there's a learning curve that it takes to get to understand when they're the most relevant and actionable. And then I look at a lot of internals, like technical internals, and everything, for example, everything was lining up as a sell back in the beginning of the year.
26:20Everything was very frothy. And people could see that. They saw it. But all my indicators were saying, hey, you need to be positioned short for a move down. I figured the Trump administration would have a lot more volatility, which we have. And back when the Liberation Day hit, we had markets that were just plummeting. I had a call that we would be under 5 ,000 at some point in the S &P this year. It happened in April. But all my indicators lined up on one side. And when I get more indicators and things that aren't necessarily correlated lining up, it gives me a lot of confidence to get in there and to buy something and buy a lot of stuff.
27:07So we turned our exposure from net short to very net long and rode the bounce up. I will, truth be told, I'm having a great year, but I've overhedged myself a little early. and I have no problem with that. Look, the fact. Yeah. I mean, I look if you're up 18 % and you, you know, you start hedging yourselves and you're not getting up and down days when the markets are going up, you're doing something right. And that's the main thing I'm now positioning with everything starting to line up on the frothy overbought crazy side on the short, you know, much more short. I have a fair amount of cash, but I am net short.
27:52Yeah. I mean, I would think that, that I, first of all, I wouldn't argue, I can't argue with you everything that I'm looking at as well, whether it's individual stocks, you look at a variety of different indicators or just, just a chart for God's sakes, forget about being fancy. Just look at the chart. You know, when you see these kinds of hockey stick moves or, you know, these late day pushes or these, you know, there's a couple of stocks out there that they feel like, it feels like they're trying desperately to keep up, right? You know what I'm talking about, right? There's, you know, it's down all day until the last five minutes, and then the stock goes green.
28:26And it's almost like, you know, it's an option play, it's something else, which is something I want to talk to you about as well. But now, the recalibration, and the reason why I ask this, is that there's so many people listening that I believe get themselves into trouble. Because what they do is they either double down on a bad idea, or they don't double up on a really good idea. So this is the opposite discussion of recalibrating, which is either making a decision that you, making a bad decision worse, or not making a good decision better. How do you know when it's like, all right, it's time to just cut and run?
29:07And secondarily, when is it time to say, oh, you know what, I should be adding to this? well one of the things that we have to all remember is that we are going to be wrong and you know that's part of the the process that we go through we're wrong at times and there's times to just you know cut and run as you said and then you know one thing that i really try and i stress to my people size your positions properly so for example if i'm initiating a new position in something, it's most likely going to be around a 2 % weight of my portfolio. And if I'm down 10 % on that, and I still believe in the idea, I have the ability to raise my position up to 5%.
29:55Sometimes I'll just cut. And sometimes if I feel like the position is is and the idea really is relevant and good, I'll add to it. And one example was I bought uranium stocks this year and they'd already been down quite a bit. And I started my, you know, small dip your toes in with 2 % positions with three ideas. And those ideas went down even further. And I, you know, added up to 5 % on all three and uranium has been an absolute monster this year. I mean, I'm looking at all my, all my ETFs year to date. Uranium is the high, has done the best. The URA has done the best. It's up 57%. We actually have a little bit better price because we bought more a little lower.
Read the full transcript
30:56So we've, we've trimmed it on the way up too. So that's the, I'm not just sticking on that uranium deal. Um, we bought a few, a few positions for clients. Uh, constellation energy is a, is a name I own, uh, Oaklow, uh, SMR that monsters, monsters. Now some of them constellations are quality, you know, as a company that's, that's, that's got revenue. It's, it's, it's, it's solid. It's had some ups and downs and all that. And it will move up and down with the concept of, So as I call it, new clear energy, not nuclear, new clear energy, so that we don't have all the people hysterical about China syndrome.
31:29But those other stocks, the hope to bees, the ones that are in the small module reactors have been absolute monsters, monsters this year. So I get it. That uranium is a great thing. Yeah. And that's the thing, too. A lot of people will do the opposite of what you should do, which is you overweight the ones that have the larger ones in a particular sector. And then you layer in with some smaller weighted positions with some of the ones that have a little bit more spice. And a lot of times, you know, I mean, this is a market where people are trying to get rich overnight. And it really, it's very difficult to do in any market.
32:19But I think that that was one of the things back in April that I told people, I said, here's the opportunity to upgrade your portfolio and buy things that we really wanted to buy for a while. We bought, I bought Nvidia under$100. I sold it at, you know,$145 a little early. Okay, fine, whatever. but still I felt like that's what you do. Well, you do that in, in markets when you have, when you have markets that go down, that's where I start to look at it and say, buy the best quality and, and, and try and hold on as, as long as you can, because that that's going to give you some peace, peace of mind, especially if markets are volatile.
33:08There's a lot of news that is volatility driven. And so that's the part of the process as well. So right now, the way we are, here we are, and we're now in the third quarter, I think we're coming into a tougher time. And of course, we've got a lot of tariff news. We've got a lot of stuff happening out of Washington. Sometimes you got to take that with a grain of salt and try and just stay focused on the fundamentals. And one of the issues that I've had, and I chart these as well, is that this has been a market that has seen some extreme multiple expansion, which what that means is the price has gone up much more faster than earnings.
33:55And you can look at them. I mean, for example, Microsoft was trading at a reasonable 25 times earnings. It's now 40 times earnings. I mean, I'm not going to even throw Tesla in there because that's almost 200 times earnings now. But you even have an NVIDIA that's trading at 50 times earnings, and that's getting a bit rich. Even for a company that's growing as strong as they are, that's historically a bit high. So I look at individual stocks much more so than just looking at the S &P multiple, which is also high. So there's a valuation risk here as well. And that to me is a bit of a concern. And one of the things I've learned of doing this for multiple decades is you can never time the market based on valuations.
34:43It's a very dangerous game. And that doesn't mean you can't get close. But, you know, the problem is that you can have a market that is a 20 PE, goes 21, you know, forward earnings, 22, 23, 24, which obviously is a pretty big expansion on an index, right? And it's for other reasons that are outside the scope of what we're looking at. Yeah, I would tend to agree. But one of the things that, and again, I look at individual stocks when they get to the extreme multiple expansion or contraction. I've overlaid DeMarc indicators on the P.E. ratios with the price. And it's been actually pretty remarkable how well those exhaustion signals do at peak multiples.
35:37For example, I'm sure a company, Wingstop, and it was trading at nearly 100 times earnings. And now it's come down quite a bit. But we had exhaustion signals on the PE ratio at the highs. and that that's just another little quirk and part of my process that i use and and it's not one thing in itself that i would ever use you know i i throw a lot of stuff into the mix um i mean it's just like you know if you're you're baking a cake you need more than flour yeah uh to make it right so i i is is tom de mark still is he still active uh in his time is still Tom is still active and they have some new things coming out that they're trying to do some more things with AI.
36:33We'll see how that goes. But I generally have what I need and I know the indicators. I've used the indicators for almost 25 years. And again, I know when they're going to work real well and when they're not necessarily that effective. And every indicator in itself, again, you need other things to sort of correlate with it. And when it all sort of lines up on one side and you can then make a fairly informed decision, either, you know, you buy or sell. Got to count to nine. You got to count to 13 on DeMarc. That's true. If you know, you know. If you know, you know. But DeMarc Indicators is one of those things, by the way, for people who don't know.
37:17So they're a fascinating countdown. It's actually one of the things that's called a countdown. At first, you're like, what? Seriously? But then you start understanding about what it is, particularly about exhaustion on the up or the down and the intensity of it. And you have these countdown clocks. And if a couple of them line up together, or up, count up, countdown, but if they line up together, and once you get to know them, it's kind of really interesting to understand because he does a certain calculation based on pricing and all that. And it can be very accurate, which is for whatever weird reason, by the way.
37:54Yeah, it is pretty fascinating. And I really can't look at a chart without the indicators on there. And even when they're wrong, you sort of understand why they are. And that's a big tell in itself because that's telling you that the trend is super strong. But, you know, again, we had we had signals. I mean, the I'll be I'll be honest, the ones that happen with the let's say the S &P or the NASDAQ are a little trickier when they're on the upside versus the downside, because we had we had exhaustion by signals in April. And that was, you know, very helpful for me. The other thing I do, and I, with, within my, you know, with the work I do with the subscribers that we have, I try to keep it simple.
38:43And this, these can be very complex and, and they change and I try to explain what to anticipate. But one of the things that I do is I screen within the S &P 500 every day what signals are happening with the most relevant buy or sell signals. So sometimes when I'll see a huge amount of sell signals happening together, let's say they're happening within a sector, that is a signal in itself that perhaps that sector is getting overdone. Perhaps on the downside, when you start to see just a ton of buy signals lining up, that's telling you something as well. And usually when that happens, most people are panic stricken when it's on the downside.
39:30And on the upside, they don't want to listen to either because they're along the market and they don't want to pay any attention. But lo and behold, for the most part, they tend to work and work out pretty well. You just made the case for having a process, for having a discipline. Thank you. Because if you don't, then emotion, fear, and even to a point, your own personal overlays get in the way. Yeah. And I use fundamental analysis as well. And that's, you know, an important factor as well for me. So let's talk about some fundamentals. Let's talk about, let's go keep this on this discussion right now with regard to PE.
40:17So just a PE discussion. Big, big picture. First, we're going to start the big picture.
40:25April, I think we both agree that the gains have been more on an expansion basis where earnings have not grown. The hope is that they will, but they have not. We've gone from, I think, 20, sub 20 to about 22 and a half right now on a forward PE, trailing PE about a 30. The S &P 500 CAPE ratio, the cyclically adjusted price to earnings ratio, 10-year average has been rising over time. It was rising like this in 1999 through about 2025. And we saw it before that from 87 to about 99. but this time it's rising to about 30. We are now at about 30, 37 on the Cape ratio. And that is a time back in 2000, we'll call it 2023-ish, 2024, where it reached that point.
41:18Also back in about 2019 reached that point. And then it seems to be a top end right there. Those times are the highest levels in history aside from 1998, 1999? Now, I don't know if we can say, well, you know, look at that. Or we could say, well, these are different times. You know, now the data is flowing a lot more freely and there's transparency and an understanding of what's happening and investors have, you know, quick access to all this. Is it a different market? To a degree, I think it is somewhat. But the question then still remains, are we out of control right here? Yeah, I'd say that every market is different in some respect, but the basics are always there.
42:09And in the end, the fundamentals always do play out to come to levels that make sense. Sometimes it takes a long time. And when you start to see some of the behavior that we're seeing in the markets recently with a lot of the meme stocks going crazy and zero data expiration options, the amount of volume that's being traded every day, the concentration in the market is very concerning. because basically the market is trading 10 stocks every day, and it's the same stocks that are seeing the most amount of volume or I'd say the most market cap movement, so those of you know. But I also see some really dangerous signals that it will probably look back and say, this is a little bit concerning, and that could be the leverage in the market And the leverage in the market is quite high.
43:17Where is it now, comparatively? Well, the FINRA stuff is, it's hard to really, they changed some metrics on it. So they used to have some of the bank leverage in there. So it's different. But one of the things that I'll say that the advent of the single stock levered ETFs is a bit concerning. And I actually am very good friends with one of the guys that's a big issuer of those and the, you know, the kookier ones at that. And he's a fantastic guy. And he's like, I'm just, you know, fulfilling what people want. And he's hedged with swaps. And I think that people just want more bang for their buck.
44:02And that is sort of a sign. You could also use it as a short, an inverse inside of a IRA to hedge. Yeah, that's true. For that matter, you could use it inside your regular portfolio to do like a short against the box without selling your long position. Yeah, that's true. You can do that. But what I've heard from him is that the inflows into the most bullish things continue to be just growing like crazy. And every little dip gets bought into with the long exposure levered. Another thing that is really concerning is the amount of assets that have moved into funds that sell options. And that could be a covered call strategy.
44:54That's fine. But a lot of those funds are selling puts. And if you sell a put, and let's say something just falls out of bed and it lights out, those people are going to get dinged pretty hard. And with the VIX here, you know, and the teens, it's a bit concerning to me. And so like what, you know, some of the, all these things, this leverage, this short-term options, all these things and the put selling. What happens, in my view, is that we could have a correction that could turn into a catastrophe if some of these things have to get unwound. I mean, I know that the semiconductor levered ETF went down so big.
45:55I think it was down like 30 % in a day or maybe even more because of when DeepSeek came out and revealed themselves to have a cheaper AI type of process. process and it's working as well. And they didn't cost$10 million versus, you know, $100 billion. So that was pretty eye-opening to me. And so I see people, you know, overwhelmingly taking a lot of risk with these. And if we do have some sort of catalyst or event, it could just be exacerbated. And so when I see those types of things happening, my process tells me to take some money off, have some short positions, and be ready for something because it won't take much after the move we've had to prick the bubble.
46:54So what you're saying basically is if this was an F1 race, the guys in the race car have their pedal to the metal, they're not taking their foot off no matter how sharp the curve is. And the problem is that can only last for so long. And if it starts raining out and they continue doing that, there could be some real problems for their cars and for them. Well, I'll tell you this. Ayrton Senna was a Brazilian, one of the greatest Formula One drivers ever. And he raced for McLaren. And he was leading the Monaco Grand Prix. And he was leading the Grand Prix by 50 seconds, which is a lifetime in Monaco because nobody can pass in Monaco anyway because it's so narrow, the streets.
47:45But he was just going as hard as he possibly could. And he talked about it. He was in this zone. and what happened is with I think it was like 10 laps to go he hit the wall and and it was just that taking too much risk when you have a huge lead it it can it can bite you and it can bite the best of people because he was clearly the best driver I've ever seen drive and that is sort of how I see it. If you've got a big lead in the markets right now, you don't need to take more risk. You need to think to yourself, you know, what's my stated goal for the year? What do I need to do to be on my track rather than get caught out in something?
48:37And I think also we could blend in here in a non-political discussion, all the things that are going on, the information flow about whether it's tariffs, taxes, you know, the trial balloons that are thrown out every day, whether it's firing Bernanke, not Bernanke, maybe fire Bernanke, but fire Powell, fire Powell, don't fire Powell, you know, find him with fraud, or maybe let's now start thinking about no taxes on capital gains on houses, or whatever the daily, you know, you roll out of bed, it's like, okay, What's today going to bring? The big thing that I think putting that all aside, whether some of it's just funny or it's debilitating for some people, the fact of the matter is – the fact is that we know something to be true.
49:30We know that – put that all aside and that we have massive deficits. We have massive debt levels. We're at a point right now that we used to laugh at 10, 15 years ago that how could a country be 120, 130 percent debt to GDP? We're there, folks. How is that going to impact our country and not only the country, but the ability for the Fed to operate? And then finally, even the ability for companies to continue on this profit growth that they've had for a long time. okay well as far as the politics of everything um i i take a more neutral approach since i'm an independent uh i'm skeptical most politicians um the last president the last president this president um i am one of those that is concerned about the growing deficit in peacetime the out of control U.S.
50:30debt that I thought was going to be addressed, as well as the deficit. But that doesn't seem like that's going to be an issue. The talk of firing Powell is something that I find to be just a lot of noise. I don't see how that's going to happen. They're trying all sorts of ways now. But I think that Powell is trying to stay disciplined to his process and the Fed's process and knows through history that tariffs do raise inflation to some degree. We don't know what the true tariff rate's going to be, if it's 10%, 15%, 25%. It's been talked about and it goes and forth. So that makes it difficult for the Fed to figure it out.
51:24And the Fed's mandate is not necessarily for the stock market. It's for providing stable pricing, liquidity in turbulent times with the financial institutions, as well as maintaining low inflation, as well as the jobs market. And I think that the economy is strong. The jobs data has been coming in steady at 4.1%.
52:00That's low. I see the point of lowering rates a little. I don't feel they're restrictive. They haven't been restrictive if you look at the equity markets. And the equity markets is sort of the measure I would use there. But I think the bond market has other plans. And this is really important because when the Fed cut rates last year, they cut rates significantly. The 10-year and the 30-year yields, the treasury yields, lifted 100 basis points after these big cuts. And the yields were starting to move down because the people were thinking, oh, you know, the Fed's cutting rates. Everything's going to come down.
52:47It's just, but it didn't. And rates went higher. And I think the bond market is more concerned about the deficits, spending, maybe throw in tariffs, throw in the huge amount of U.S. debt. And if you really want to get interest rates, treasury rates low, you should probably be addressing more of the deficit. But President Trump is under the assumption that if you lower the Fed funds rate, that's treasury rates in this thing. And there may be some correlation, but I think the bond market's going to say, I don't think so. We're more concerned about the other issues that haven't been addressed. And so, you know, oh, everybody wants to buy, you know, let's lower rates to 1%.
53:40That would be inflationary. If we did that so more people can buy houses, the prices of houses would go up. I know, that's the ridiculous point right there. The unaffordability would even get worse. It would exacerbate the fact that housing prices have been going up all along. The last case, Shiller numbers are up three, three and a half percent on a U.S. basis. Housing prices, again, that's not everywhere, but that's the general statement. How does housing prices get more affordable if you reduce interest rates? Because it's automatically going to slingshot prices higher. You're right. And any time you give, I want to say free money, but low interest rates on something, it can be, I mean, we learned in the housing crisis.
54:26And when you had such low interest rates and basically my dog could have got a mortgage for a house and we saw it, you know, I'm friends with the guys from the big short. So we talk about all the time and our firm was short, you know, similar, but we didn't have a movie made about us. But it's same thing with student loans. If you make loans easier to get for students, the prices of colleges is going higher because there's more demand. And that is really the problem. I mean, sadly, if you want the housing market to, let's say, prices to come down, more turnover, you have a recession. And then you have more people that need to sell their houses because they lose their job.
55:20Now, I'm not advocating for that, but that is historically what has been a trigger for the housing market to turn over a bit. And Paul, you know, just blindly trying to lower interest rates is exactly what we just talked about. That's just populism right there. That's just a bad idea. Let's not even talk about it. I can't even talk about it. It makes me nauseous. Seriously, it's like the stupidest thing I've ever heard of. No, no, it's just stupid. It's just stupid to even talk about this. Because the idea, if we do so, first of all, it's going to be an upheaval in the markets themselves due to the fact that there will be a realization that politics are taking over an independent Fed.
56:00That's number one. Number two, we're going to go back to Erdogan in Turkey or Argentina or Venezuela and what they did and the belief that lower interest rates will bring down inflation, which didn't happen. We're in 30%, 40%, 50%. And the fact of the matter is it wrecked their markets, it wrecked their economy. There's no – and then on top of it, the final nail on the coffin will be that there will be no confidence in the U.S. economy at that point. So I don't even want to talk about it because if we get to that point, that's going to be really troubling to me. You're really getting me nervous.
56:31But I'm fine otherwise. I am fine otherwise. Well, you're right. Right. And again, if you just take a step back and you look at history and you look at what's happened in the past, and that's part of my process. I look at things when markets get oversold. What were all the other indicators doing? What was market sentiment like? Everything that when it gets oversold, it did it before. And if all those things line up, then great. We can get in there and buy, but it's also evident as well with economics. And maybe we're living in a little, you know, of a strange period with so much emphasis with the administration talking on TV every day.
57:26It's getting a little exhausting. I will tell you that. It's exhausting. Yeah, it's hard. And I, one of my neighbors who lives two houses away, he's, he works for Goldman Sachs. And he, after Trump was elected, he said to me, he said, and he works in the prime brokerage business. So he talks to hedge funds all day. He said, I don't think people quite remember the volatility with Trump and the tweets and all the other stuff. And I said, no, I don't think people do either. But with that, I will say I don't necessarily I mean, it's exhausting. Yes, I will say that. But it creates opportunity as for a trader and for, you know, you can have a dislocation in the market.
58:17and you scoop something up and get a great price. And lo and behold, you're looking back and saying, thanks, that's cool. Or the other side is true also. You get jacked up on promises that do not come to fruition or information that's only half stated. And for example, I'll give you an example of a half stated statement that is not factual. Well, let me say that. It is factual, but it's not factual. Here we go. no tax on tips. That's factual, except it's only half the sentence. No tax on tips up to$25 ,000. You know, as long as you make less than$150 ,000. So those kinds of things where we have the greatest deal ever with, I don't know, pick your poison, Japan.
59:07Really? So they're going to buy some corn and they're going to buy some rice and they're going to buy some vegetables from us and there's going to be a lower tax. I mean, that's the greatest deal ever. I feel like I'm back to when China was going to buy more soybeans. And that was like, oh my God, fantastic deal. These aren't great deals. These are not great deals. I understand and agree with you. I think there's imbalances out there and they should be addressed in some places. They might be picking off more than they should at first. Trade deals take years. I don't think that, I mean, look, I would love to see a better balance with trade.
59:55That would be great. But forcing it down the other country's throat at the expense of just basically higher prices, which let's remember who, I mean, again, who pays the tariffs? prices get jacked up and the consumer pays some, the company selling it in the U S pays some of that tariff. And, and, and then the supplier from, you know, Mogadishu is, is getting tagged for it as well. So it's a, it's going to hit margins and, and probably see a slowdown ultimately with some consumer spending. But it's not that, you know, you have, you know, these countries are writing the U.S. a check. It's it's I don't think that's quite factual.
1:00:46These are I wouldn't consider these quote unquote trade deals because I agree with you. Trade deals take they're intense. There's a lot of little big things. You don't just do this on a on, you know, a couple of months and say we're going to do this. You got to get it done by then. What this is, I'll tell you what it is. I break it and then I fix it and it looks like it's all better. That's what this is. And it makes sense. Yeah, I would agree. You know, that is sort of a staple of how Trump operates. And, you know, we just have to sort of align ourselves and see that for what it is and go with it.
1:01:25We can't. That's the bottom line. That's the bottom line also. Don't get caught up in all this. That's what we have. Yes, we have. Again, I think that if you go back and you saw like the beginning of the beginning of this term for Trump, he he had a I was all on board with seeing the government spending get cut. That how's that going? Well, I don't think it's I don't think it's addressing the big issues that, you know, the big places where there's too much spending. I mean, I, you know, finding the little things in there that are going to spin, you know, a billion here, a billion there. When we have a trillion dollars that's added to our U.S.
1:02:11debt every quarter, it's four trillion dollars a year. And the deficit is, you know, maybe it's going to come down a little bit, but still it's at levels that are really concerning. And if we go into a recession, which I will say this, I'm not necessarily, I mean, everybody know there's no recession in sight. I don't think that's necessarily off the table. And I'm not saying this year, but I could see something. There will be a recession in the future. There's going to be, let's get this out. There's going to be a recession one day. We can't deny that. And the fact is that probability is we're still going to have massive debt ahead of it.
1:02:50That's going to make it very difficult to deal with that. I think that's the bottom line. So change the scope of that. Thomas Thornton, I got to cut it right there. Tell everybody how they get in touch with you and where they can find it. We're going to have, by the way, on episode number 932 on thedisciplinedinvestor.com. You go there. You can just find right on the front page there under the podcast. Under the podcast notes, there'll be all sorts of information on how to get in touch with them. But Thomas, tell us anyway. Okay. My website is Hedge Fund Telemetry. Reach out there if you'd like a free trial.
1:03:19If you'd like to just sign up and say, yay, go for it. We're building a whole new site, and it's coming out in the next month or so, and I'm really excited about that. Good. Love that. I'm also on X at Tommy Thornton, but I've locked my account because I don't like the spam bots. I've been getting a lot of people doing imitations of me. You know, they changed my name to Andrew Horowitz with an L at the end or something like that. Nobody knows. And it's an imposter. And then they start talking to all my people about cryptocurrency. Yeah, I've had hundreds of those. And actually, I've had I've had people reach out to me and say, are you going to refund me for this this trade that I did?
1:04:03And I said, who are you? And he said, I was in your discord. And I'm like, I don't have a Discord. And there's a lot of scammers out there. And unfortunately, Elon hasn't cleaned up the mess that Twitter was. And now it seems to be even worse. All right, buddy. Have a good day. I'll see you soon. Take care. Thanks. That's it. That's a wrap. Thanks so much for being here. I'll see you again next week. This podcast is intended for informational purposes only. and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principal and past performance is not indicative of future results.
1:04:47The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz & Company, Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements. Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement.
1:05:19Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates of Horowitz & Company.
From the publisher
F1 Racing and the markets.
Earnings, economics and the Fed.
The casino – zero date options.
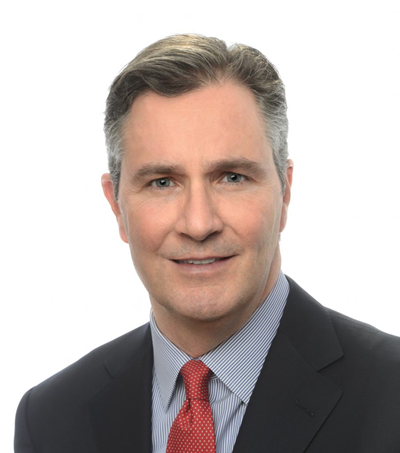
Thomas Thornton, Hedge Fund Telemetry is this week’s guest.
NEW! DOWNLOAD THE AI GENERATED SHOW NOTES (Guest Segment)
Stay Updated
Thomas Thornton is a former portfolio manager, senior trader, and technical analyst with Level Global Investors and Galileo Capital. Tom has written a daily market note for a select group of hedge fund managers for years and now has offered it for all investors with Hedge Fund Telemetry. His long term focus on sentiment indicators borders on the obsessive. Our growing team at Hedge Fund Telemetry is comprised of current and former buy and sell side individuals.
Hedge Fund Telemetry was first conceived with inspiration from Tom’s lifelong passion following Formula 1 racing. In the early 90’s, Formula 1 teams started to equip cars with sensors on every imaginable component and data was relayed wirelessly through telemetry to the pits to analyze and then instructions from the pits were relayed back to the driver so he could make changes to find the optimal balance for the car. It has always been the same way for Tom, as a senior trader at his hedge fund, he would get in early, collect data from many sources, analyze that data, and then communicate information out to his firm so his team could properly balance the firm’s portfolio. It’s now our goal to relay that same type of information so that one can also gain that edge.
Check this out and find out more at: http://www.interactivebrokers.com/
Looking for style diversification? More information on the TDI Managed Growth Strategy – HERE
Stocks mentioned in this episode: (MSFT), OKLO), (SMR), (WING), (NVDA), (CEG)