
In short
Podcast Summary: The Disciplined Investor - Episode #960: The Perfect Portfolio
Episode Overview In this episode of *The Disciplined Investor*, host Andrew Horowitz discusses the current state of the market with guest Cullen Roche, author of *Your Perfect Portfolio*. The conversation delves into employment reports, market disruptions, and the shift from growth to value investing while offering profound insights on portfolio construction.
Key Topics Discussed
- Market Updates
- Solid Employment Report: Indication of economic stability.
- Tech Disruption: Notable companies that were once disruptors are now facing challenges.
- Growth vs. Value Shift: A significant rotation with value stocks outperforming growth stocks recently.
- Cullen Roche's Profile
- Founder of Discipline Funds, focusing on low-fee, diversified portfolios.
- Areas of expertise include global macro portfolio construction and behavioral finance.
- Background in asset management with a focus on risk management and investment strategies.
- Market Analysis
- Disruption in Tech: Companies like Upwork reported poor earnings, showcasing vulnerability to AI advancements.
- Value vs. Growth Performance:
- Year-to-date performance shows large-cap value up 5.5% while large-cap growth is down 4.5%, indicating a 10% spread in favor of value.
- CAPE Ratio Insights: The current CAPE ratio for the U.S. is significantly higher than for Europe, suggesting a potential valuation disparity.
- Investor Psychology and Behavioral Risks
- Roche emphasizes that behavioral risks can outweigh market risks.
- Investors should be cautious about chasing performance trends, as this can lead to suboptimal returns.
- Portfolio Strategies Discussed
- Diversification Importance: Emphasized the necessity for a diversified portfolio to mitigate risks.
- Defined Duration Concept: Assigning time horizons to different assets to align them with financial goals. For example, understanding that the stock market's effective time horizon may be longer (e.g., 14 years for certain investments).
- Behavioral Discipline: Investors should design portfolios that they can stick with, avoiding the temptation for constant rebalancing based on market performance.
- Discussion on AI Impact
- AI's rapid evolution may disrupt various sectors, but it’s not entirely clear how this will affect employment long-term.
- The conversation covers both opportunities and threats posed by AI advancements in financial services.
- Cullen Roche’s Book: *Your Perfect Portfolio*
- The book provides an overview of various investing strategies and emphasizes that there is no universally accepted "perfect" portfolio.
- Roche highlights the importance of individual investor preferences and circumstances in portfolio construction.
Conclusion The episode concludes with a reminder of the importance of understanding personal financial goals and the necessity of a diversified investment strategy that aligns with individual risk tolerance and time horizons. Andrew encourages listeners to consider restructuring their portfolios in light of current market conditions and to remain engaged in their investment strategies.
Additional Notes
- Stocks Mentioned: INTC, UEC, IONQ, CEG, OKLO, NXT.
- Recommendation: Listeners are encouraged to explore Cullen Roche's book for a deeper understanding of effective portfolio strategies.
For more information and detailed insights, visit [The Disciplined Investor](https://thedisciplinedinvestor.com).
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOMarket Reflections: Shifts and Disruptions
2:13 to 4:20
Andrew reflects on recent market shifts, emphasizing the importance of portfolio evaluation in a changing economy.
“It's Andrew Horowitz, and thanks for joining me this week and every single week talking about money and finance and everything in between to try to make you a little bit more, well, financially stable, secure, and free.”
AI Disruption: Risks and Market Responses
4:20 to 8:14
Discussion on how AI is disrupting various sectors, affecting market valuations and investor behavior.
“On that Friday when the Dow Jones Industrial Average blew out over 50 ,000.”
The Value vs. Growth Debate
8:14 to 9:50
Exploring the current spread between value and growth stocks, emphasizing the importance of diversification.
“They're on a five-day quote basis, meaning you want a quote from Dell for a particular project, it's only good for five days because prices are changing so quickly.”
Market Conditions and Historical Perspectives
11:10 to 14:00
Cullen Roche discusses current market conditions, focusing on valuation metrics and historical data comparisons.
“but he founded Discipline Funds to help investors obtain access to low fees, diversified portfolios that helped him stay the course and meet financial goals.”
CAPE Ratios: A Comparative Analysis
14:00 to 18:45
Explore the CAPE ratios of Europe and the U.S. and their implications for investment decisions.
“And so, like specifically when you look at the current environment, I mean, the CAPE ratio, for instance, of Europe right now is about 22.85 versus the United States is 39.21.”
Understanding Sequence of Returns Risk
18:45 to 21:38
Learn about the importance of sequence of returns risk and its impact on investment outcomes.
“And we're kind of starting to see that, actually.”
The Role of Rebalancing in Market Dynamics
21:38 to 27:58
Discover how portfolio rebalancing influences market movements and investment strategy.
“The thing I was going to talk about, too, and I would like to know your opinion on this, my theory that this is kind of a loosely put together, like this makes sense from a basic standpoint.”
Global Portfolio Advantages
28:00 to 29:00
Learn how a global portfolio can provide dollar hedging without gold.
“But the more important thing is for a domestic investor, you're getting a very specific type of dollar hedging where you didn't even have to own gold in the last 24 months to get a dollar hedge.”
AI Disruption in Various Industries
29:00 to 31:00
Explore how AI is affecting traditional disruptors and their markets.
“there's a lot of discussion about AI, right?”
The Seismic Shift of AI
31:00 to 34:00
Understand the implications of AI development on employment and industries.
“Schumer is a, he's involved in the, the kind of on the ground and the whole AI ecosystem.”
Show all 20 chapters
Consumption Cannibalism and Productivity
34:00 to 37:00
Discuss the relationship between AI, productivity, and potential job loss.
“This whole thing, Colin, is I call this, I've been calling this for years.”
Exploring 'Your Perfect Portfolio'
37:00 to 38:40
Delve into the key concepts and strategies from the book, 'Your Perfect Portfolio'.
“That's what people are freaking out about.”
History of Portfolio Strategies
38:40 to 42:00
Learn about the origins and evolution of various investment strategies.
“Boy, I learned a lot about all of these different strategies.”
The Myth of the Perfect Portfolio
42:00 to 45:30
Explore the idea that there is no universally accepted optimal portfolio and why it's crucial to find one that suits individual needs.
“but wasn't really so popular throughout all of history.”
Behavioral Risk vs. Market Risk
45:30 to 47:20
Delve into the impact of behavioral discipline on investment outcomes and portfolio management.
“of you in your 20s with like a dating app for portfolio swiping left and right.”
The Flower Garden Portfolio Metaphor
47:20 to 51:00
Learn about the importance of diversification in portfolios through the flower garden analogy.
“go to where the grass is greener and you're buying, you know, a lawn that is actually on the verge of dying.”
Defined Duration in Portfolio Planning
51:00 to 55:30
Gain insight into the concept of defined duration and how it can enhance financial planning.
“you know, that's going to be the kind of thing, and we want to call it old weather, but I call it my flower garden, that we can kind of visualize something in bloom at any given time of the year.”
Understanding the Perfect Portfolio Concept
56:00 to 56:24
Learn about the importance of aligning portfolios with specific financial goals.
“But what is the underlying goal of the instruments in there?”
Reflections on the Guest and Future Episodes
56:44 to 57:08
Hear the host's thoughts on the guest and plans for future discussions.
“Appreciate you coming on and imparting all this great knowledge as well.”
Investment Strategies and Services Overview
57:08 to 58:03
Explore the various investment strategies and services available to clients.
“Make sure to go over to thedisciplinedinvestor.com.”
Transcript
Automatic transcript. May contain errors.0:00This episode is brought to you by Interactive Brokers. And ask yourself something. Will the year-over-year change in the US CPI exceed 2.6 % in February? At IBKR Forecast Trader, the yes recently priced at 48 % and the no at 50%. But markets move fast. Forecast contracts let you turn your views into trades on future events like the economy, climate change, and politics with simple yes-or-no prediction-style contracts. Explore trending data, spot the trends, and if you get your prediction right, you earn$1 per contract at settlement. Plus, you'll earn 3.14 % APY on your investment with an interest-like incentive coupon.
0:42And you'll get$3 for signing up with IBKR Forecast Trader, which you could use for any purpose or to start trading. Forecast contracts are not suitable for all investors. Go to IBKR.com slash forecast and turn your views into IBKR forecast trader contracts today. Last trading day for this contract is March 11th. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast.
1:16Cullen Roche:This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz & Company, from seed through harvest, cultivating financial success.
1:35How's that for a pretty solid employment report? The tech disruptors are getting disrupted. Growth versus value and abrupt change. And our guest is Cullen Roche, author of the bestselling book, Your Perfect Portfolio. all this and much more on episode number 960 of the Disciplined Investor Podcast.
2:12Hey, hey, hey, and welcome to the Disciplined Investor Podcast. It's Andrew Horowitz, and thanks for joining me this week and every single week talking about money and finance and everything in between to try to make you a little bit more, well, financially stable, secure, and free. That is what we're trying to do here each and every week. Last week, well, that show was packed with information, wasn't it? If you haven't listened, we talked about Software-Mageddon. We talked about the fallout from AI disruption and other sectors that happened. And we'll talk about that as well this week. We dug into precious metals.
2:49Oh, we talked about diversification, which we're going to have a little bit of a discussion with again, also with our guest today because he's all about that. And there's a great response from that discussion. I got to tell you, thank you all for your emails, your comments. And as I mentioned, now probably more than ever in the past year or so that I can think of is a real good time to start getting down and dig into your portfolio. Consider taking a very hard look at what you own. The reality is that things are a little bit different. We're seeing a very big change in the leadership in the markets.
3:29And by the way, many of you wrote me. You went over to the Disciplined Investor. You clicked on either the Ask Andrew or anything else that was in there. And you said, hey, what do you think about this? and that you were going to get down and start looking at this. And you're going to roll up your sleeves and you're going to get involved. Yes, some of you asked me to help you, which is fine. I could do that. But what is really great is that you're taking this thing seriously because we live in a world and an environment and an economy that is ever-changing. And that being said, we need to be present to all the things that are happening, Not lazy.
4:08Not just ho-hum. So what's different this week? What's different this week than we had in the past? Well, last week we had that monster move like a week and a half ago. On that Friday when the Dow Jones Industrial Average blew out over 50 ,000. And now we turn around and where are we today? Well, the VIX tipped above 20 this week. We saw this massive rotation that is taking hold, right? We saw that the move from growth to value, we see that potentially we have some type of military action in the Middle East, maybe, maybe not, I don't know. And that's probably the reason why crude has been moving up so nicely in the past few weeks and why commodities, and in particular, even with gold and silver and platinum and palladium doing what they're doing, has been holding up really well.
5:00are we going to go into a war, a conflict in the Middle East again? I don't know, but the markets seem to be sniffing out something. But I thought that the real under-the-radar situation that's going on that ended up being, I think, above the line, like front and present, right there in front of our eyes, no need for any kind of specialty glasses, night vision, or radar, sonar, anything, was all about disruption. This disruption that's going on. You know, we saw some of the companies like Upwork. Horrible earnings outlook. Horrible numbers. Stock caved down 25%. What kind of work is done at Upwork?
5:45To give you an example of what's going on, well, pretty much almost anything that can be done on a computer, right? Like software and web development. They do things like creative design work. They do translation, writing, editing, marketing, SEO, sales. They do things like accounting and legal. They do possibly get hired for somebody to do admin and customer support. this is the poster child for something that can be disrupted with the likes of artificial intelligence of where we are today. We don't have to get into the next levels of where they are. They can be disrupted today. And they're seeing that, this company apparently on the bottom line.
6:30And that is why we're seeing other companies get so skittish in the current market environment that we're in now. In fact, we also saw this week another potential, although I don't think this was, I think this was overdone a bit. We saw a new financial AI that could take a look at tax returns and other financial forms and make informed tax decisions. And that sunk the companies like Schwab, Morgan Stanley, and there was a few others that got clocked. With all this forced explanation that we've been hearing from the companies that are embracing AI, that they're not going to lead to job layoffs and all this.
7:14Okay, I'm calling BS. I have before, I'm going to say it again. And while AI, by the way, may not dislodge an Etsy creator or crafter, whatever they're called. Maybe someone with very specific mechanical skills, although there are some robots coming, Some robots are already there. There are plenty of other areas that can be impacted. There's no question about this. So investors are selling first and they're asking questions later. That's what's happening. We saw the likes of Dell. Highflyer recently. Everybody loved it. I like Dell. Why? Because they're selling machines. They're selling a lot of them.
7:58Problem is, they got some problems. The cost of chips and some of the materials that go into the device that they're making have been so elevated. Not that we have any inflation, by the way. They've been so elevated. They've been absorbing much of this cost. They're on a five-day quote basis, meaning you want a quote from Dell for a particular project, it's only good for five days because prices are changing so quickly. This company has a huge footprint in the AI space, in the tech space, but they're getting smoked recently because of all the extra costs that are going into this. Pretty interesting time.
8:35We're seeing that there's a huge amount of capex that's going on. Investors are captivated right now. Maintaining that generally bullish tilt. A couple of days down, then boom, right back up, right? Now, is that going to be around forever? I can't tell you. But what I do see is the moves have been massive rotations for now. Huge gains in areas that have underperformed, outperformed, putting into areas that have underperformed. And this is why we're seeing this massive spread. For example, value, staples, financials, energy versus growth, tech, consumer discretionary, biotech. 10 % spread there right now.
9:1910 %! The value on the large cap side, you look at the Russell 1000, up 5.5 % year to date. the growth down 4.5%. That's a 10 % spread. Wow. In only a short period of time. That is amazing. This is the whole point of diversification. That's why we're going to get to talking with our guest in a minute. We're going to do that because I think there's a lot we're going to learn here today. Before we do that, I want to talk about, again, interactive brokers because, listen, Listen, I know, you know, you do a great job. You research your investments, right? You analyze markets, you manage risk. But did you research your broker?
10:06In 2025, IBKR clients outperformed the S &P, the S &P 500. Retail clients, well, they average about 19.2%, while hedge fund clients average about 28.91 % compared to the S &P 500 index of 17.9%. IBKR's, here's why. You got to really understand what's going on. IBKR's lower trading costs, their competitive rates, efficient execution, and access to more than 170 global markets helped investors keep more of what they earn and put more capital to work. Makes sense. Over time, your broker is important. The broker you choose makes a difference. Interactive Brokers, member SIPC. If you care about performance, find out why the best informed investors choose Interactive and Brokers at ibkr.com slash 2025.
11:07All right, let's get to our guest. Get to our guest, Colin Roche. He was on years ago. We'll talk about that. but he founded Discipline Funds to help investors obtain access to low fees, diversified portfolios that helped him stay the course and meet financial goals. His primary expertise includes global macro portfolio construction, quantitative risk management, monetary economics, financial accounting, and behavioral finance. That's a lot. And prior to establishing his own business, he worked at Merrill Lynch Global Wealth. We worked on a team overseeing about a half a billion dollars in assets.
11:43and upon leaving there, he managed a private investment partnership which took advantage of reporting irregularities ahead of major corporate events. So he's been on the show before. Let's welcome, let's get into it, let's talk to him because I'm pretty excited about his book and what he has to say. So, Cullen, how are you? I'm doing great, Andrew. Thanks for talking to me. Yeah, you know, you've been on the show twice before and the last time was August 2023. 2023. We discussed asset allocation. We talked time horizon. We talked rich risk. Back then it was the Fitch downgrade. Uh, we talked about cash as an investment, discipline investing.
12:22That was in 23. The time before that was way back in 2015, by the way. I don't know if you remember that. You don't like talking to me very much. I know. I was looking at all these delays. What's going on? We talked about China, robo. We were talking about robo-investing back in 2015. Yeah, remember that? Remember the robo-advisors? Yeah, yeah. Boy, I guess they didn't kill all the financial advisors. I know, right? The death of this or that industry is well overblown in all occurrences. So let's talk about, I want to start with the current market conditions, some things that are going on from your perspective, right, from your unique perspective.
13:02And then I want to talk about your book. I want to get into it because I have a lot of things after going through it and reading it. I have a lot of dog ears on, you know, bend downs and sticky notes and things shoved in this thing. But let's talk about current market and valuations. Yeah. How should investors think about, I don't know, you want to call it, I'm going to say high valuations. I'm going to say the word high valuations. They are. In the context of their portfolio. Yeah, I mean, this is, I think, especially from a valuations-based perspective, this is one of the most interesting and difficult times to allocate assets.
13:40Because the thing that is really interesting to me about this environment is when you look at especially things like the historical CAPE ratios of the market, the market is really all over the place. It's very, very differentiated across different regions and even different styles and sectors of the economy. And so, like specifically when you look at the current environment, I mean, the CAPE ratio, for instance, of Europe right now is about 22.85 versus the United States is 39.21. And so, and ours, by the way, just to put a perspective, if you look at a chart, this goes back to like 2000. And what was it like?
14:21It was back like 10 years ago or so that, and then, and then we rolled over hard. Right. Yeah. And so the really interesting thing about this data, though, is that the before basically before the financial crisis, these two regions and really most of the world, it correlated very, very closely. So like in 1999, during the tech boom, the CAPE ratio, which this is the cyclically adjusted P ratio, which is like Andrew said, it's the it's basically the trailing 10 year cyclically adjusted P ratio of the market in Europe in 1999. it was 42 in the usa it was 45 so this was really tight back in in 1999 during the tech boom and then valuations collapsed they fell a lot during the the financial crisis of course and and the post-tech bubble era but then since then there's been this crazy crazy divergence where the united states has massively outperformed everything that's been largely tech driven and now you have this huge disparity where Europe looks very, Europe and really the rest of the world looks very attractive from a valuation-based perspective.
15:28The United States looks incredibly expensive, especially on a relative basis. Yeah, that's what I was going to ask. Is the word relative going to come up here? That was an important thing because you talk about 22, which is not low either from a Cape when we look at Europe, right? When we look at the European Cape, it's not light. It's just relatively so much less. In fact, when we look at value and growth, Growth has been smushing value. At the top of the show, I talked about, there's like a 10 % differential this year so far, year to date between large cap growth and large cap value. Large cap growth is up 5.5%.
16:03Large cap value is up 5.5%. Large cap growth is down 4.5%. And so I'll tell you how I kind of think about this and how I compartmentalize this stuff, especially what I'm talking to clients and other investors. I think of this stuff very specifically across different time horizons, where I like to try to quantify actually what a financial planner would call it the sequence of returns risk, meaning the way that the returns are likely to materialize in the future. Because I think a mistake a lot of people make with high valuations is I think they assume that future returns necessarily have to be much lower or maybe even negative.
16:43And I don't necessarily think that's true. The way I would frame this is I would say that the risk of a much bumpier ride is elevated when valuations are high because valuations are functionally, they're basically just expectations. So the multiple that's built into the expected earnings going forward is very, very high in the current environment. And so if you get any sort of disruption to those expectations, you get a lot of volatility, whether that could be, you know, if the AI trade doesn't materialize or some unknown event transpires, a recession or something like that, you get a lot of bumpiness in the future way that the returns will materialize.
17:24And so in a year like 1999, when valuations are super high and expectations are really high, you have crazy high sequence of returns risk where the interesting thing about buying the market, if you bought the exact peak of the tech bubble back in 2001 or 2000, the return since then has actually been 8 % per year. You've done really, really well. But of course, you went through a 15-year period of horrific downturn to get to that point. And so your sequence of returns risk was really, really terrible in there. And so I would frame it the same way now, where if you are loaded to the gills with AI and nothing but US technology and growth stocks, you may not necessarily generate lower expected returns, but you should expect the volatility that comes with those returns to be much higher than it would be on average compared to, say, an environment where valuations are much more reasonable, or especially if you're buying the rest of the world, European stocks or emerging market stocks, the likelihood for a less volatile ride in those parts of the world, a better risk-adjusted return, as a financial nerd might put it, is probably a more probable outcome.
18:45And we're kind of starting to see that, actually. The financial markets right now, I mean, the last year, God, four and almost double domestic returns. It's unbelievable. Right now, it's continuing. markets and small caps international are absurdly it's like yeah let's just stop and call it a year yeah i mean you could i mean foreign the foreign markets right now what are they up uh you know 10 11 percent already so you know you're seeing this in the domestic u.s market is up you know one two percent so you're seeing this huge you know and it's not i don't know a lot of people have been calling for this to occur um you know for a long time and it's looked very very bad but it's all of a sudden it's happening very, very quickly where the, you know, those relative, um, CAPE ratios might compress, they might compress a lot more going forward.
19:37So there's two things about that. And I want to tell you about one theory I have, and I want to dig into a little tidbit underneath the surface of what you just talked about and just bring it out. I want to kind of like tease it out, if you will. And you talked about the idea that the CAPE ratio, um, with regard to, um, the expected returns, they talk about like, oh, it's elevated. And that means we're going to have negative returns. Everybody's like, oh, first of all, I think we both would probably agree that trying to market time on valuation is an impossible task. You can't do it. Secondly, the thing that you I think that we want to talk about just briefly is this idea where most people believe that when we're overvalued means we have to have some kind of significant corrective action.
20:17Negativity right across the board somehow or within a sector to bring us down where, in fact, the reality is we don't necessarily have to do that. we could just temper the returns. So instead of getting, I'm just gonna pick a number, the 25 % a year that people are expecting from tech stocks, they may only be a mere 8 % per year for the next few years. And I think that's the exact right way to frame this is that if you have, let's say 25 % returns going back the last 10 years with, let's just say, 20 % volatility or what the statisticians would call like standard deviation. I think going forward, if you got, say, 10 % returns with 25 % volatility, that would not necessarily, that would not surprise me at all to see an environment like that.
21:12And that's what that results in. It results in a worse risk adjusted return. It doesn't necessarily mean that you generate bad returns. 10 % is still a fantastic outcome. Tremendous, tremendous. But I think people should look at this sort of an environment where if you're loaded to the gills with AI stocks and growth stuff, you should expect some bumpiness along the way there and higher bumpiness than we would regularly see on average. The thing I was going to talk about, too, and I would like to know your opinion on this, my theory that this is kind of a loosely put together, like this makes sense from a basic standpoint.
21:48You know, you take down technology in the U.S. by 2%, right? You have this major run over the last year and two years, three years, five years, pick it up, whatever you want. Instead of it being a 15 % position in your portfolio, now it's 18%. I got to take 3 % down. 3 % down in that particular environment is a chunk of money that now all of a sudden they're going to move. Where are they moving it? They're moving it to Europe just for a simple rebalance. That 3 % that was taken out of technology is a huge number, right? Because it's, you know, if I'm saying that's going to now be pushed into these lower valuation, thinner traded, less liquidity stocks.
22:25And I wonder if some of that, when you start moving that massive money that you're taking from into the smaller companies with less liquidity, if that's one of the reasons that we're seeing such a dramatic move in some of the EM, small cap international and developed international. Yeah, I think that totally makes sense. I think that you're, you know, and gosh, I mean, not to get into like the geopolitical aspects of all this, but you're starting to see, you know, this whole like sort of dollar debasement narrative around the globe and the United States has become, you know, we're obviously not isolationist, but we're coming on a relative basis, a little more isolationist.
23:06isolationist. And so I think the rest of the world is looking at their own asset allocation, and they're moving away a little bit from dollar-denominated assets. And that may be part of it is political. Part of it may be just a sensible rebalancing mechanism that a lot of, especially foreign investors, are going through where they look at the valuations in the United States and they're saying, you know what, we're going to buy a little more international small cap and whatnot, and just to diversify the portfolio. And I think that makes a lot of sense. And, you know, but I think in terms of the thing for me that I try to communicate, especially to clients, is that I really try to talk about this over time horizons, where, like, I would say that right now, you know, going back to that kind of sequence of return risk concept, I would say that the time horizon over which you can reasonably predict the technology sector now to generate a stable return is longer.
24:03You might have to be more patient with the way that technology generates its returns versus something like if you're buying like domestic value or if you're buying international stocks, I think the time horizon of those instruments is a little shorter. So if you're someone who is hypersensitive about the short-term moves of the market or even inside of like multi-year time horizons, the growthy stuff, the tech stuff, the concentrated parts of the market, they're going to test your patience. And so I think that that's a really solid argument for if you're really time sensitive about this, you need to have more diversification in your portfolio because you're just going to get really bumpy returns, I think, from things like the NASDAQ 100 and the more growth oriented parts of the U.S.
24:51market. You know, this last six months, and I'll stretch it to a year, has been the year of, oh my God, they're finally right. Right? Yeah. You look at Peter Schiff, who is calling for the dollar debasement and the whole idea that, well, it's more than a debasement. It's more than a dollar evaporation in his mind. But he was just talking about gold and silver for years. Nothing happened, right? Yeah. The guys that I talk to all the time from the various, you know, the Goldmans, the JPs, all these guys that are kind of trying to feed you some information here and there coming up with, you know, This is the year of the emerging markets.
25:26Like, okay. Meb Faber. You know Meb. He's been preaching for how long? Which he's right, by the way. I'm not taking anything away from Meb, but I love him. But he's been talking about and trying to educate people for years about, are you kidding me? You have how much of your investments in the U.S. only not in the rest of the world where the rest of the world is this? The funny thing is it's the year of things turning around or maybe just one thing just not working. Gold and silver. Interesting, right? You know, we see this massive volatility. We see that parabolic move that I saw as an exhaustion gap that one day that it went up.
26:04I don't know what it was. Some ridiculous number to the top end of where silver was. I think SLV ETF was somewhere about$125 a share or something like that. And is this still something that's viable, important? or is it just another asset that has been exploited to a point that's not even investable? Yeah, I mean, the way I would describe this is it happened gradually and then all at once, you know, with all these different markets. So yeah, I mean, it's interesting. I mean, I think it's a lesson in why diversification matters to different investors. And so I don't know for me international investing is more so about currency hedging so it's interesting to talk about this in the framework of the the dollar debasement trade because and this is one of the things i talk about in the book is i i display the data over which the the different currency regimes impact different styles of returns across different markets across the globe and what you see is when the dollar goes down foreign markets beat the pants off of u.s markets and so for me it's not so much am I trying to pick where is going to be the best performance for me owning international stocks is really a it's an exercise in dollar hedging basically that you get a you know you don't necessarily have to just follow the peter shifts of the world to get a dollar hedge you you can actually hedge your dollar exposure to a large degree by owning different types of equities and so when the when the dollar goes up a lot and the U.S.
27:37companies are beating the pants off of foreign companies, you know, you get you get periods like 2010 to 2024, whatever it was that period where the US stock market just annihilates the foreign markets. And then when the dollar reverses, and if it reverses in a big way, like it has in the last sort of 18 months or 24 months, you get this huge seismic shift in a reversal where the foreign markets then start to beat. But the more important thing is for a domestic investor, you're getting a very specific type of dollar hedging where you didn't even have to own gold in the last 24 months to get a dollar hedge.
28:15You just had to own a global portfolio of equities because you got huge, huge outperformance from that international slice. You know, I talked about that last week on this very show. I talked about looking at your international EMM, but I said, make sure if you're trying to get your biggest bang for your buck, or to be, in my opinion, to an extent. There's different reasons for different things, but look at whether or not your portfolio, whether it's in the foreign bond, fixed income slash or in equity, is it dollar hedged? Because you could, a lot of times you don't know, right? And all of a sudden you're like, ah, that's great.
28:48I got this dollar going down. I got the, no, you are dollar hedged. Yeah. Blew out 5 % of your return right there. So be careful when you're looking at this. Let's go on to one more thing and then I want to talk about the book. there's a lot of discussion about AI, right? You know, we've been seeing this, and I've been talking about this too. The disruptors have been disrupted. That is what I am seeing right now. The idea that the Zillows, the DocuSigns, the Upworks, you know, you pick the names, right, out there, which are out there, the Asanas. These are the, even to a degree, the big guys, right?
Read the full transcript
29:32The big, like Salesforce. So you have all these companies out there that were the disruptors, that were, I don't know, we'll call it, I want to call it first-level tech efficiency
29:48and productivity beneficiaries. Now, all of a sudden, things are a problem, right? We see industry after industry all of a sudden freaking out and flinching with AI. In fact, just earlier last week, there was a discussion from altruist.ai, which where you could upload your tax forms and a few other forms and all that. And voila, they do all this work for you. And some of the guys, like I was talking about this at the beginning of the show, Schwab, Morgan Stanley, a few others got just beat to crap in a day. is ai generally speaking um from our portfolios what how should we be looking at this gosh i mean this is one of those things that it's very it's very very hard to decipher what is going on because the and this is part of the problem with the the world today is that things are changing faster than they've ever changed.
30:50And, you know, I was reading this piece. There's a great piece by Matt Schumer called something big is happening. Uh, people should Google it and read or read it. It's on Schumer's website. Schumer is a, he's involved in the, the kind of on the ground and the whole AI ecosystem. And he talks about how there is this seismic shift that's going on that really has not even started to impact things. He basically was saying that, like, you know, in short, the AI is starting to rewrite the code for the AI. And so he's a developer involved in writing AI where all of a sudden the people developing the software that is transforming everything are no longer, they're basically irrelevant inside of developing the software itself.
31:34And so you can start to see this world where when people who are that involved in actually developing the software become irrelevant, well, what does it mean for the rest of us? where this software eventually just starts doing all of the other things around the world. And I don't know. I mean, I think that there are pockets that are going to be disrupted and probably eliminated. And that's the scary thing from an employment perspective is that this isn't like, you know, the innovation of like the car is something that a lot of people would look at and say like, oh, well, this is going to, it's going to ruin all of the mail delivery services.
32:10and the Wells Fargo delivery service from horse and carriage is gonna go away. And that's a really interesting way to look at all of this because the adoption of the car was different than today because it took, God, it took really like 50 years for cars to get really widely adopted. It wasn't until really like people came back from World War II and even like Vietnam and then really started to, the average American and then really owned a car in a widespread manner. This is happening much faster. So this is different in that sense. I don't think I buy into quite the narrative that this is gonna like destroy the employment market.
32:53And because there's kind of a catch 22 in there where the paradox in all of this is that if the AI start really destroying a lot of jobs, well, the demand for AI then goes down because people won't be able to afford to buy all these crazy subscriptions to, you know, all these different services. And so there's kind of a paradox in there where the, you know, unless you have somebody else coming in and fill the spending void, you know, if you get enough employment, well, we reach a point where people aren't even buying this technology in the first place. So, and the other thing is like, this is still very, I think, sort of niche in terms of its impact and the way it's going to materialize out over different sectors, because until this becomes something that is like for me, the moment where this becomes really scary is when, when I wake up one morning and I see robots walking across a construction site, that is the scary moment where you kind of know that it's going to happen.
33:50I have no doubt. I think it's going to happen in our lifetimes, but you know, I, that's really scary because at that moment, those robots are doing even the most manual of labor. That's the one thing. That's the last thing. This whole thing, Colin, is I call this, I've been calling this for years. When we saw some of the productivity and efficiency come out, consumption cannibalism. Whereas you have a robot or you have a, let's talk about a robot in an Amazon warehouse, right? They don't need to take breaks. They don't need to have a vacation. They don't whine to HR, right? Nobody's harassing them.
34:28Nobody, they don't need to ask for a raise. They don't need to take a lunch break. They don't need a smoke break. You know, this is where all of a sudden this happens and we see all these potential things. Now, what happened was productivity got better. More people made more money. There was more consumption. I get it. But this is kind of like that. I see this as a little bit of the tweaking of the potential for that consumption cannibalism where all of a sudden people may be out of work in certain areas or not necessarily. Look at, for example, graphic artists. I mean, man, you can go to Grok and ask just a very simple thing.
35:04It'll do a whole image for you. That's beautiful. Beautiful. You used to have to send that out. You wait to the guy, tweak it up. You send it to Upwork, which, by the way, stock was down, I don't know, 25 % this week on just piss poor earnings. You could do something like, how about this? I look at your book. I read. I'm like, hey, Chapter 12, the counter-cyclical rebalancing portfolio. Chapter 13, the Bernstein no-brainer portfolio. Hey, I have an idea. I'm going to feed that into AI and say, do me a favor, analyze this, take your time. And I want you to spit out what is the most appropriate for this.
35:35And I want you to help me work the rebalance on this on a regular basis quarterly. Yeah. You know, I'm just saying just something like that. You know, you wrote it, my friend, you gave it to us. You're, you're thinking about this. I think the exact right way where you're taking a creative approach to utilizing AI that I think these are the, those are the use cases that where people are going to actually add a lot of value utilizing this software. And, you know, it's the, it's, it's hard. It's impossible to predict where all this is going. I think that, I think if I was a, if I'm a creative entrepreneur utilizing this software, the boy, the world is your oyster.
36:19I mean, I think that the upside is limitless for those types of people who can really creatively use things like this. If you work at like a big clunky fortune 500 company, you know, punching tickets, you know, that those jobs, those companies actually weirdly, I think are much, much more at risk than like, cause that's the, that's the thing. I think AI is the ultimate disaggregator. It is the ultimate decentralizer because it, it gives people who want to operate from a fully autonomous and sort of decentralized position a huge incredible value add potential so whereas this is much more disruptive for big big firms that are doing things that are very repeatable processes that these large language models are just really really good at doing and we're not even talking about eliminating those those jobs we're not even talking about uh inference or or no one near agentics yet right we're yeah we're getting there but can you imagine where where you deploy that.
37:17That's what people are freaking out about. Let me talk about the book. The book is called Your Perfect Portfolio. By the way, I don't know who picked out the particular texture for this cover, but it's very soothing. You got to get this book, and seriously people, get the book and just to feel the cover, if nothing else. But you got to do that. That's what the book is for. I call it good sleeping material. I made it very comfortable in case it puts you to sleep. So you can just fall asleep right on top of I could have this instead of a fidget spinner. I'll just kick the book. No, no. Great, great stuff.
37:51The book is called Your Perfect Portfolio, The Ultimate Guide to Using the World's Most Powerful Investment Strategies. We got some good commentary from Morgan Housel, which, by the way, are you good friends with Morgan? Because I want to get him my show. He was on years ago. I haven't been able to. Somehow we're not connecting. I'll ping him. Yeah, Morgan's an old buddy of mine. God, we were both lame bloggers back 20 years ago before anybody knew who either of us was. Morgan is just astronomically more famous than I am. He sold 10 million copies of Psychology of Money. Unbelievable, right? Unbelievable.
38:31But yeah, if you could do that for me. So let's talk about this. First of all, I'm going to ask you straight up. What did you learn from writing this book? Boy, I learned a lot about all of these different strategies. You know, the most, I think, educational piece for me was actually studying the history of all of the different strategies. Because it's funny when you talk about, so people kind of know, the book is sort of an overview of mainly 20 famous strategies. From either Warren Buffett strategy to like the Boglehead three fund strategy to factor investing to the all weather portfolio. All these different styles and strategies.
39:12And I kind of go through and I tear them all apart and I kind of try to objectively analyze them. But I also like rip through the history of all these. And so it was it was really cool, like looking back and really studying the history of what where did these strategies come from and why are they a thing and why do they work the way they do? And so like for me, I loved like going through the history of like the 60-40 strategy was really interesting. So that's 60 percent stocks and 40 percent bonds. and it was really interesting to kind of study the history of that one because it doesn't have an origin story kind of like a lot of the other strategies.
39:47Yeah, that's a good point. I was thinking about that just as you said it like because all these other ones have like a bit of an origin story who's famous for it. They have an origin story or a founder, some famous person who is attached to the strategy and the 60-40 doesn't and that one's interesting because 60-40 is arguably like the most famous and widely used strategy of all of the strategies. I'm taking credit. I'm taking credit. I invented 6040 and prove me otherwise, by the way. But yeah, it's weird because it didn't seem to have this origin story. And so I kind of, I don't know if I exactly got the history right, but I kind of traced it back to the Great Depression and, you know, the old Wellington fund that was created back then.
40:25And so it was, it was interesting because the origin story there, it actually like runs through, you know, not only the Wellington fund, but then, you know, John Bogle ends up running the Wellington fund at some point in his career through the 60s and 70s. And this materializes into Vanguard, which obviously everybody knows of Vanguard now. But the story there is basically that the fund itself was created right before the Great Depression. And the founder of it had been, or the manager had been burned in the past. And he created a more balanced type of portfolio, hoping that, hey, if I load this thing up with a big slug of bonds, if the stock market were to go down a lot, I wouldn't get as harmed as, say, an all-equity portfolio.
41:14And it's funny because the portfolio is built basically or implemented right before the Great Depression. It falls 40%, which is pretty catastrophic by most measures, but it did way, way better than 100 % stock portfolio, which fell 80 % plus during that period. And so it becomes kind of widely adopted because it creates this more balanced type of return. And it stood the test of time through World War II and the inflation of the 1970s. And then obviously in the last 40 years, the 60-40 has kind of become the gold standard in asset allocation to a large degree because it's just so diverse and so balanced.
41:51And so, but it was cool to kind of trace that back to the Wellington Fund and this more balanced type of asset allocation that now has become very, very popular, but wasn't really so popular throughout all of history. You know, it's interesting. You talk about, early in the book, you talk about, and I think you argue quite well that there's no universally accepted optimal portfolio. Even though the book is called Your Perfect Portfolio, right? There's no perfect portfolio per se. It's just out there on the shelf. I remember post the 60-40, And as we got into the Harry Markowitz, William Sharp, Brinson B.
42:29Bauer and Hood and, you know, pick your poison of who else, you know, DFA funds, all that stuff. I was like so engrossed with getting one more percent in the commodities. I think that will be perfect. You know, the efficient frontier and all that. And then one day I'm like, what am I doing? Like, seriously, it was like a year into this. I'm like, hold on a second. This is silly. One percent, even if I'm wrong, doesn't mean anything. That was the whole point. by the way, of these studies, right, of the major pieces, the white papers that were put out about all this. And I got kind of soaked up in this.
43:05But how did you kind of distinguish between a portfolio that's kind of uncomfortable versus one that's genuinely misaligned with who the people are that are investing in it? Yeah. Yeah. Well, I mean, that's the main message of the book is that there there really isn't a an overarching perfect portfolio. There's only a portfolio that's perfect for you. And so the you know, part of the one of the analogies I used in the book was to dieting and that there you know, there's all these interesting dieting studies. And one of them found that basically the there they studied all these different sort of fad diets.
43:46And what they found was that they all worked, but they only worked for people who stuck with them. And so, you know, that's one of the messages of the book is that, hey, here are a whole bunch of really good strategies. These will probably all work fairly well if you stick with them, but you've got to find the one that's right for you. And that's kind of the main message of the book is that we're all different. We're all unique. We all have different financial goals and needs, and you've got to find a portfolio that you can ultimately stay loyal to and stick with. And if you do, that portfolio will probably serve you pretty well, but you've got to find the one that's right for you.
44:22Because if you're incompatible with it, you know, it's kind of like finding a spouse in a lot of ways. That's the other metaphor I use in the book a lot is the, you know, finding a good portfolio is like finding a spouse and someone you can stay loyal to. And someone that, you know, you don't want to do, like, I spent a lot of my 20s having, you know, not real one night stands, but portfolio one night stands where I was constantly flipping and kind of tweaking and changing things, trying to optimize everything to, to make it better and better. And I finally realized like, Hey, actually I need to just find something that is good enough for me because perfect really is the enemy of the good in this process.
44:59And you have to find something that is just, it's good enough for you that is going to solve your financial goals, hopefully, and you stay loyal to it. And you got to make changes of course, on the fringes over time, cause your life is going to change and the portfolio needs to be rebalanced and, you know, reallocated to be consistent with the underlying strategy and you're changing goals across time. But you have to find a process, especially that is something you can really stick with and stay loyal to. And that that'll be your perfect portfolio in the long run. I have this envision of you in your 20s with like a dating app for portfolio swiping left and right.
45:36Exactly. That's that's pretty much who I was. And then and you know, the other thing is, I want to also put this analogy metaphor, depending on how you want to look at this. I don't remember which is which. You know, when you have people in the kitchen, there's some people that like to cook freestyle and there's some people that like to bake. Some people like to be like, I need a quarter cup of teaspoon, you know, 42 milligrams of whatever it is, right? And some people are like, hey, throw the garlic in the pan, throw the wine in the pan, you know, get it around, mix it up, throw some salt, get on the plate.
46:06So there's, but that person can't be the baker and the baker can't be that person. And if you ever try to do so, So you're probably going to be miserable. And then you're not going to want to do it. And that's exactly what you're saying with this. So let's talk about – you talk a lot about behavioral discipline, investor psychology. And I think if I – I guess when I kind of wrote this down because I was taking notes, I was reading, you often emphasize that behavioral risk is often more damaging than market risk, which is kind of an adjunct of what we're talking about here, right? So which portfolio structures do you look at as maybe doing the best job of protecting an investor from themselves, right?
46:54Not just from volatility. Because that's what you're talking about, but I want to expand on that. Well, that's the hardest part about all this, I think, is that people are constantly chasing performance and looking at where the grass is greener. And those shifts oftentimes occur at the worst possible times. And so one of the things I emphasize in the book is that don't, don't spend so much time chasing to where the grass is greener, because oftentimes you, when you, you know, you, you go to where the grass is greener and you're buying, you know, a lawn that is actually on the verge of dying. And then you have to, you know, you're going to realize that lawn is dying.
47:30You're going to look across the yard and you're going to see, you know, grass growing where you just were, and you're going to flip back to that one. And you want to avoid that process because it, it just results in suboptimal returns because you're constantly chasing to where the returns are actually the worst and the risks are the highest. And so, you know, for me, it really does depend. I mean, the portfolios that are more diversified that do sort of a more of a sort of, I guess, an all weather style of investing strategy where you sort of you have to acknowledge that the grass in some part of your portfolio is always going to be brown.
48:04And that's actually not necessarily a bad thing. I think a lot of people look at their portfolio and they sometimes think, well, gosh, you know, the the foreign equities in my portfolio really just they've done so dreadfully compared to the U.S. equities. I'm just going to I'm going to ditch them completely. And then you get, you know, years like the last couple of years and the the international piece blows the pants off of the the domestic piece. And you realize, ah, I should have just, you know, I should have watered my own lawn. I shouldn't have just been jumping around. And so I think that's sort of all weather style strategy where you're very broadly diversified.
48:37And that, you know, for some people that might just be stocks and bonds across very, you know, structurally different time horizons. It may be something more like, you know, the permanent portfolio where you're buying something very intentionally to own things like gold or commodities. And you're hedging against very specific regime structures where you've got kind of this all weather portfolio that you've got to get into something like that, knowing that in the long run, in totality, it'll serve you very well. but there's going to be times where pockets of that portfolio do really poorly. And that's one of the, it's one of the big lessons from diversification is that, you know, one of the quotes I love from Brian Portnoy is that good diversification is learning to hate some of your portfolio all the time.
49:21And that's really true. It's that you're, you're never going to find a portfolio where the whole thing is performing really, really well all the time. And, and that's perfectly fine. And so again, kind of going back to that perfect is the enemy of the good is that you don't necessarily want your whole portfolio to be perfect all the time, because it probably means your portfolio actually isn't that diversified. Cause that's one of the things you have to acknowledge is that when the stock market gets really hairy and starts going down, you need, if you, if you're going to remain comfortable inside of that thing, you need other hedges and those other hedges are, they're not going to perform as well.
49:58When the stock market is rip roaring and doing really well, those hedges are not going to be doing well. And that's just the tradeoff that you have to accept in part of this process. So I'm going to give you something for your next book, something that I wrote about in my first book, which is the flower garden. So I've been talking about this for, I don't know, 15 years. And that when we build a portfolio, you want to look at it as a flower garden, similar to your brass. But in that flower garden, if you have things that only pop up once a year and you fill your whole garden with that, they look beautiful for a month or two.
50:27But then you just got this arid, dirt-ridden patch of dry that goes into mud. And it looks horrible. But then it pops back up. That's great. Whereas if you had roses, heliconias, and impatience that come up, and you have annuals, and you have semi-annuals, and you have evergreens, by the way, which are like your money markets, right? Never changing color. Something is going to hopefully pop at any given time. Now, unless we have a hurricane that comes or a tornado that rips through everything, like tornado 2022, you know, that's going to be the kind of thing, and we want to call it old weather, but I call it my flower garden, that we can kind of visualize something in bloom at any given time of the year.
51:10Yeah. Well, hey, that's why I need inside plants. Exactly. That's why I need fake plants. I like that. The flower garden strategy. Yeah, that's what we do. All right. I need to add a chapter. You want to write it for me? Yeah, I've written it right. I I can give it to you. We can just bolt it on the back. So again, in this book, which by the way, you can go over to thedisciplinedinvestor.com for show notes, episode number 960. And the link right to Amazon will be right there. So you can grab the book. I encourage you to do so. And also, by the way, tells you more about Cullen and founder of the Disciplined Funds, which is missing a D clearly for the Disciplined Investor, but there is no relationship with us.
51:52But he also does a grouping of ETFs called the Discipline Funds. But I want to ask you about that. So one of the things you talk about, and then I think it reflects also in your actual real life investment strategy, is the idea of defined duration, right? Could you explain exactly what that is? yeah so really i'm sort of extending the idea of bond duration to other instruments specifically mainly the stock market i think the stock market is very hard for people to remain disciplined with in large part because people don't understand the time horizon over which they should judge the stock market and so what i basically have done with this methodology i've created a way of actually trying to assign a time horizon to the stock market so to to use kind of a simple example, if you were really trying to quantify like what a financial planner would call the sequence of returns risk inside of this instrument.
52:52And that's the risk that if you were to buy a 100 % allocation in the stock market today, and let's say it fell 50 % tomorrow, what is your temporal risk in that instrument? And so if you were to apply something like a CAPE ratio and assume the, let's just assume the future expected returns of the U.S. stock market are 5 % in real terms. Um, well in that scenario, if the stock market were to fall 50 % and generate a 5 % annualized return in real terms from there, it would take about 14.2 years for you to break even. And that's your point of indifference. Basically that's the time horizon over which that instrument has no sequence risk for you anymore.
53:32And so when you embed this into a broader sort of like bond duration methodology, you You can start to assign very specific time horizons to the instruments where we can look at something like the stock market and say, well, in today's environment, 14 years for a retiree who's very sensitive about the way they're going to generate their returns, 14 years is the time horizon over which they need to think about that instrument. And so I utilize a very sort of structured asset liability matching process inside of my planning processes where like I'm going in and for somebody I work with, I'm quantifying the expenses they have and the liabilities they have.
54:10And then we're matching instruments to give them actually a time horizon over which they know they have principal certainty of that instrument. And so for me, the stock market is this very sort of long-term instrument where if you're thinking of it inside of like your retirement plan, you've got to think of it as a decade plus long instrument because that's functionally what its sequence risk is potentially across different time horizons. Whereas something like a money market fund or a T-bill, something like that, you can match that thing to, you know, your emergency fund, your annual expenses, something like a five-year bond.
54:47You can match that to, you know, if you, if you're planning to buy a house and at some point in the next five years, you don't really know when you could reasonably go out and buy a five-year bond. And, you know, if that thing's got a duration of about five, you kind of know what your sequence risk is inside of that instrument. And so for me, good financial planning is all about really understanding time horizons and the way we're going to apply certain assets to match certain goals. And so I created this methodology that I call defined duration to try to help people kind of implement more of like an asset liability matching process where they can go in, understand their liabilities and expenses over time horizons, and then build a really diversified portfolio that isn't just diversified across asset classes so much, but is very strategically matched to very specific time horizons so that the investor can look at the portfolio and say, ah, well, I own$100 ,000 of T-bills because I needed$100 ,000 for a home down payment in the next year.
55:46And I know that's not gonna beat the stock market, but it's serving a very specific temporal goal inside of my portfolio. Right, it's also not gonna make them buy a$65 ,000 house in a year. Right, yeah. So you can match these things very quantifiably though, where the whole portfolio is basically serving a really a financial planning-based set of goals rather than the, you know, sometimes we put together sort of cookie cutter portfolios, like a 60-40 where, you know, your 60-40 is great. It's diversified. But what is the underlying goal of the instruments in there? It's not always necessarily very clear.
56:22Yeah, I hear you. Cullen Roche, your perfect portfolio. Get it wherever you get things. It's going to be available. I'm sure it all fine bookstores that are remaining out there that are actually standing up or right on Amazon. You can go there or go to thedisciplinedinvestor.com. Amazon, Harriman House. All those places. It's great. Thanks for coming on. We'll have you on again soon. Great book. Appreciate you coming on and imparting all this great knowledge as well. Awesome, Andrew. Thanks for having me. All right. Thanks. That was really interesting. The book is great. He is a really interesting fellow, and I appreciate him coming on.
56:59We'll definitely have him on again more than five years from now. I'll tell you right now, we'll definitely do that. Thanks for joining me this week and every week. We're working our way into the middle part, the heart of February, a short month for markets, oftentimes a little bit of a squirrely month for markets. But here we are. Thanks for joining me. Make sure to go over to thedisciplinedinvestor.com. See what's available there, the various strategies that we manage for clients just like you, whether it's our specialty of dollar-cost averaging through opportunistic and time-based DCA, dollar-cost averaging, or whether it's our lobster trap mentality.
57:36or even investing like the flower garden. All this is available to you. Make sure to go over there if you want some really clean advice. Yes, we manage IRAs. We manage non-IRAs and trusts and we do estate planning. We have wealth management. All that is available to you. So go on over to Disciplined Investor. Just reach out. That's all you have to do. And we'll make sure to get back to you and figure out how you can be best situated and into the hands of your future financial security. Thanks for joining me this week and every week. I'll see you again real soon. This podcast is intended for informational purposes only and does not constitute personalized investment advice.
58:19Investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz & Company, Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz & Company is properly registered or is excluded from registration requirements. Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement.
58:58Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates of Hollywood's a company.
From the publisher
Employment Report Solid
The Tech disruptors are getting disrupted…
Growth vs Value – an abrupt change.
Guest – Cullen Roche – Author of the bestselling book – Your Perfect Portfolio.
NEW! DOWNLOAD THE AI GENERATED SHOW NOTES
Cullen Roche founded Discipline Funds to help investors obtain access to low fee, diversified portfolios that help them stay the course and meet their financial goals.
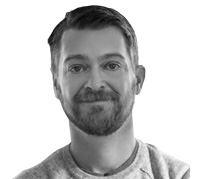
Cullen’s primary areas of expertise include global macro portfolio construction, quantitative risk management, monetary economics, financial accounting and behavioral finance. Prior to establishing his own business, Cullen worked at Merrill Lynch Global Wealth Management where he worked on a team overseeing $500MM+ in assets under management. Upon leaving Merrill Lynch, Cullen managed a private investment partnership which took advantage of reporting irregularities ahead of major corporate events. The strategy generated substantial positive alpha (high risk adjusted returns) without a single negative year of returns from 2005-2011. He formed Orcam Financial Group in 2012 to help better serve the much needed retail space with sophisticated but low fee asset management and financial planning services.
Cullen is also a prolific writer. In addition to the weekly musings on his website Pragmatic Capitalism, he is the author of the popular book Pragmatic Capitalism: What Every Investor Needs to Know About Money and Finance as well as “Understanding the Modern Monetary System,” one of the top 10 all-time most downloaded research papers on the SSRN academic research network. He is also the author of the popular white paper “Understanding Modern Portfolio Construction.” He was named one of the “Top Wall Street Economists, Experts and Opinion Leaders” of 2011 by Wall Street Economists and was named one of the “101 Best Finance People” by Business Insider, where he was described as “one of the most influential economic thinkers today.” In 2015, Cullen was named one of the “40 Under 40” most influential people in finance by InvestmentNews. He is regularly cited in the Wall Street Journal, on CNBC and in the Financial Times.
His latest book is YOUR PERFECT PORTFOLIO: The Ultimate Guide to Using the World’s Most Powerful Investing Strategies . In that, Roche draws on two decades of experience building investment firms and advising clients to help readers discover the strategy that fits their goals
Check this out and find out more at: http://www.interactivebrokers.com/
Looking for style diversification? More information on the TDI Managed Growth Strategy – HERE
Stocks mentioned in this episode: (INTC), (UEC), (IONQ), (CEG), (OKLO), (NXT)