
In short
Market volatility and “hidden risk” in public and private credit, plus a discussion of banks, private credit/insurance demand, and precious metals (gold/silver). The host also notes the death of John C. Dvorak and mentions a Fort Lauderdale memorial meetup.
Guest backgrounds
Christopher Whelan is chairman of Whelan Global Advisors and publisher of the Institutional Risk Analyst. He previously worked as a Federal Reserve Bank of New York financial policy advisor (bank supervision and futures desk) and has long studied U.S. financial system, banking, credit markets, housing finance, and regulation. Author of Inflated, Money, Debt, and the American Dream.
Key claims
Public-market AI/tech strength is masking leverage/speculation (citing FINRA margin “debit vs credit” divergence). Private credit is “slow motion” and opaque, with many insolvent borrowers, non-recourse structures, PIK payments, and continuation funds that reset clocks. Bank earnings are differentiated by business mix; private credit competition compresses loan yields. Transparency is “largely bullshit” beyond first-level disclosures.
Notable examples
Microsoft vs Meta earnings/capex; Korea semiconductor/storage declines; Goldman removing Apple-related exposure; white-label credit-card risk; SVB mortgage-duration mistakes; multifamily loss rates “100% of the loan” vs Fed-supported bank mortgage default rates near zero; Monetary Metals gold-lending for jewelers; Bunker Hill Mine (Barrick team) targeting silver/rare metals.
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOAcknowledging a Loss
1:13 to 2:07
Host reflects on a difficult week and the passing of a friend.
“Horowitz & Company, from seed through harvest, cultivating financial success.”
Upcoming Meetup Announcement
2:07 to 4:15
Information about a meetup to celebrate the life of John C. Dvorak.
“And as you know, it's been a kind of a miserable week.”
Market Update and Analysis
4:15 to 8:21
Discussion on recent market movements and investor behavior.
“We'll talk about John and we'll throw a few back as well.”
Investor Perspective and Action
8:21 to 14:01
Encouragement for investors to take action and gain perspective.
“My concern is the advanced decline line.”
Immediate Action Required for Your Financial Future
14:01 to 16:09
Learn why delaying financial decisions can be costly and how to take charge of your future now.
“We're in the beginning of August already.”
Introducing Christopher Whelan
16:15 to 17:42
Get to know Christopher Whelan, his background in banking, and insights into the financial market.
“Christopher Whelan, he is one of America's best-known independent banking analysts and financial historian.”
From Politics to Finance: Whelan's Journey
17:42 to 20:02
Explore Christopher Whelan's unique journey from a political background to becoming a financial analyst.
“I started my life growing up in a very political family in Washington.”
Understanding Financial Imperfections
20:02 to 22:43
Understand the inherent imperfections in finance and the importance of adaptability.
“Well, I think what you throw away is that you shouldn't expect perfection.”
The Risks of Today's Financial Landscape
22:43 to 25:07
Discuss the hidden risks in the current financial markets and the impact of private credit.
“Well, the regulation that occurred after the great financial crisis, as they call it, drove a lot of activities into other sectors.”
Banking Strategies and Market Dynamics
25:07 to 28:07
Examine the strategies banks use to maintain profitability amid changing market conditions.
“That is the proof of what you said, right, in a reverse methodology.”
Show all 28 chapters
The Illusion of Transparency in Banking
28:07 to 28:51
Discussion about the transparency of financial institutions and bank earnings.
“You know, we're going to show you everything.”
Risk of Non-Disclosure in Bank Reports
28:52 to 29:59
Exploration of banks' non-disclosure of critical loan items and its implications.
“The reason is, is that they only show you so much.”
Challenges of Private Credit Financing
30:00 to 31:27
Analysis of the competitive landscape for banks versus non-banks and issues with private credit.
“Perhaps, but I think it's just a matter of risk.”
The Dangers of Private Equity Financing
31:28 to 33:15
Discussion on the risks associated with private equity financing and its impact on companies.
“Private credit's a slow motion train wreck, is what I like to call it.”
Market Risks and Speculation Trends
33:16 to 34:38
Examination of current market trends and risks, especially in tech stocks and margin lending.
“I think it's fascinating that, you know, we have these companies like, go back to crypto for a second, you know, oh, we need to have this in your 401k plans, right?”
Behavioral Shifts Post-Financial Crisis
34:39 to 36:41
Analysis of behavioral changes in markets following the 2008 financial crisis.
“So that tells you that that's a naked, you know, long position.”
Private Credit and Investor Challenges
36:42 to 39:24
Discussion on the challenges faced by investors in private credit markets and their lack of transparency.
“And I think that scar tissue still stays with us, and it's caused behavior to get really crazy.”
Insurance Companies and Private Credit Demands
39:25 to 42:00
Insight into the relationship between insurance companies and the demand for private credit.
“And you've signed an NDA, so you can't complain.”
The Demand for Business Purpose Loans
42:00 to 43:16
Learn about the current demand for business loans and the risks associated with insurance companies.
“The reason you have such a vast demand right now for business purpose loans that are supposed to be for rental properties is because of this.”
Impact of Fed Policies on Mortgages
43:16 to 44:45
Discover how Fed policies have influenced mortgage default rates and the banking sector.
“And what that means is that if somebody actually defaults, they have enough cash on the table that they can just buy them out, sell the house, hand them the excess, and say, get your life together, goodbye.”
Silicon Valley Bank's Risky Investments
44:45 to 46:16
Examine the risky investment strategies of Silicon Valley Bank and their consequences.
“and it sunk all these bonds because the banks thought this was going to be forever.”
The Case for Precious Metals as Investments
46:16 to 49:00
Explore the investment potential of gold and silver, and the trends affecting their value.
“We have to have a little sit-down meeting with bankers who want to own variable duration stuff.”
Innovations in the Gold Market
49:00 to 51:15
Understand the innovative approaches to gold lending and investment in the modern market.
“Meanwhile, we have silver, which is really not a monetary asset.”
Preparing for Economic Challenges
51:15 to 56:01
Learn about the looming economic challenges, inflation, and strategies for asset protection.
“Which is what I like about it, by the way.”
Cost Cuts and Inflation Insights
56:01 to 57:25
Discussion on reducing living costs and the impact of inflation on investments.
“We moved down to Florida, we cut our costs in half.”
Energy Market Dynamics
57:26 to 59:20
Exploration of the current state of oil reserves and energy market risks.
“Why are markets still not reflecting, I would say, the risk in your thesis that we're going to have this inflation moving higher by the end of the year, next year, whenever it is?”
Refined Products and Global Trade
59:21 to 1:01:10
Analysis of the refining process and international trade of refined products.
“We're not going to just be able to follow price and say, well, you know, we'll buy diesel fuel, for example, for the West Coast of the United States from Korea, which is what we were doing.”
Legal Disclaimers and Closing Remarks
1:07:14 to 1:08:30
Final legal disclaimers and closing statements regarding the podcast.
“and does not constitute personalized investment advice.”
Transcript
Automatic transcript. May contain errors.0:00Christopher Whalen:This episode is sponsored by Interactive Brokers. And you know, you research your investments, you analyze markets, you manage risk. But have you researched your broker? For the past three years, Interactive Brokers' individual clients averaged an annual return of 24.3%, compared to 23.1 % on the S &P 500. IBKR's lower trading costs, competitive rates, efficient execution, and access to over 170 global markets help investors keep more of what they earn and put more capital to work. Over time, the broker you choose matters. Interactive Brokers, member SIPC. If you care about performance, find out why the best informed investors choose Interactive Brokers at ibkr.com slash performance.
0:51Christopher Whalen:Visit ibkr.com slash performance.
0:57JCD:The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast.
1:07Christopher Whalen:This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz & Company, from seed through harvest, cultivating financial success.
1:26Christopher Whalen:Saying goodbye to JCD and the first test of the Fed chair. What a miserable outcome that was. Some eye-popping moves in the bond market and an update on the meniscus repair. And our guest this week, Christopher Whelan. He's a publisher of the Institutional Risk Analyst. All this and much more on episode number 984 of the Disciplined Investor Podcast.
2:06Christopher Whalen:And welcome to the Disciplined Investor Podcast. I'm Andrew Horowitz. And as you know, it's been a kind of a miserable week. First and foremost, my dear friend and longtime podcast co-host has passed away. John C. Dvorak is no longer with us. If you've listened to DHM Plugged, you know about that. If you listen to No Agenda, you know about that. If you follow me on Twitter, you know about that. Anywhere we have a presence out there, we've talked about it. And it's a very sad day, very difficult. Combine that with my meniscus surgery on top of it, and it's just been a really tough week overall.
2:43Christopher Whalen:Really difficult, not only for me, but also for the No Agenda family, the DHM Plug group, the listeners of this show that know I've done this for such a long time with John. And now we are including the Discipline Investor listeners in that grouping, in the DH Unplugged. And in fact, we're going to talk about that a bit more. I have a bit of a tribute, a testimonial. I'll play that at the end of this episode after our guest. I want you to hear about it. It's something I did for John. I want to play it. It's very cathartic for me to have this out there to make sure I pay the tribute to the man who I call a dear friend and family as well.
3:24Christopher Whalen:just one more time. We'll do that. And before we do that, I also want to mention something that is, I think, really important and make you aware of that we're having a meetup. We're having a group meeting in Fort Lauderdale to celebrate the life of John C. Dvorak for all the things that he did technology-wise, writing-wise, all the things that he did for podcasting. If you're a listener of No Gender, if you're a listener to DHM Plug, the Discipline Investor, it's going to be on the 8th of August at 333. That's an important number, 333 p.m. And it's going to be on the beach down in Fort Lauderdale.
4:02Christopher Whalen:If you want more information about that, you can find it on the signup page over on DH Unplugged. So go to dhnplugged.com and there's a signup page right there that you'll find all the information that you need and we'll get you all the information. It's going to be a good time. We'll share some laughs. We'll talk about John and we'll throw a few back as well. It's going to be great. Again, that's on 8-8, the August 8th, 2026, 3.33 p.m. in the afternoon. And right on the beach, at actually a restaurant on the beach. So you'll get all the information. Go over to dhnplug.com and check that out. Now let's talk about what's going on in the markets because last week we had Brian Shannon on.
4:39And he talked about only price pays.
4:42Christopher Whalen:And we know about that, right? The action we saw last week with the crazy moves that we saw at the beginning of the week and then the crazy moves to kind of mirror the upside from the downside at the end of the week was pretty astonishing. And clearly this is, there's a good amount of pain that's going around. In fact, when we saw on, I guess it was Thursday, that huge up, that 3 % move or so on the NASDAQ in the morning of Wednesday, when we saw what happened there, the fact was, interestingly enough, that there were more losers than winners. The decliners outpace the advancers. That is not a great setup.
5:22Christopher Whalen:And when we look at something like that, I have to wonder, you know, what's going on. In fact, what it was, it was like the 15 % move on names like Microsoft that just blew out earnings and really had a great report that offset the earnings from Meta that was down about 9.5 % on their capital spend when they were talking about how they had plenty of compute to spare. They don't need to really be doing a lot more, but yet their CapEx budget was, I mean, mushrooming. Where Microsoft, on the other side, said that their Azure numbers were really doing great. They're using all the computers that they have right now.
5:55Christopher Whalen:So what we're seeing right now is a tale of many situations, right? We're seeing on one side the welcoming for Kevin Warsh into the Fed. Hello, sir. You don't want to tell us anything? We're going to sink the market pretty good. We saw the Dow down like 1 ,000 points on Wednesday after they came in with no chains. Credibility at, I would say credibility is at a big concern level right now. And then we had semis taking it on the chin. I mean, left and right. The numbers we saw entering into a bear market for the semis, not only here, but like a 35 or 40 % decline from the highs in Korea. SK Hynix and Samsung and all of the other names in that arena doing really poorly.
6:42Christopher Whalen:We saw, I think, a 40 % correction on some of the disk drive makers. And you look at Intel and AMD, where they were, where they came to. Even the numbers in the software space started to do a lot better. Well, what is going on? Well, there's a lot of margin. There's a lot of leverage out there. And I think that's a big issue. What's also interesting, I think we have to recognize, is that while this was all going on, one of the things that we saw was that there was a significant amount of movement in things like healthcare, in staples, in the non-sexy alternative trades that were like, well, I need something.
7:20Christopher Whalen:I mean, markets were telling us something. I think it's very clear. They want to be in equities. Investors want to be invested. They do not want to be out. What they're going to do instead is a rotation. They're going to move from the technology shares, the things that were working, and all of a sudden they're going to kind of move away from that into something else, and they'll make that work. That's what we saw, for example, the healthcare shares, when you look at the ETF, at an all-time high. Doing great. When the biotechs are starting to really do very well. Staples, to a lesser extent, but still doing well.
7:52Christopher Whalen:Financials, a little spotty after the earnings. But right after the earnings in this earnings season, things were glorious. You look at the Goldman, J.P. Morgan. Again, you look at Bank of America, to a lesser degree, some of the other names that didn't do as well, the Wells Fargo, but Morgan Stanley, all these names that have participation in these IPOs and the capex spending. All of this has been very, very good for the overall market. And now the rotation was, to a degree, until this week, holding things up very nicely. My concern is the advanced decline line. That's an issue. We're going to have to watch that.
8:25But what this clearly, again, is showing is that there is an appetite for risk.
8:31Christopher Whalen:Maybe the risk parameters have changed a little bit, but that appetite for risk from going from things like the tech trade, the semiconductors, the storage, the chips, over to emerging markets that have now rotated back to a little bit more of the calm and more relaxed type of investors. So that's something to be looking at. that rotation is something that is holding things up very nicely right now. Bonds, on the other hand, after and post, well, I should say into, into the actual print of Warsh's and the Fed's actual number when they came out on Wednesday afternoon at 2 p.m. Eastern. And then the follow-up conversation, it was rather, I would say, flippant.
9:21Christopher Whalen:It's like, you know what? We're going to let the markets do our work. You know what? That's the best thing to do. We don't have to be doing what they did before. We don't have to have all this conversation. Markets didn't really appreciate that. They didn't appreciate the fact that there was a significant amount of people inside the Fed that wanted to actually hike rates, and they still cooled it off. And the question is, well, why? What are you waiting for? We saw PCE come out on Thursday, 3.3%. GDP sagged a bit. The numbers, and we saw the GDP deflator, a huge number on the upside. And even though inflation, generally speaking, through the PCE, through PCI, was somewhat tame to a degree, the fact is we're still seeing a lot of underlying inflation.
10:06Christopher Whalen:A 6.3 % GDP deflator that came out on Thursday kind of threw markets into concern. And that's why we saw the advanced line versus the decline line on Thursday really get wacky. So I was thinking about all this. I was thinking about all the zigzagging markets and what was going on. And a few days down, a few days off, it's just a reversal. A lot of people are looking for answers right now. What do I do? I'm freaking out. I'm excited. Oh, my God, what's happening? This is fantastic. I mean, the emotions that are going on every single day back and forth. But the fact of the matter is that there still is a general investor appetite out there.
10:43Christopher Whalen:And I think rarely have we seen markets, say over the past year or so, break one way or another definitively for a period of time other than for a month or here or there, and then it just turns. So the big question with that is really what is that going to mean for us longer term? What is that going to mean for markets? Are we in a situation that we're going to grind? I want you to step back for a second. And I want you to become a little more less agitated about the situation. Because it is funky. It is a bit concerning. It is a situation where it can get you and make you think like, I don't want to get anywhere near this.
11:28But the fact is we still know that the stock market in general,
11:33Christopher Whalen:the equity markets around the world are some of the best capital formation levers that you can pull in life to make sure that you are far ahead of where you should be into retirement. The problem is that we see it every day. We look at the CNBCs, the Bloombergs, and other stations and looking at the markets and the headlines and they're flashing us all the time. It's like, wow, it's like right in our face all the time. Step back. I want you to get in a little perspective here. I want you to get from looking up so close, like right here, it's always right in my face, to backing up a little bit.
12:11Christopher Whalen:We've talked about this so many times. This perspective, this perspective that you should be having where you can step back and look away gives you a much better viewpoint of what you should be doing. Now, am I telling you to actually go in and go all in on the markets? No. But we post this again on Twitter because I think we're starting to hear a lot about this from people that have sold out. They're like, you know, what do I do now? How do I do this? And I've talked about this 100 times, this one foot out, one foot in protocol that we developed to kind of dollar cost average you into the market.
12:46Christopher Whalen:That is smart. Don't stay all out. Don't stay all in. Let's get you in a situation where you're broadly diversified in the right manner that is appropriate for now and for the next several months, according to the current outlook that we have from an economic and an earning standpoint, of course. But looking back at things from a distance, I think that's a pretty good idea. And right now, considering all the cross currents that we're seeing and a new Fed that's going to be tested and the period we are in the presidential cycle with the midterms coming up, I think the best thing we could do right now is spend a little time and simply step back, gain that perspective that we need so desperately and not make any kind of crazy moves right now, but ensure that you're allocated properly for the next hour long.
13:40And understand that you have to wonder,
13:46Christopher Whalen:what are you waiting for? What are you waiting for? I've said it before and I said it again, especially now with the understanding that life is short. Life is really short. Days go, weeks go, months go, and all of a sudden it's next year. Here we are in the end, beginning. We're in the beginning of August already. That's where we are. And with that, this idea that someday in the future we'll do something has to stop right now. Why wait anyway? Things can happen if you just put things off, right? We know that, but the truth of the matter is that I want you to consider the fact that every time you put something off, it's costing you.
14:27Christopher Whalen:It's costing you a ton. Every single time you say, oh, wait until tomorrow. It's costing you. Your future is reliant on you making the right decisions right now. Whether you're doing it yourself, working with somebody, I don't really care. The fact is, do something. Be motivated, self-motivated to get it done. Do not wait. Everything just gets more expensive. Honestly, it's just dumb. It's just dumb. I can't tell you how many times I've seen people wait and they're like, well, let's do it. I'm like, you're 60 years old. You haven't done it yet. What are you going to do now? And then they can't do it.
15:02Christopher Whalen:If you're 35, 45, 50, 55, make the right decisions now. For goodness sake, let's get it going. I mean, if you don't know how to, let someone help. If you can't do it on your own, let someone help. That's what we're here for. That's what we do as advisors. We're here to help you make those decisions that you can't do. You want the security? Listen, your future isn't something that happens to you. It's something that you create. It's something that you create. How? With the choices you make right now. I want to get to our guests, but first I want to talk about something. You know, you could trade your portfolio with the power of prediction market probabilities.
15:46Christopher Whalen:With interactive brokers, trade prediction markets on election, climate, and economic outcomes right alongside stocks, options, and bonds. Prediction market prices reflect probability, and correct predictions receive$1 per contra, plus earn interest on your position. Prediction contracts are not suitable for all investors. Visit ibkr.com slash predictions. Let me tell you about our guest today. Christopher Whelan, he is one of America's best-known independent banking analysts and financial historian. He is chairman of Whelan Global Advisors and publisher of the Institutional Risk Analyst, where he analyzes banks, credit markets, housing finance, and financial regulation.
16:31Christopher Whalen:He has spent many decades studying the U.S. financial system for both the public and private sectors and is the author of Inflated, Money, Debt, and the American Dream. His market commentary is widely followed because he's willing to challenge conventional thinking and often does so well before consensus catches up. I've been looking forward to having Chris on the show for a long time, so glad that we were able to make this happen. So, Chris Whelan, welcome, finally, to the show, The Disciplined Investor. How are you?
17:01JCD:I'm good, man. Nice to join you.
17:04Christopher Whalen:Yeah, like I said, I've been looking forward to this for a long time, and I have a lot of, I think, interesting questions to ask because I want to find out more about you. and I want the audience to do so at the same. And plus, this is a prime time for some of the things that you know about to bring us some of the details on. So let's go back a little bit. And like I said, we're looking forward to having you on. You started out your career. You're a former Federal Reserve New York financial policy advisor, and you ended up where you are now. And I want you to start with your first job. I think it's an interesting place where you started to how you got to this place from here.
17:42Well, okay.
17:43JCD:I started my life growing up in a very political family in Washington. My father, Richard Whalen, was the biographer of Joe Kennedy, worked for Harry Luce at Fortune. And then he comes to Washington and ends up as a speechwriter for Richard Nixon. He was the sous chef in the Reagan kitchen cabinet. He and a couple of his buddies wrote the first acceptance speech, Family Neighborhood Freedom. So, you know, I grew up with all sorts of interesting people roaming around our house at all hours of the day and night. You know, Bill Casey, Jim Slesinger, Pedro San Juan, who is Bobby Kennedy's guy. So, you know, I worked first for Jack Kemp out of college.
18:30JCD:I went to Villanova and I worked for Kemp on Capitol Hill writing about legislation. So I started my life as a writer. And then I ended up moving to New York because I couldn't stay in Washington. And I became a management trainee at the Federal Reserve Bank of New York. I was basically a Volcker appointee before he went to Washington. I worked briefly for Tony Solomon and then Jerry Corrigan in bank supervision. and then I went across the street to foreign and I was in charge of the futures desk. And it was funny. I actually got my futures license while I was there and they were like, why did you do that?
19:08JCD:And at the time, we didn't have FINRA. We had all of these independent associations and I was now a member of the National Futures Association. So it was very funny. Wow. And then from there, I went to Bear. I worked at Bear Stearns in London. That's where I really learned about the bond market. And, you know, the rest of it's kind of on the bio. But I got a lot of interesting opportunities as a young person to see the world that most people never see. And so, you know, I've been very, very grateful for that.
19:41Christopher Whalen:But the one thing that's really interesting is that when I looked at that and I did my research on this, I'm thinking, my gosh, three unbelievably different perspectives on the way you think about finance, right? from a political standpoint to more of an academic and then to the trenches. So, I mean, that's kind of shaped how you dealt with this. I mean, what did you pick out from that and what did you throw away?
20:07JCD:Well, I think what you throw away is that you shouldn't expect perfection. You know, the world is imperfect, as, you know, the great man said, the crooked timber of humanity. And I think that, you know, whether it's politics or markets, you always have to be trying to see to the details as you go along. But you also have to make it up as you go along. You know, for example, Jerry Corrigan, a man who had to clean up a lot of other people's messes in the financial markets. He was really Paul Volcker's go-to guy. And both of them had to go out and deal with a lot of stuff from the debt crisis on through till the end of their careers that was caused simply because of the ebb and flow of the economy and the ebb and flow of interest rates and the natural tendency of people to do too much and be a little greedy at times.
21:00JCD:At times. At times, yeah. So you have to be accepting of the fact that people are imperfect. and no matter how much you hope that society will do the right thing, Americans will usually do the wrong thing until they've exhausted all the possibilities, as Winston Churchill said, right? Yeah. So that's kind of how I look at the world. I work in mortgages a lot now. Right. So that is a business that is entirely imperfect, no matter how the progressives try and regulate it. The reality is that every loan is different and every loan has a person and a story. So you have to be flexible enough to deal with that.
Read the full transcript
21:42JCD:Right.
21:43Christopher Whalen:So one of your strengths, you talk about working in mortgages, is digging through the financials, right? Getting down and dirty into understanding that. And you just pointed out the fact that, you know, you look at that area, it's different for every single, literally every single house, right? Every single person that's in there. You could have someone in the same neighborhood with the same amount of mortgage, the same bank living next door with an identical house. Entirely different setup of what is it going to be for that mortgage. With that understanding and looking at what you've seen, how much of today's risk do you think is hidden?
22:19Because that's the big plan, right?
22:22Christopher Whalen:to make sure that while we are attempting to do the right thing by our investors, sometimes things don't go right and we've got to kind of not show them all that because we can end in demise really quickly. So is the accounting methodologies or something going on today that you see as concerning?
22:43JCD:Well, the regulation that occurred after the great financial crisis, as they call it, drove a lot of activities into other sectors. So, for example, you couldn't earn the big fees in public markets that you could 20 years ago. So where did these people go? They went to private credit. That's where they could still earn their two and 20. And I think that right now, if you look at the financial markets today, as we go through second quarter earnings, the big problem is that the public markets are clearly on fire because of AI. and that's actually starting to collapse. I told my readers to get out at the end of last year, in fact.
23:26JCD:And then the private stuff is even more concerning because what you have is banks that have been disintermediated by the Apollos and the Brookfields and the Blue Owls. I love that name. And they have tried to compete. But what you've seen for the last six quarters is the yields are falling. And that means that banks have to compete. They have to drop their cost of funds, you know, and they have been doing that. But they also have to drop what they charge for loans if they want to win the asset. Because your customer is going to go to somebody else.
24:00Christopher Whalen:With that's happening, we still saw a lot of the banks do very good. Net interest margin reports were generally okay.
24:07JCD:No, no. Yields on earning assets have been falling for six quarters. Now, the margin is still okay because funding costs have been falling. Not as much, but they have been falling a lot. But, you know, what I do with banks is I always tear apart, what do you make on assets, loans, securities, right? And then I look at funding. I look at credit, obviously. And that gives you a whole picture of the interest rate side of the house. And then you look at the non-interest rate side, the fees, the investment banking. So that part's been going great.
24:38Christopher Whalen:Yeah, great.
24:38JCD:Oh, my God. But, you know, most of the banks are kind of flatted down on the making money on money part. Right. Right.
24:46Christopher Whalen:You know, it's interesting because you saw the differentiation clearly between like a Goldman, which just had extraordinary numbers, SpaceX, and J.P. Morgan that had unbelievable numbers, SpaceX, and the things that went on with that. And then you look at the others like the Wells and, well, let's just say non-investment banking centric companies, which is right back to what you just said. That is the proof of what you said, right, in a reverse methodology.
25:12JCD:Oh, totally. And, you know, it is what it is. The banks are making hay where they can, particularly Goldman. Goldman is infinitely flexible. But the big story with Goldman this quarter was that they got rid of Apple. That means that their smallest line item, Platform Solutions, is going to probably disappear. And now they're going to be back to being a two-line company.
25:36Christopher Whalen:That was the Markham card, right?
25:39JCD:Yeah. The credit card thing that they tried to get into? No, no. Marcus was their own invention. That was their attempt to kind of get into banking, have an offering for their asset management clients and their private banking clients, which is fine. They're not really good at that because they're not really bankers. Most of Goldman's a broker-dealer. But what they had done was they said, well, we'll get into white-label credit cards, which is a profoundly bad idea. And so they ended up being the sponsor for Apple, the Apple portfolio is only$20 billion. It's barely big enough to even care. And so now that book is going to JP Morgan.
26:20JCD:Jamie, I think, has a lot more leverage. He's going to be able to keep them in line. But you would think Apple would have a bigger book, honestly. The reason why I mentioned Marcus, I thought that was the name of the company,
26:32Christopher Whalen:of the, in other words, with Goldman, the card that they issued on the -
26:37JCD:Yes. Maybe. I'm not sure what they gave to the Apple people. I think Apple had their name on it. But white label credit card is a tough business. There are some banks that have done it historically. Jamie Dimon, he's got about a third of his credit card business now in white label. God bless him. But you own the credit. So when the credit goes bad, it's your expense. Right. And I think, you know, on the good side, they're going to see their credit losses go down. We're going to just see the wholesale book now at Goldman, which is another conversation we could have because they bank a lot of people that J.P.
27:14JCD:Morgan won't bank. OK. And they don't have a very low cost of funds at Goldman. So they have to charge a lot. Their gross spread on their loans is around 10 percent. That's twice J.P. Morgan. And so what they do is they charge a lot. They're more aggressive on what they'll give you in terms of advance rates. But overall, you know, it's tough for them to be in that business. It's not impossible, but it's not like they, you know, not like somebody like Truist, which has the lowest cost of funds among the top seven. So they have a lot of money to play with. And JP, too. JP's got very low cost of funds.
27:51Christopher Whalen:So now in modern day accounting, is the items that we've been told are and the rationale for what's going on in a lot of companies, this, you know, quest for transparency because we're the good guys. You know, we're going to show you everything. Right. Right. Or is it is it is it more just, you know, word garbage? Right. Where it's a talk in the talk and this whole idea, but buried beneath the footnotes and even end notes and even, you know, disappearing ink in some cases. Right. That it's really not as transparent as everybody would think. And one thing I will say is that I've been in this business for however long.
28:31Christopher Whalen:Literally, people are like, what do you think of the bank earnings? I'm like, you know, I'm not going to try. I'm literally not going to try. Seriously.
28:38JCD:Well, banks are relatively easy compared to mortgage companies. Yeah, I'm sure.
28:41Christopher Whalen:Right, right. But so is the modern day transparency with financial institutions something that we should applaud or is it just total bullshit?
28:51JCD:I think it's largely bullshit. The reason is, is that they only show you so much. You know, they go down to basically the first level, if you will, in terms of the general ledger of the company. So they're showing you business lines. They're showing you significant subsets of that if they're big enough. So, for example, many banks don't break out loans to non-depository financial institutions, even though that's the fastest growing line item on most of their balance sheets. The FDIC gives us an aggregate number and we can back into some of the other numbers. But they still haven't forced the banks to put that line item on their call reports, even though now it's gotten to be a trillion and a half dollars.
29:35JCD:There's over three trillion dollars in unused lines behind that. So you're figuring, you know, over four trillion dollars in exposure. And the FDIC still hasn't gotten around to forcing the banks to disclose it as a separate business line.
29:50Christopher Whalen:But the banks will use that against individuals who are applying for a credit card or credit for any open lines that you have that are unused. They will use that as something. And by the way, taking that and reversing that back to the banks, that's why they don't want it released.
30:07JCD:Perhaps, but I think it's just a matter of risk. You know, the big problem today for the banks is that they have to compete with the non-banks. The Apollos and the Brookfields and all the rest of them have access to capital that's almost equal to that of the banks. So if I'm a company today and I'm looking for financing, let's say I'm a very good credit, right? I go to JP. They quote me whatever. Then I go to Apollo. And Apollo may beat JP's price. Right. So in that case, you know, the banks have to work extra hard. And what's happened is the rest of the loan book has only been growing 1%, 2 % a year.
30:45JCD:So all of a sudden, they have private equity guys who they want to do business with, remember, coming to them saying, hey, our portfolio company has a couple of components that aren't making money right now. We need to pay dividends. Will you give us a loan? So they'll make a loan to a private equity fund on a non-recourse basis, right? They have no way of getting paid back. Unless, say, the company has become profitable, I mean, what is the sponsor going to do? tell the LPs that they have to pony up more cash to pay back JP Morgan. Right. And they're not going to sue them, right? Yeah. They've already accepted it as non-recourse.
31:23Christopher Whalen:Yeah.
31:24JCD:So that's, to me, the problem we face with private credit. Private credit's a slow motion train wreck, is what I like to call it. And it's going to continue to be a train wreck because half of these companies are insolvent. They're paying their debt with payment in kind where they give you equity of dubious value. And some people will actually take that equity and pretend that the value of the investment went up.
31:49Christopher Whalen:Well, I mean, we've seen that kind of thing where I've seen this. I don't know if you agree with this. I'm going to go off script of the banking area for a second where, you know, you have the financing of income. So, for example, when Microsoft takes money off their balance sheet and gives it to XYZ AI company and says, by the way, we're going to give you$4 billion. and part of the deal is we're going to take a piece of your company and you're going to buy back a$3 billion contract over a four-year period with Azure, and all of a sudden magically IBM's revenues slash income go up. And what they've done is, tell me what you think, but what I think is they basically took magically money off the balance sheet and put it on their income statement.
32:34JCD:That's right. Right. Now, you know, we should always remember that public disclosure is an oil painting. It's not meant to be an x-ray. So the requirements from the FCC say you have to show us so much. And the investor relations guys will only show us so much because that's their job. Right. And in the case of things like private credit, well, they showed us a little at the end of last year, some of the banks in the first quarter gave us a page or two on it. But now, no, they've taken it back. Right. Because the lawyers told them, if you put this out as a regular disclosure, you have to continue to do it.
33:14JCD:So that's what's going on there.
33:16Christopher Whalen:I think it's fascinating that, you know, we have these companies like, go back to crypto for a second, you know, oh, we need to have this in your 401k plans, right? Now, private equity, private credit was like a part. I was at an event. I was at down in Miami a year ago at the, I forgot what event it was. It was some event. I think it was Ritholtz's event. And I was literally, I went to this cocktail party and it was like, I was like crap with flies around me, just descended upon by these people. They don't owe me from anybody. How much of your portfolio of your clients are in private equity? I'm like, what?
33:49Christopher Whalen:Why are you asking me this, right? This whole discussion and almost like this peer pressuring, Weird.
33:55JCD:Well, you notice how quiet they're being now. How quiet.
33:58Christopher Whalen:Remember last year?
33:59JCD:We had retail shops out advertising private credit on television. Yep.
34:04Christopher Whalen:And then all of a sudden we have the holdbacks, no requirements, and no money coming out. It's crazy. So I don't know if that's one of them, but you've said one of the biggest risks. No, no.
34:12JCD:The same guys were talking about crypto rather loudly.
34:15Christopher Whalen:Right. Right. Exactly. Now, you often say the biggest risks aren't where everybody's looking. I think you've said that a lot. And historically, the markets have been consistently underestimating risk. I think that's something you've also talked about. Where do you think that we're making the same mistake now?
34:37JCD:Well, the obvious ones, you know, if you look at margin credit, the debit side has gone straight up to the moon and the credit side is not moving. So that tells you that that's a naked, you know, long position. And these markets are starting to revert to the mean. You saw the same thing with gold. Can you just back up? I'm sorry to interrupt.
34:55Christopher Whalen:Can you just give me a little explanation of what those things mean?
34:59JCD:When you see margin credit going up, look at the numbers that FINRA discloses, right? They have a debit side, which is people borrowing money to go out and buy stocks. And then they have a credit side, which is how much money is in the account that could compensate that. In other words, what do they have in their margin account in terms of equity? and the two numbers have just diverged. That's not normal. That's been something very recently. So what it tells you is that the amount of speculation today in public markets, particularly in AI and related tech stocks, has been extraordinary. There's a huge amount of manipulation involving agentic trading where people create bots and they tell the bot, you know, go out and make money.
35:44JCD:So the bot does. The bot goes out and trades stock without any intervention from you But you can really do a lot of malicious things in the market using this technology. And nobody at the Trump administration cares because they're too busy making money for themselves.
36:01Christopher Whalen:Making money. It's all about making money.
36:03JCD:You know, Paul Atkins at the SEC, forget about it. He's worried about crypto. Yeah. And he's an old friend, by the way. I love the man. He's a great conservative, but not a good guy to have as a regulator. And in my dad's book on Joe Kennedy, the first chapter is about Joe at the SEC. And he knew about speculators. You didn't have to tell him anything about that. So we're going to come back to that because this period we've been in since the great financial crisis, which I think really is a function of everybody being terrified. Many, many, many of us after 2008, 2009, 2010 were broke. Most of our assets had declined enormously in value, and the leverage was gone, right?
36:47JCD:So we had to rebuild these markets. And I think that scar tissue still stays with us, and it's caused behavior to get really crazy. And I mean, you know, both in public and private markets. So that's what I worry about. I think that, you know, some banks are laying off risk very astutely. Yep. And there are people standing there that are willing to buy it at top dollar, by the way. Always. Yeah. And then there are others who aren't. So there's always dumb guys in the room. The greater fool theory we call that, right? So look at Bank of America. How on earth did Brian make all those mortgages in 2020 and 21?
37:25JCD:And he didn't sell them for a profit. He could have sold those twos at 104. In other words, I have friends who have 2 % mortgages from Bank of America that today trade in the high 60s, low 70s if you wanted to sell them. Right. Well, that's why he's earning less than 3 % on his$800 billion bond portfolio.
37:46Christopher Whalen:And I thank him for my 2.75 % mortgage, which, by the way, my wife says, why don't we pay it off? I'm like, are you kidding? No. I'd take out more if I could.
37:54JCD:Tell her to have a party when you die. That's right. Exactly.
37:57Christopher Whalen:You know, it's interesting because you talk about the leverage margin issues. You know, look what happened in Korea recently where not only were the margin to the hilt, but they were trading significant leverage products. Forget about other things you're doing too. But, you know, not only do we have the margin, the leverage, the divergence of the debit credit side, but you also have the leverage side of things, whether it could be futures or it could be just levered products that the average investor has. And that's not really calculated into the whole margin thesis, is it?
38:28JCD:No, no, it's not. And, you know, these markets in Asia trade the way our markets did in the 1920s. Right. When Americans first got into investing and they, oh, wow, how cool is this, right? Stocks, margin. So, you know, the same kind of intensity and the same kind of willingness to take risk that they may or may not understand is very evident in the Asian markets.
38:53Christopher Whalen:Can we switch back to private credit for a second? Because this is something that's been bugging me. I have some clients that we adopted positions from, from a variety of these private credit. We try to go through the financials, but we know we're only getting the financials they want us to see. You know, whether they're side-pocketing, whether they're just not disclosing, or whether they're just holding a mark to wish. Would that be the right word? Mark to fantasy? Definitely not mark to market on some of this stuff, right? Oh, no.
39:21JCD:No, no, no. You're the sponsor to tell you what it's worth.
39:26Christopher Whalen:Yeah.
39:26JCD:And you've signed an NDA, so you can't complain.
39:30Christopher Whalen:Yeah.
39:31JCD:You know, the way they run these funds now, when they get to the end of the fund life and they are supposed to sell it, oftentimes they'll sell it to another private equity company or they'll do what's called a continuation fund where they'll force the LPs to stay in. but they'll just reset the clock and put the assets in a new vehicle. And it's totally opaque. There's absolutely no reason on earth why you would want retail investors or even high net worth individuals to get involved in this crap. If you have institutionals and insurance companies that want to play here, okay, they have the wherewithal to deal with this, and they can get better terms because they don't have to sign those NDAs that retail people do.
40:16Christopher Whalen:Chris, one of the things that have happened is that the retail is either sold or convinced that this is a good opportunity because it's institutional, right? That's what the institutions do. Right. That's first. Second, it's like, well, do you need the money right now? Well, you've got a high net worth person. It's like, oh, I don't need this$4 or$5 million out of my$50 million. I can leave that in for the quote-unquote four to seven, right? That's a four to seven year period that they always talk about. this issue of some liquidity event that comes on IPO slash buyout something. Meanwhile, what I see on my end, by the way, is the continuation of capital calls.
40:52Christopher Whalen:And when they do distributions, they reset those as recallable distributions for capital calls in the future. I'm like, wait, what happened with just this standard distribution that you get from an income source? No, it's a recallable. So you constantly have to feed this monster, right? That every time they get some, That's right. It's terrible.
41:10JCD:But what's - Well, think about the other side of it, though. The reason for this is that most of these big sponsors of private equity, private credit, have all gone out and bought insurance companies. So they have to feed the beast. Yeah. Now, how do you feed the beast? On the one hand, you have annuities on the liability side of the ledger. And then on the asset side of the ledger, you have private credit, loans. You have agreements, for example, by your customers where they have, you know, essentially lent money via a note. You know, these are a special type of instrument insurance companies use.
41:49JCD:So the amount of demand from these insurance companies that have been turned into private credit machines is vast. And that's also spilled over in the housing. The reason you have such a vast demand right now for business purpose loans that are supposed to be for rental properties is because of this. The insurance companies are lining up out the door.
42:11Christopher Whalen:Crazy question, and I'm not asking you to give advice on this, but I'll ask it this way. Have you thought about the opportunity to maybe short some of these insurance companies? Because historically, these guys who have these long-range type of – now, listen, some of their portfolios matched, right? The long-term nature of an annuity matched to a long-term nature of private credit, not mismatched like you have this really short-term liability with a very long-term asset, right? That's not how a lot of this is. But still, we start seeing markdowns. And if reality ever hits, that could be a problem directly to the insurance companies as I see it.
42:45JCD:I don't follow the insurers closely enough to actually take a long-short view. I have been thinking about laying down some shorts on some of the smaller, more aggressive banks, simply because some of these outliers are clearly over their skis. They're making loans with AI and all of this nonsense that we haven't been able to test because we really haven't had a recession since 2008. The Fed hasn't allowed it. So because the Fed has been so absolutely benevolent with liquidity, we have a situation where today bank-owned mortgages still have a default rate that's about zero. And what that means is that if somebody actually defaults, they have enough cash on the table that they can just buy them out, sell the house, hand them the excess, and say, get your life together, goodbye.
43:42JCD:So you don't even see the default. And then from a credit perspective, when you look at the whole portfolio, what we call loss given default, which is recoveries less charge-offs, is about zero. So that's what the Fed did. When they pushed up asset prices 50 % in resi, it solved a lot of problems, but it also created problems. Meanwhile, if you look at multifamily apartment buildings, it's been in a dump since really 2022, 2021. Loss rates are 100 % of the loan. So that's not good. It shows you what politics and affordability are doing to that asset class.
44:25Christopher Whalen:You know, it's interesting because many of the areas that you talk about where the Fed won't allow for a recession, one of my favorite things that happened, I think, in the most recent timeframe was when the Fed came to the rescue of the banks where they raised interest rates. And what happened was, of course, we saw that by going from a negative interest rate or a zero for that matter to anything other than that was an enormous differential in terms of percentage. and it sunk all these bonds because the banks thought this was going to be forever. Sure, I'll buy that 1 % bond. I'll buy that 0 % bond.
45:02Christopher Whalen:And all of a sudden, they went from 100 to 80, whatever it was. But then the Fed said, don't worry about it. Market to the maturity. How great was that?
45:10JCD:Well, they should have done more. See, bankers aren't that smart. If you look at Silicon Valley Bank, they put 40 % of the bank's book in mortgage banks. and they go down in interest rates from 19 on when Powell panicked, okay? He really panicked in December of 18. And then in 19, what do they do? They start growing the balance sheet and they were selling forwards in the mortgage market to force rates down. So by the time we get to 2020 and COVID, right? Yeah. The duration on Ginnie Mays has gone from a five down to one, which I didn't even think was possible, one year. Right. And they stayed there.
45:49JCD:And so you look at these guys at Silicon Valley Bank, and the book is prepaying 50 % a year. What do they do? They go out and they buy more. So as rates started going up, as we get into 2021, the bank was already dead. They just didn't know it. And it was funny. I published comments on the Basel proposal. And I said, look, Mickey, I want you to lower the risk weight for mortgage servicing because it's inappropriate. It's too high, 250%. But we need an idiot test. We have to have a little sit-down meeting with bankers who want to own variable duration stuff. So mortgage servicing assets, whole loans, and mortgage-backed securities.
46:33JCD:All of these things change. And if you want to see what change means, just look at the Fed's balance sheet. Look at their P &L. Because when they bought those mortgage securities in 2021, they had a duration of a year or two. Now they have a duration of 15, 18, 19 years.
46:50Christopher Whalen:Yeah, with the same interest rate, by the way. Oh, yeah, they're getting killed. In plain English, it means bad investment. Bad investment.
46:58JCD:Bad investment. If you're going to run a hedge fund, you've got to pay attention. Yeah, exactly. So anyway.
47:02Christopher Whalen:Look, so let's talk about, you do have an outlook that things are a little bit concerning. Obviously, I heard from your voice that you said that obviously the earnings and equity side of things, probably from the AI and the trade with technology was good. but you got a little wary of it towards the end of the year. You have some concern about where the Fed is, the amount of debt we have. That leads us into something, which I didn't know about you until recently, actually. Not that I need to know everything about you, but I just didn't know. Was that you are a bit of a, I think for the last, well, let's think what that is, seven, eight years, you've been a big believer in hard assets, particularly gold.
47:37Christopher Whalen:Yeah, is that correct?
47:38JCD:Yes, very much. We actually, we publish the top 100 banks every quarter after earnings, And we kind of, you know, give our readers a sense of who's performing best market and fundamentals. But we started putting together a list of stocks that can give our readers access, not just to gold and silver exposures, but the miners. And the reason for this is I've always believed in gold. I'm actually working on a book on gold now that talks about the end of the U.S. effort to try and get people not to think about gold as a thing of value. Yeah. Clearly, that didn't work. That was Franklin Roosevelt. I talked about that in my last book, Inflated.
48:21JCD:But I think, you know, the fascinating thing to me is that the stepchild, silver, which for years and years was not really considered at all once we stopped using it for money in like the 1890s, is now a huge commercial commodity. And silver prices have been going up in the past couple of weeks again. So what I've said to my readers is I said, look, both of these precious metals have different strategies. One is a monetary asset. Central banks around the world are going back to the old days. They want something that's independent of politics that they can easily trade. And it's going to, if anything, go up in value over time.
49:02JCD:Meanwhile, we have silver, which is really not a monetary asset. It's more mostly for tech. Just about everything you make in tech requires silver, fodder. Right. Right. So I've been focused on that and some of the other metals. I've got some great interviews in the pipeline, by the way. We added a funny company called Bunker Hill Mine, which is a very storied penny stock. But it's been taken over by a team from Barrick Gold that's very impressive. This was one of the biggest Superfund sites in the country. So right out of the gate, Richard Williams and his team had to go sit down with the EPA and talk to them about how they were going to manage this extremely big property.
49:44JCD:And they're going into production later this year. They're going to try and be half rare metals and half silver by the time they get their full operation up and running. I think it's very exciting. And you're going to see more of this in the U.S. There's no dirt out there for the big producers. So they're going to have to buy what we call the junior miners as we go forward in time. So I like paying attention to them. They're interesting stories.
50:09Christopher Whalen:And you have some kind of, you're a branded ambassador for a company now, right?
50:14JCD:Yes, we have a sponsor, Monetary Metals, which is a really cool company created by Keith Weiner. And what Keith has done, which was the obvious thing, is provided a return on gold. So he lends his gold to people that need it, mostly jewelers around the world, and he pays his customers a 4 % yield. See, the problem with gold is if a jeweler needs it, doesn't the jeweler just get it? How does it lend it? No, no, because it's very costly to keep the inventory you need. Oh, gotcha. Yeah, if you're an Indian jeweler or in Turkey, you're talking about 24 karat gold. Right. So you are looking at inventory that runs into millions of dollars.
50:57JCD:So what they do is they have a just-in-time kind of supply system. They charge them a fee so they don't have to have their capital fully tied up in their inventory. And he's able to give people a return on the metal, which makes it work. Because if you think about it, the institutional players have never liked precious metals because it doesn't correlate to any of the benchmarks. Right. It doesn't have a natural carry. Which is what I like about it, by the way. Just as one reference. Yes, if you have the patience to get through the periods like today when it's been selling off.
51:33Christopher Whalen:Right.
51:33JCD:A lot of, you know, the small investors who are price oriented look at gold prices the way they look at stock prices. If you go to the Far East, that's very different. Very different. Because they're talking about taking physical delivery and putting it in the bank and forgetting about it.
51:50Christopher Whalen:Well, but you look at India, they have like a clear and definitive cycle of the wedding season that is all gold-based. Yes. Right? They're all about that. Right?
52:00JCD:Totally. Whereas here— Jewelry is seen as a way to amass wealth, and they can trade it because it's 24 karat. Yep.
52:08Christopher Whalen:And the difference between gold, which we don't know if we're going to ever get to this point, but diamonds, whoever thought. Fake diamonds or lab-grown diamonds. The diamond industry, have you seen the price of a diamond? Oh, my God.
52:20JCD:Yeah.
52:21Christopher Whalen:Horrible. Horrible.
52:22JCD:I know. And now you— Well, listen. Who knows what we were— When I was in Villanova, I did sports photography. Yeah. And my first camera, which I got from a friend of my parents, was a Leica. Oh. And it had a 180 zoom on it that was so heavy you had to put a monopod under it. It was made from quartz from the Baltic. Oh. That's where they make lenses, right? Right. But over time, the Japanese started manufacturing crystal in labs, which was much lighter, much more flexible in terms of making lenses. And they won. Even though the color spectrum on that Leica, you can't replicate that with artificial glass.
52:59JCD:It's made out of quartz. So, you know, it's funny because things change. There's nothing we can do about that. And diamonds are the same problem. They can make them in labs and they're flawless. Yeah. Amazing. So let's close with this and talk about, you know, after you're, you've studied financial
53:20Christopher Whalen:crises. I mean, obviously anybody in the fixed income area, banking area, has to have a career that they say studied financial crisis because that's where they blossom from usually. That's where they germinate, right? That is the banking oftentimes. Unfortunately, that's what it is. what's one lesson that you think maybe, you know, you can impart to investors that, you know, before the next one arrives, I guess, you know, if there is one? Or is the Fed just going to permanently put a no, you can't do that on the recession posture? Well, I think our current Fed chairman, Kevin Warsh, who I've known for a long time, is not going to do what the Fed did under Powell and Janet Yellen.
54:06JCD:Specifically, if he has to ride to the rescue of the Treasury market, the way we did in March 2020, he would keep the spigot open until the crisis was gone. And then he would shut it off. So the trouble for the U.S. economy is that we've used falling interest rates for 35, 40 years to manufacture nominal growth in the economy, while at the same time our people were slowly losing ground to inflation. When we had COVID, though, the rate of inflation accelerated rather dramatically. And I would tell you it's actually much, much higher than the statistical evidence. I would believe you. And I think that we're going to see perhaps even double-digit inflation by the end of this year because fuel prices, prices for things like fertilizer that you need sulfuric acid for, all of these things were coming from the Middle East.
54:59JCD:The whole world had optimized around the Gulf states, some producers in Asia too, in terms of price. So, for example, we don't refine fuel on the West Coast of the United States anymore. There are no refineries in California. So I think, you know, unfortunately, the future is going to be about scarcity and inflation. And in order to protect yourself, you're going to have to do precious metals. You're going to have to carefully look at real estate as a shelter. But you've got to remember that there's going to be an awful lot of Americans out there that aren't going to be able to do anything. You know, I think about the number of people who are literally trapped in New York City who can't leave.
55:40JCD:and I've said for years, we should be resettling low-income families. Because think about our experience. We moved down to Florida this year. Yeah, you're right across from me, by the way. You're direct west. Yeah, I'm in Fort Lauderdale. You're over on the west coast. That's right. Yep. So when we left New York City, we went to Westchester, which is one of the most affluent communities in the United States. Cut our costs in half. Yep. In half. Yep. We moved down to Florida, we cut our costs in half. Right. When we sold our house in New York, the price had doubled in five years. That's crazy. But it's because they don't build new homes in New York State, the politics and the costs and everything else.
56:19JCD:So I think inflation, unfortunately, and affordability, if that's what you want to call it, are going to be the key benchmarks you're going to use for protecting assets and protecting yourself and your loved ones. And, you know, I've rotated to a focus on precious metals. I still follow the financials because people like stocks, right, the shiny object. But, you know, I think long term people are going to have to focus on gold and silver as just a way to shelter themselves.
56:49Christopher Whalen:I guess the last question to follow up to that is this. We know that the Strait of Hormuz is running 10, 15 percent of capacity. We know that the reserves around the world in terms of oil reserves are down substantially. We know that the strategic oil reserves are also down substantially. And why the price has not escalated is probably due to the fact that all the strategic reserves have been purged. And probably why Trump, you know, said, OK, war is over because he recognized that, man, any longer we got a real problem here. You know, between the urea and the sulfuric acid and all that stuff coming through and, you know, on and on and on and on.
57:25Christopher Whalen:Now, they're finding some very interesting ways to get around some of this, a little bit of a longer way. Why are markets still not reflecting, I would say, the risk in your thesis that we're going to have this inflation moving higher by the end of the year, next year, whenever it is?
57:40JCD:I think it's just because we're still not that far from the start of the war. I have a couple of interviews with a dear friend of mine, John Dysart, on the website. John was a columnist for the FT for a long time. And he's one of the sharpest energy analysts I know, both fuel and also electricity. And he said to me, he goes, Chris, there's nowhere else to get this stuff. The Gulf states and certain plants in the Gulf that the Iranians targeted early on and destroyed, gas plants where you create other products as a part of the gas production cycle. It's going to take years to fix these things. So what's happened, and you ask a really important question, is they've been drawing down stocks all around the world.
58:25JCD:There was an awful lot of product on the seas when this war started. So all of those ships arrived, they all offloaded, and you started to see behavioral changes by the Chinese, the Koreans, others, who have stopped exporting. And they're essentially husbanding their existing supplies so that they can take care of their people. China, for example, stopped exporting sulfuric acid last year. They just said no, because they're worried about fertilizer out on the farm. And I think that the U.S., frankly, is going to have to adopt some kind of cooperative effort, if not rationing, in order to make sure that we have fuel and lubricants where we need to have it.
59:09JCD:They will create production capacity here over time. Chevron's got a big lubricants plant that's going to come online early next year. But it's not enough. And I do think medium term, and the reason your question is so important is you're going to see countries go back to more of a national approach to energy security. We're not going to just be able to follow price and say, well, you know, we'll buy diesel fuel, for example, for the West Coast of the United States from Korea, which is what we were doing. The U.S. was actually exporting diesel through the Gulf over to Europe and to other countries.
59:46JCD:So all of these things are going to have to be adjusted. And the politics of this as we go into the midterm. You start messing with energy.
59:54Christopher Whalen:Energy is a core factor for world economy and for individuals and for politics and for the pocketbook of individuals. You start messing with that and you start going to more of a nationalistic style of that and hoarding, if you will, that we have, you don't. I mean, what happens to India? What happens to even South Korea? That's right.
1:00:11JCD:But remember, West Texas and Brent are the wrong things to look at. Right. When you think about oil, you've got to say to yourself, have I ever consumed a barrel of oil? The answer is no. You consume gasoline. You consume other types of refined products. So the question is, can I get the oil that I need to put into this refinery, which is tuned up to use this sort of oil? Right? Yep. So, for example, we still refine product for Mexico. The top northern half of Mexico gets refined product from Deer Park in Texas because they just didn't have the cash to build their own refining capacity. It's actually cheaper for them to ship the oil up here, return it into refined product, and send it back down there.
1:00:56Christopher Whalen:Amazing.
1:00:57JCD:That's the economics of energy because it's a very capital-intensive business.
1:01:01Christopher Whalen:Yep, very capital-intensive. And not something where you say like, ah, we'll skip that. No. It's okay. Listen, Chris Whelan, pleasure having you. Chairman of Whelan Global Advisor, publisher of the Institutional Risk Analyst. Great books out there. Also affiliate, Branded. I want to be a Branded Bastard or something. Branded Bastard. We'll have all the information on how to get in touch with you over on thedisciplineinvestor.com. Episode number 984. By the way, approaching our, listen to this, you may not know this. In about six months, 20 years of doing this podcast. We were doing podcasts when people were like, what's a podcast?
1:01:42Christopher Whalen:What does that mean? And including me, by the way.
1:01:45JCD:I've had to get tuned up. I had to get cameras and lights and everything else. Yeah, yeah. We're all set. But we'll do it again. Maybe I'll run over there and we can do it together. Sounds great. All right, I'll talk to you. Thanks. Thank you, sir. Appreciate it.
1:01:58Christopher Whalen:And a little update, just a small update on the meniscus. I'm walking around getting PT done. Hopefully I'll be able to, I don't know if I'm going to play pickleball anytime soon, maybe a few weeks of rehab to go before the next leg of this. But I did ride a bike or the stationary bike as well as do the PT. And that was pretty good. So you have that. Chris Whalen, great guest. We have Tommy Thornton coming on from Hedge Fund Telemetry next week. I'm excited about hearing about some of his DeMarc indicators and things that he's looking at in the markets right now after a pretty unbelievably crazy week in the markets this week.
1:02:35Christopher Whalen:Thanks for joining this week and every week. And of course, as I mentioned, if you do want to sign up for the meetup, the JCD Memorial Meetup in Fort Lauderdale, go over to dhunplugged.com and click on the button. It's at the top right there. You'll see it on the right-hand side. And make sure to reserve a spot. No cause to do it, of course, but we want to know who's coming and what's going on. So with that, I just want to, for the final time, play this memoriam, this eulogy, this tribute to John C. DeBorak. Thanks for listening. It's hard to imagine saying these words today, but today we're remembering my dear friend.
1:03:20Christopher Whalen:And we're honoring my longtime podcast partner, John C. Dvorak. You know, John's passing is a tremendous loss for the entire podcasting and technology community. There's no question about that, because for decades and decades and decades, he informed, he entertained, he challenged and often delighted audiences about all his great information, knowledge, and way of being. He was a man with sharp intellect, independent thinking. He was unmistakable in his sense of humor. Sometimes dry, but a great sense of humor. He never hesitated to question anything about anything, and especially about conventional wisdom.
1:04:07Christopher Whalen:We know that from his time on the show, DH Unplugged, and No Agenda, and all the times on TV and other podcasts he's done over his career. He did so with style. He did so with grace. He did so with a sense of humor. And that was entirely all his own. For me, the loss is, it's deeply personal. I mean, John was my friend. He's my co-host for 18 plus years with energy and insight and information and countless memorable experiences and times where we talked about things that maybe weren't that interesting, but he made it interesting. The conversations we had each and every episode was unbelievable, and we didn't always agree on anything.
1:04:54Christopher Whalen:No, we didn't. In fact, a lot of times we disagreed, but in fact, over the years, we came close to understanding what each other had and the unique ability that he had to put it all in perspective and to create a better understanding for all of us. He made our audiences smarter and friendships richer. And Tuesday nights are never going to be the same, ever. Every Tuesday night for the rest of my life, I'm going to remember that, oh, it's 9 o 'clock p.m., Eastern Time. I've got to be on show and on live with John right now. The conversations we had, the laughs we had, the debates in that familiar voice are things that I'm going to miss more than words.
1:05:38Christopher Whalen:I'm sure you are as well. but while there's a void that can never be filled we're going to continue to find ways to remember John and beyond what this life has the impact that he had on all of us we're going to move forward because that's what he would have wanted I'm sure of that he believed in looking ahead he did and staying engaged and continuing the conversation. He leaves behind an incredible legacy of family who I consider part of and I'm honored to be a part of and much more than just behind the microphone. He's inspired generations of listeners, technology buffs, creators and thinkers to ask questions, to wonder, to think independently and never be afraid to speak what they think.
1:06:42Christopher Whalen:He's going to be missed by many. I know I can't even begin to tell you. I'm kind of numb to this and I can't really, I'm tingling because the thought of not being able to talk to him is, it's a big hole in my heart, in my life. He's going to be remembered by all who knew him and I miss him. Rest in peace, John. Thank you for your friendship and for sharing your remarkable gifts with me and all of us. We'll miss you. This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principle and past performance is not indicative of future results.
1:07:26Christopher Whalen:The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz & Company, Inc. and investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz & Company is properly registered or is excluded from registration requirements. Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement.
1:07:58Christopher Whalen:Hypothetical scenarios or forward-looking statements are for illustrated purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates of Horowitz & Company.
1:09:01guitar solo
1:09:05We'll be right back.
From the publisher
Saying Goodbye to JCD.
The first test of the Fed Chair – with a miserable outcome.
Some eye popping moves.
An update on the meniscus repair.
And our guest this week – Christoper Whalen – Publisher of The Institutional Risk Analyst
NEW! DOWNLOAD THE AI GENERATED SHOW NOTES
Christopher Whalen is one of America’s best-known independent banking analysts and financial historians. He is Chairman of Whalen Global Advisors and publisher of The Institutional Risk Analyst, where he analyzes banks, credit markets, housing finance, and financial regulation. Chris has spent decades studying the U.S. financial system from both the public and private sectors and is the author of Inflated: Money, Debt and the American Dream. His market commentary is widely followed because he’s willing to challenge conventional thinking—and often does so well before consensus catches up.
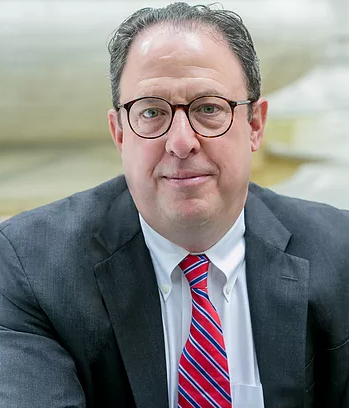
Chris recently became a brand ambassador for Monetary Metals, a company whose approach to making physical gold a productive asset aligns with views he’s held for years about the role of gold in a portfolio.
Check this out and find out more at: http://www.interactivebrokers.com/
Looking for style diversification? More information on the TDI Managed Growth Strategy – HERE
Stocks mentioned in this episode: (MSFT), (TLT), (META), (INTC), (AMZN)