
In short
The Disciplined Investor Podcast - Episode Summary (#945)
Episode Title
Valuation Cliff Release Date: November 2023 Host: Andrew Horowitz Guest: Vitaliy Katsenelson Podcast Description: The Disciplined Investor Podcast
---
Overview In this episode, Andrew Horowitz discusses the implications of current market valuations with guest Vitaliy Katsenelson, focusing on themes such as inflation, the overspending of big tech companies, the recent Fed rate cuts, and the impact of AI on the workforce.
---
Key Topics & Discussions
- Market Conditions and Consumer Sentiment
- Seasonality in Markets: The end of the year is usually a strong period for markets, but current consumer sentiment raises concerns.
- Income Disparities: The lower-income demographic is particularly stressed, leading to reduced spending capabilities despite overall retail sales remaining stable.
- Inflation Concerns: While inflation has decreased, it remains at 3%, above the Federal Reserve's target. The compounding effect of previous higher inflation rates is a concern for consumer purchasing power.
- Federal Reserve Actions
- Rate Cuts in Question: The Fed recently cut rates by 25 basis points without clear economic indicators, raising skepticism about their decision-making process.
- Quantitative Easing: The Fed's decision to stop balance sheet runoff and resume buying bonds indicates a return to quantitative easing, which could have implications for market stability.
- Big Tech Overspending
- Spending Trends: Companies like Meta are investing heavily in AI, raising concerns about their financial sustainability and the potential for overspending to impact their market positions.
- Valuation Worries: Katsenelson expresses concerns over the massive capital expenditures (CapEx) without clear returns, particularly around AI and tech companies.
- AI's Impact on the Workforce
- Automation in Distribution Centers: A case study on Amazon's distribution centers highlights the shift towards automation, which blurs the lines between human labor and machine efficiency—leading to fears about job displacement.
- Potential Job Market Shift: AI is not only affecting blue-collar jobs but also encroaching into white-collar professions, raising questions about future employment landscapes.
- Valuation Concerns in Current Market
- High Valuations: The discussion touches upon the high valuation levels in the market, suggesting that future returns may be compromised if current prices do not reflect true value.
- Investment Strategy: Katsenelson emphasizes the importance of investing in fundamentally sound businesses that one would hold for the long term, irrespective of market fluctuations.
---
Key Takeaways
- Consumer Strain: Consumers, especially at the lower-income level, are feeling the strain of inflation, impacting their spending habits and economic sentiment.
- Skepticism About Fed Policy: The Fed's blind rate cuts and quantitative easing raise questions about the soundness and transparency of their economic strategies.
- Big Tech's Future: Overspending by big tech could lead to significant challenges if economic conditions worsen or if AI investments do not yield expected returns.
- Job Automation: The rise of AI and automation is expected to fundamentally change job markets, with implications for both blue-collar and white-collar workers.
- Valuation Discipline: Investors are encouraged to focus on purchasing fundamentally strong companies, maintaining a long-term perspective despite current market exuberance.
---
Conclusion The podcast episode presents a critical analysis of current economic conditions, the implications of AI on jobs, and the importance of prudent investment strategies amid high market valuations. Listeners are urged to remain vigilant and thoughtful about their investment choices in these uncertain times.
---
Listen to the full episode: [The Disciplined Investor Podcast](https://thedisciplinedinvestor.com)
Follow the Host: [Andrew Horowitz on Twitter](https://twitter.com/andrewhorowitz)
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Transcript
Automatic transcript. May contain errors.0:00Andrew Horowitz:This episode is sponsored by Interactive Brokers. And are you ready to take control of your financial future? Meet Portfolio Analyst from Interactive Brokers, the free all-in-one dashboard that lets you consolidate, track, and analyze all your financial accounts in one place. You don't need an IBKR account to use it. Just connect your accounts and see your complete financial picture, your investments, performance, and allocation all on a single screen. Plus, you can plan smarter with IBKR's new tax and retirement planners, built around your goals and your market assumptions. Get deep portfolio insights with detailed risk assessments and compare performance against more than 300 benchmarks.
0:43Andrew Horowitz:Plus, manage with confidence thanks to GIPS verified returns. Ready to get started? Sign up for a portfolio analyst, which is free for everyone, at ibkr.com slash freepa. Interactive Brokers, the best informed investors, choose IBKR, member SIPC.
1:07Vitaliy Katsenelson:The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast. This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz & Company, from seed through harvest, cultivating financial success.
1:34Andrew Horowitz:We got Swiss cheese agreements. Overspending by big tech, that could be their downfall. A rate caught in the dark. and our guest today is Vitaly Katzenelson, discussing hopefully some basic math of this market and find out what's going on with valuation. Maybe even find some bargains. All this and much more on episode number 945 of the Disciplined Investor Podcast.
2:14Andrew Horowitz:Hey, it's November. Welcome to the fun part of the year. It's kind of like a basketball game, you know, where the last few minutes, or the only thing that really matters, last two, three minutes of a basketball game, it's like, okay, it's tied up. It's within three points, been five points. It lasts forever. And that's kind of like what happens towards the end of the year. We have that seasonality that's all important. It's not exactly like the last two minutes of a basketball game, I give you that, but the seasonality and the importance of the last couple of months of the year, in particular over the last, well, I don't know, a couple of decades, as we get closer and closer to that end of year holiday season, the seasonality that we see when things pick up.
2:52Andrew Horowitz:But this year could be something to watch, something different. And I'll tell you why. You have a consumer that is stressed. Nothing really terrible on the whole when you look at sentiment, when you look at the totality of retail sales, when you look at it from afar. But when you start digging down, looking into the details of what's going on, there's some real problems. There's some cracks in the armor, and it's a real serious concern. The lower end of the income spectrum and their ability to spend, listen, they're just tapped out. They're exhausted. The ability for them to come up with more money in the face of goods costing so much.
3:30Andrew Horowitz:You may say, what do you mean? We don't got much inflation. We're being told that there's not a lot of inflation. We're coming down. In fact, I heard a few politicians recently say that inflation has been coming down and down and down. Things are looking a lot better. And yeah, yeah. Inflation does not run away like it was 8%, 9%, or 10%. But the fact is it's at 3%. 3%, which is 1 % higher than what the Fed is looking for to begin with. We still have an inflationary market. And somehow, I don't know how, which we'll talk about in a second, the Fed, in the dark, without economic inputs, cut rates.
4:08The 3 % inflation that we see is on top of the 4%, the 5%, the 8 % that we saw a few years ago.
4:16Andrew Horowitz:The compounding effect of that on prices is monumental. The ability for individuals to absorb that is becoming too much. Their pay, their salaries, their overall compensation is not keeping up. That being the case, you have to wonder what's going to break. How is this going to all play out? And why are the markets continually making new highs after new highs? Yes, there was a little bit of backup here, but I'm saying generally speaking, when we look at where things are, the multitude of years and the multiplication factor, the compounding of the inflationary environment on prices is clearly adding up.
4:58Andrew Horowitz:And again, the politicians are saying, you know, hey, inflation is coming down under Trump. It's great. You know what we've seen lately? And yes, inflation has come down over the last few years, but that's not who we look for to find our data. If you're looking at one station, CNN or Fox, if you're listening for politicians to tell you exactly what's going on, that is not the way that we look at data. Because it's twisted and it's meant to be either looked at in an unfavorable fashion or a favorable fashion to benefit whoever is speaking. You know, there's an age-old question that's asked. How do you know when a politician is lying?
5:42Andrew Horowitz:Well, when their lips move. Right? I mean, the politicians of today, unfortunately, have a lot of, they're really more concerned about their own individual stature and their continuation of being able to be elected than they are in telling us what's really going on. Now, we know that. There has to be, and this is something that I've said many times, that we know that the Fed is a cheerleader, but they have to be. That is their job. You can't take that away from them. But we've got to look beneath the surface and understand what is actually going on because it's our money that's on the line, not theirs.
6:18Andrew Horowitz:Don't forget, the government's closed, what, 33 days? The senators, the congresspeople, they're getting paid. They're not skipping a beat. Now, the Fed came out this week and they dropped rates by 25 base points, right? A quarter of 1%. They also announced an end to the balance sheet runoff starting in December. In other words, they're about to start buying bonds again. You know what we call that, right? That's quantitative easing. That's what we call it. And during their recent, that was Wednesday, during their recent presser, Two o 'clock was the rate announcement. We all knew that it was pretty much baked in stone that we were going to get this 25 basis point reduction.
7:06Andrew Horowitz:And there was some talk about kind of greasing the skids into the actual meeting that they talked about that probably we're going to start slowing down on the bond runoff. So we knew that was going to happen there too. But they were really cagey. When I say they, it was. Chairman Powell, was a bit cagey about the next possible rate cut. Talking about how, well, December, we'll see what happens. Because they, of course, are data dependent. The December rate cut odds have gone from 81 % to 72%. So there's still a general feeling the Fed is going to continue cutting. But as of right at this exact moment, and I don't think this is going to last forever, but right now, right where we are at this day right now, They're doing this totally blind, in the dark.
7:56Andrew Horowitz:The Fed, who is supposed to be this data-dependent organization, they keep on touting it as we are data-dependent, they cut rates without knowing all the data. And the data that they do know, which is CPI, is climbing, or at least steady at 3%, above their target. The data they don't know is about employment. In fact, rates went up after the meeting. After the rate cut, we saw the tenure actually go up. Now we know about the Fed. This particular meeting in itself explained to us and taught us a really good lesson. If we didn't know before, we know they're full of shit. We know that they don't have all the data to make a well-informed decision, yet they cut rates and spent 90 minutes trying to explain their logic and their potential next move.
8:49Andrew Horowitz:We saw that one of the characters that was recently appointed wanted a 50 basis point cut without knowledge of all the data. We know it's all a bunch of BS. The environment that we live in, that we're all supposed to believe without asking any questions, right? The China deal. Oh, the China deal. What a crock. China's done it again. They outplayed us just like the last time. I remember sitting right in front of a microphone just like this on a podcast some time ago, talking to you about exactly what I'm going to tell you right now. They know how to work this team, and it's eerily similar to what we saw during Trump's first term.
9:38Andrew Horowitz:These so-called deals, right? The announcement of these deals. We got a deal. We got a deal. The best deal ever. Oh, my God. An excellent deal. Perfect deal. They're much more optics than substance. President Trump seems to be really desperate. For whatever reason, I don't really understand. I don't understand the psychology about this. I really don't. I mean, I can speculate. But I don't really get it. But this unbelievable need to prove something. But what are we getting? We're not getting deals. We're getting these Swiss cheese agreements full of holes, just like the Trump golf course. Full of holes, just like any golf course.
10:20Andrew Horowitz:That's what these agreements are. They're not deals. This is a master class in negotiation from China. And a reminder that, you know, the headlines themselves, they don't always equal progress on a particular area. And what do we get out of this deal anyway? Well, China got lower tariffs. We know that. We may have received some soybean purchases. Good for Scott Besson, who seems to be a soybean farmer of sorts. He admitted that last week. They're going to be buying some soybeans. Woo-hoo! Woo! They're allowing the rare earth sales back to the U.S. You know what that is? That's just back to where we started when Trump took office.
11:08Andrew Horowitz:This is a chess game. China did a great block by adding the rare earths. We hiccuped by putting on those tariffs over the weekend that came off. Remember that whole thing? 100 % tariffs on China that's going to come. That came off. That disallowed us from doing anything because they put a great block there on our check. And then they came in for the checkmate. That basically allowed them to say, you know what? You want to do a deal? No. I don't think so. The tariffs and all that, that's great. You need these rare earths just to be clear. We'll buy some soybeans. It's good for us. We don't care.
11:48Andrew Horowitz:You lower the fentanyl taxes, that's great. So I'm getting more and more skeptical about the backdrop and a bit more concerned of how investors are taking on this whole idea. And then more importantly, what we saw late in the week last week was the reports from the Metas, the Microsofts, et cetera, the hyperscalers, if you will, or the AI spenders. And let's forget about this whole vendor financing concern, but the actual massive CapEx, I mean, meta, during that conference call, it was like, what? How much are you going to spend? This is like what Mark Zuckerberg did during his quest to dominate the alternative reality or when he was building the glasses
12:42Andrew Horowitz:I got one in my closet. The Oculus, right? When he was doing the,
12:49Andrew Horowitz:I can't remember the words for it. You know, when he was building out that whole thing where it was going to be, you know, nobody's going to be in meetings anymore and everybody's going to be basically in, you know, online in this virtual reality. That's what it is, virtual reality. This virtual reality setup. And everybody's like, no, I don't think so. Well, investors gave the nudge to Zuckerberg last week and the end of the week after the earnings came out. And particularly when they came out with their conference call with how much they were spending. It's like, you know what? Hey, maybe going a little bit far.
13:18Maybe this spending bender is going to, you know, make investors not as happy.
13:25Andrew Horowitz:And OpenAI came out last week with a restructuring. Microsoft now owns 27 % of that deal. Now OpenAI is looking to do an IPO with a trillion dollars of valuation. But wait a second. Wait, hold on. Don't they have plans and commitments and promises already for payments over the next few years for that number? And if Microsoft owns a big piece of that, even though the valuation is a trillion, they're not getting a trillion dollars in. Maybe a few hundred million? Billion? but you got commitments to pay hundreds and hundreds and hundreds of billions to Oracle and this company and that company. Where's that money coming from?
14:12Andrew Horowitz:So many questions. So little time. That's what's happening. I mean, I got to tell you, I'm going to be watching this very carefully. We did cut down some of our positioning and do some real rebalancing of portfolios over the last few weeks because my concern is being raised with the current valuations. Look at the Case-Shiller, you know, the Cape Index, and just the amount above where the ratio is right now is getting a little spooky. The fact that investors are throwing money at everything, it's getting a little concerning. I've seen this movie before. And by the way, it doesn't have to end in a crash and all that, but it needs to settle out.
15:00Andrew Horowitz:So we're waiting and being patient in some areas. Let me get to our guest. Before we do so, I want to talk one more time about interactive brokers and ask you a question and something to think about. Here it is. Will the U.S. Fed Fund's target rate be above 3.625 % at the FOMC meeting ending December 10th, 2025. At IBKR Forecast Trader, the yes was recently at 23 % and the no was at 75%. With Interactive Brokers Forecast contracts, you could trade on future events like climate change, the economy, politics. You simply choose yes or no. And if you're right, you get paid. It's that easy. Explore the data, spot the trends, and make your prediction.
15:49Andrew Horowitz:Trade forecast contracts and interactive brokers and earn a dollar for every correct prediction. Now, forecast contracts are not for everybody. They're not suitable for all investors. Go make your prediction. Go to ibkr.com slash forecast and start predicting today. The last trading day for this contract we talked about, December 10th, 2025.
16:17Andrew Horowitz:All right, so let's get to our guest, Vitaly Katsanelson. He's been on many times. Great guy. Good friend for many, many, many years. He's chief investment officer at Investment Management Associates, a value investment firm based in Denver, Colorado. After he received his graduate and undergraduate degree in finance, cum laude, from the University of Colorado at Denver, he finished his CFA designation, and he wanted to keep learning. He does teaching. He writes. He invests. Lots of things I want to talk about, some of his recent writings, some of his recent ideas, and talk about valuations. because he's a value guy.
16:48Andrew Horowitz:So he really gets into the fundamentals. So something we really, I think, need to focus on right now. So let's get right to that discussion. So Vitaly, it's been a while. How are you? Andrew, I'm doing great. It's so, so delighted to be on your podcast. I'm always happy. Always happy that you're here. How's your son, by the way? Last time I saw him, you and I were walking for miles and miles and miles, like a lot of miles, a lot more miles than I thought we were going to walk, down a strip on the beach down in Miami.
17:15Vitaliy Katsenelson:That's right. So listen, my son graduated from CU Boulder. He had a job in corporate finance for a company here locally for a while and didn't like it there and decided he wants to join IMA. And now he is running our marketing. Oh, very nice. So it's like the way I explain it to people. So he does marketing, so I don't have to. Ah, I like that.
17:44Andrew Horowitz:Well, it's also you set up a succession plan in a way.
17:48Vitaliy Katsenelson:To some degree. I mean, he has very little interest in investing. But he learns how the company works, et cetera. So if he decides he wants to stick around, he may become a CEO or something.
18:07Andrew Horowitz:It's always good. You can have lunch with him whenever you want.
18:10Vitaliy Katsenelson:You know, every time I come to work, I kind of pinch myself. I just, I get to spend time. First of all, I have a great team here, but I just kind of get to spend time with my son and just, it's phenomenal. Great.
18:21Andrew Horowitz:So let's talk about your time because I read this article you wrote recently about Amazon, which actually, you know, is an amazing company. We know, we all know them and love them, but you had the experience of spending time actually in a warehouse in the light and the dark side and then talking about how they do things and what they do and you were just blown away.
18:41Vitaliy Katsenelson:Yeah, so I went to visit one of their distribution centers in Denver. And it's about 2 million square feet. Think about maybe the size of, like it's on three stories, 2 million square feet, the size of maybe, I don't know, 40, 50 football fields kind of thing altogether. And when we showed up there, what really blew me away is this. Imagine you have this area where on the perimeter of this, you have almost like a track. And this is where people walk. This is where the goods have been delivered. And then two-thirds of the warehouse is dark, completely dark. And then one-third is lit up. And the dark part is basically fenced up.
19:34Vitaliy Katsenelson:And this is where inventory lives. But inventory lives there on the shelves that's been basically been transported around by these robots that look like lawnmowers. So you have this lawnmower kind of slide under the shelf, lift it up, and bring it up to this area, what I call a DMZ zone, where the lightness and darkness kind of meet. and under DMZ zone, you basically have hundreds of stations where you have people taking stuff from that shelf and putting it into bins. But what's important to understand is if you pay attention close enough, you realize these people there, they just look at the screen and the screen says on the row five to the right, pick up this item and it has a picture of it, pick it up and put it in the bin too.
20:35Vitaliy Katsenelson:They do this, the computer counts how many seconds it took them to do this, and then the next instruction comes in. And I watched it, and I realized people who are doing this are almost like middleware. It's kind of as good as the most, what they were doing was completely, completely mindless. And if you spend enough time looking at this, at the distribution center, you realize these people come to work for 10 hours a day, four days a week, and the job they're doing is basically incredibly robotic. There is a single thought, goals into what they're doing. And I had these complex feelings. And so then the whole distribution center is basically run by a computer.
21:35Vitaliy Katsenelson:It's already run by the overlord of computer. In a sense, the second you order the package, the algorithm decides what's going to happen, like makes millions of decisions to which shelf to bring to which person.
21:50Andrew Horowitz:And the interesting thing you saw, though, I have two things I want to talk about. I want to talk about light and dark, so remind me about that. But there is no like A, B, C, D, E, F, G. There's a randomness. The particular product could be on any shelf anywhere, but it's known by the inventory system where all that is. Like an individual would not able – if you were an individual going into that sector, the dark sector, we turn the lights on, for example, and you would be like, where is it? There's no rhyme or reason. You could have paper next to perfume next to soccer balls.
22:26Vitaliy Katsenelson:No, absolutely. So there's 10 ,000 shelves that are randomly standing on the floor. And the computer knows where every shelf is. And the computer knows where every single item is there as well. And the reason I'm kind of drawing the dark and light comparison is because computers, the robots don't need light. This is why two-thirds of the warehouse is dark. And it's the light part where humans are. But the interesting part is this. Like I was, after the tour, I was talking to my colleague and I said, this whole dark section looks dystopian. And my colleague said, no, Vitaly, it's the human part that looks dystopian.
Read the full transcript
23:09Vitaliy Katsenelson:And the reason the human part looks dystopian because even though there was light, but the job that people were doing, they were basically following directions by algorithm, what algorithm told them to do. and the IQ in that distribution center lied completely in the algorithm. The algorithm made every single decision there. And so I kind of, when I left the distribution center, I had these complex thoughts. That distribution center employed 3 ,100 people. And I can see that in five or 10 years, this whole center, that whole distribution center will go dark. It's going to have probably 100 people just dealing with edge cases and maybe turning on the lights and turning off the lights.
23:56Vitaliy Katsenelson:I don't know, actually.
23:57Andrew Horowitz:There will be no light switches. The point of the lights, by the way, it's not an issue of whatever. It's just, they don't need them on. There's no reason to have them on. That's the point. Exactly. Yeah.
24:06Vitaliy Katsenelson:No, that's exactly right. But then I realized, okay, so 3 ,000 people will lose those jobs.
24:12Andrew Horowitz:Yep.
24:13Vitaliy Katsenelson:But also on one side, you kind of feel sad about this. But then you realize, my God, I'm not sure I would want my kids to have those jobs. Right, right, right. I'm not sure because that is a job, like what you have to understand is this. When, let's say you work at Walmart or Target or whatever, you at least see people and you socialize with people and you have interaction with people. Here, you are in basically in this warehouse where you're wearing headphones because it's too loud for 10 hours a day, and all you're doing is just following the instructions computer tells you to do, and you have almost no human interaction at all.
25:00Andrew Horowitz:Yeah, but I think you're being too nice, my friend. There are some people that that is the job that there really is appropriate for them. There are people that are ticket takers at the toll booth for years. You know, I think about that all the time. I'm like, oh my God, you know, could I imagine being stuck in that toll booth for hours and hours and hours? The bridge tender. How about the bridge tender? All he does is talk on the radio. Please open. Okay, we're opening. We're closing. Okay. I'm just saying this. But the point is that hopefully if there's an upshot here, the upshot is that maybe the machines will take over and then give the opportunity to that person to actually do something that may be much more, if that was suited, but something that is much more rewarding.
25:45Vitaliy Katsenelson:You hope so. So this is why I had complex thoughts, right? Because on one side, I'm not sure. Maybe you're right. Maybe some people like to have those jobs, like actually want to do this.
26:00Andrew Horowitz:Right.
26:01Vitaliy Katsenelson:There's definitely people that like mindless work. For me, people in my epic circle would be crushed if they had to do the job. Yeah, I get it. But maybe you're right. But you're right about that. And those jobs, but here's the interesting part. A few weeks ago, CEO of Walmart came out and said, despite us opening new stores, they're going to basically put freeze on hiring people in the warehouses. And I can see, you know, then a week later, Amazon came out, actually maybe last week I think they came out and said, they're going to be laying out 14 ,000 people in those actually white-collar jobs.
26:44Andrew Horowitz:Right. I think 30 ,000 in total. Oh, is that? Yeah, okay. 30 ,000 in total, 14 ,000 or something like that was in management or something, or something that they overhired for. So the, so my, I have a lot of, a lot of conflictive thoughts on this.
27:03Vitaliy Katsenelson:In the past, when if you and I talked about, so, so this is like, this distribution center is a version nine.
27:13Vitaliy Katsenelson:and maybe it's six or seven years old and there is already version 13 that's even more automated than what I saw. But Andrew, five years from now, 10 years from now, the distribution centers will have very few people. It's just going to be computers doing all the work, the robots doing all the work. And I was thinking a lot about AI because when we were thinking about in the past about AI, this is what we were thinking about, right? It's this kind of mindless jobs being gone, okay, kind of automation. But what we start seeing is that the EI is actually now going after white-collar jobs as well, and those are much higher-paying jobs.
27:58Vitaliy Katsenelson:So in the past, when people asked me what I thought about the impact of EI on the economy, the argument I would make was very simple. I said, listen, 100 years ago, 40 % of the country worked on the farms. Okay. Then after automation, after the development of combines and automation, today we have maybe 2 % or 3 % of people working on the farms, and we produce a lot more and export a lot more. But those people went to work on car factories. Now they're doing jobs that did not even exist 10 years ago. like search engine, I don't know, SEO, like software engineer did not exist. These things weren't exist.
28:41Andrew Horowitz:Yeah, I get you. Right. Sure. Yeah, exactly.
28:43Vitaliy Katsenelson:So there's a, but what's, what I think is different this time is AI is that I think the speed of the speed is so much faster and it's so much more pervasive across so many sectors, so much more horizontal. It impacts everything. and that's really like that's really introduced a lot of uncertainty and well right now we're
29:14Andrew Horowitz:riding the high right now we're riding the high of the expectation and how much more productivity it's going to provide because you got to admit that the amazon what's an amazing thing about amazon the company the book company that was originally started with jeff bezos back in the 1990s was that everybody thought it was going to fail because they were a book company. And by the way, if they remained a book company, they probably would have failed. You know, just a book delivery company. Even though there's some Barnes & Noble still hanging around out there. But the fact of the matter is that they saw the opportunity and what they were doing back then in that they needed this machinery and this AWS style at the time, the web services, to do what they did and they said, wait a minute, this is fantastic.
29:55Andrew Horowitz:And the same thing is happening with the distribution. where they created not only great distribution, but state of the art stuff that is allows them. I mean, it is pretty unbelievable that I click a button and Amazon says it'll be there in four hours. You know, is it unbelievable? Like, well, that's no big deal. You can always get food delivery in an hour, what's, you know, fresh food delivery, but you know, you can find some obscure product and the worst it's going to be is maybe a day or two later. Yeah. And we had to refocus on how we did things in life because the old days was like, I'm going shopping.
30:29Andrew Horowitz:I need this stuff. I need it now. We didn't want to wait three days, four days, five days, right? But we changed ourself on how we do things with recognition of, you know what? I need ink. Let me think through this. I'm going to buy some ink from my ink jets, or I know I'm going to need, I don't know what it is, right? This particular thing, a vitamin. Let me buy it now. I'll be here in a few days, and I'm stacked. I got my inventory is back to where I need it to be. We've changed how we do things to adapt to how they do things. And Amazon is premier in this area.
31:03Vitaliy Katsenelson:No, absolutely. But I think the point I'm trying to make is that Amazon is just one example. And I think this is going to become a standard practice across most companies. Yeah. And the ones that aren't will not be around.
31:20Andrew Horowitz:Let's talk about AI for a second because you touched on that. And let's talk about, like, there are plenty of careers, businesses, jobs that are not going to be in existence. I'll give you an example of something. I was recently, we talked offline about a recent trip. I was in Italy. I was in a place called Orvieto. And I was standing in front of this beautiful church. And I was looking from the outside of this beautiful church. And it was this big dome. It was like a Duomo in Orvieto. and I'm looking at the front of it and there was 12 different statues in the front and this fresco and it was this beautiful edifice, right?
31:56Andrew Horowitz:God, I wish I said to him, I said out loud, I wish there was somebody who could explain this to me. I popped on my Microsoft co-pilot and I said, I'm standing directly in front of the Duomo in Orvieto. I'm looking at these 12 statues. Are those a representation of the 12 apostles? and tell me about the fresco and the design. Okay, Andrew, and started rattling off this unbelievable conversation with me about each of the different parts of the front edifice, if you will, of the church. And then I said, all right, well, now I'm about to walk in. Tell me about what's important inside this church, which I should be looking at.
32:36Andrew Horowitz:And there was a certain particular immaculate something that there was a statue that started bleeding back in whatever day that was considered this holy thing. And, you know, it's over on the left side. You know, you talk about the fact that a personal travel guide is no longer going to be needed.
32:53Vitaliy Katsenelson:Incredible.
32:55Andrew Horowitz:And the people I was with, by the way, had no experience with AI and they were just totally flabbergasted.
33:01Vitaliy Katsenelson:Yeah, it's almost they felt like they just visited the future. Right, exactly, exactly. Which they have.
33:07Andrew Horowitz:So AI, there's a promise, there's a hope, but there's also a reality check too, isn't there? I mean, there's a lot of components.
33:15Vitaliy Katsenelson:So the way I look at this, I kind of drew a parallel between AI and.com bubble, but let me just, the internet, but there is the nuances. This is like, these parallels are never perfect, but there are certain things that are kind of similar. And so a couple of things. Number one, the internet was supposed to change the world. And it has. It has had, right? It has an incredible impact on us. But in the short term, I would argue the impact was less than expected. And in the long term, impact was much greater than we expected ever. So it just takes time for those things to play out. And we get over-optimistic in the short term and probably don't underestimate and underestimate the impact on the long run.
34:08Vitaliy Katsenelson:That's number one. Number two, another thing is that the inflection point with internet came in 2007, 2008, or maybe nine, I forget, eight, yeah, with the introduction of iPhone. Mobile phones have changed the trajectory, kind of the slope of internet adoption and its pervasiveness. so that's so that's one analogy and we'll kind of merge them together in a second another analogy is that the during the dot-com bubble there were a lot of companies that kind of were kind of vaporware and that's not what we're seeing today but there were a group of companies that were actually made internet possible and they were the fiber optics companies right the backbone Yes, it's the Quest Communication, it's Level 3, Global Crossings, and a few others.
35:07And at the time, I remember how Level 3 was saying that they just cannot build enough capacity for internet because the demand is going to be so huge.
35:19Vitaliy Katsenelson:Now, as the demand ended up being huge, but with a couple of things that happened at the same time, that number one, they were not the only one building that fiber. There were other companies doing it as well. And number one, number two, what also changed, technology has changed. The compression made, even though we use, I don't know, exponentially more data today than we did 20 years ago, the technology changed and now data is a lot more compressed. So how that brings us to AI is this way. Number one, you have five or six or probably maybe dozens of companies spending an insane amount of money on building out this infrastructure.
36:06Andrew Horowitz:And by the way, the word insane doesn't actually represent the insanity of the amount of money we're talking about.
36:13Vitaliy Katsenelson:Let's pin this for a second because I have an example. I want to talk about this. Let's come back to insane separately. I want to have a case study. I have a case study for you. Yeah. Okay. But we're sitting in, and Mark Zuckerberg talks about how for Facebook or Meta, it's existential. And that basically it doesn't matter if they overspend a hundred billion dollars or 200 billion dollars, because if they don't, if they don't succeed, they're toast. The problem is when everybody behaves that way, suddenly you're going to have overcapacity. Overcapacity means you're just going to have too much spending.
36:56Vitaliy Katsenelson:And therefore, who will benefit from this are you and me, consumers. And a lot of capital will be misallocated. Now, I want to do something interesting. I want to combine two analogies together, additional analogies. Okay? I want to talk about Oracle and the OpenAI deal. And I want to talk about Andrew Sorkin's 1929 book. Yeah. And I'm going to combine it in an interesting way, I think. So let's talk about Larry Ellison. Larry Ellison now is, I think, either he's the richest person in the world or one of the richest. Okay. And so Oracle today is worth$800 billion. And the value of the company went up by a few hundred billion dollars where Oracle announced this deal with OpenAI, where by 2030, roughly, they committed to spend$300 billion.
37:58Vitaliy Katsenelson:This is the insanity that you're referring to.
38:01Andrew Horowitz:Oh, yeah.
38:01Vitaliy Katsenelson:And OpenAI is going to pay them somewhere between$30 and$60 billion a year or something like this. Okay? And so I was thinking, wow, this is interesting, but how could Oracle do this? So I looked at their financials. So, Andrew, okay, Oracle last year generated, and I'm going to be generous when I say this, about$15 billion, one five, of free cash flows. Oracle has more debt than they have cash. In other words, they have literally, I think, let's just make the numbers round, $100 billion of debt and maybe$10 or$20 billion of cash. So they're leveraged. They're leveraged. So they have$15 billion of cash flows and they have$80 billion of debt, not debt, after you take out all the cash.
38:52Vitaliy Katsenelson:So they're basically going to have to borrow$300 billion because their cash flows are not good enough. Like there's not enough money to -
39:02Andrew Horowitz:You're talking about open AI. Yeah, to do this, yes. Right.
39:06Vitaliy Katsenelson:But then you should tell me, Vitaly, Larry Ellison is brilliant. He built an insane company. That's an incredible company. He must know what he's doing. And, you know, listen, part of me wants to believe that's true. And then I'm going to tell you a story from, I'm early into Andrew O'Sorkin's book, but there is a character there that you may be familiar with. His name is William C. Durant. He was the guy who started General Motors. He basically, I think if I'm right, he built Buick, merged with other companies and built General Motors. Then he was kicked out from General Motors. Then he co-founded Chevrolet and then merged again with General Motors and took over General Motors again.
40:07Vitaliy Katsenelson:So you would argue this guy is like Larry Ellison, like in a sense, brilliant guy, started a company that's still around today. I mean, after a few bankruptcies, but that's not his fault. But so he built General Motors. But what was interesting, and this is what blew me away. he lost his shirt in 1929 bubble through complete speculation. He thought this time was different and he blew all his wealth. And I actually looked it up because I'm not that far into the book, but he died in 1947, complete destitute, managing bowling alley. Oh. It's somewhere in the Midwest. Wow. So I'm not saying Larry Ellison is destined to manage a bowling alley.
41:00Vitaliy Katsenelson:But what I'm saying is that just because people are brilliant does not mean that every decision they make is going to turn out well. In fact, I would argue that a lot of times the more successful people are, the more arrogant they become. They feel like they can walk on the water and the more likely they are to blow up. Yep. And so Larry Ellison, like, so I'm looking, the reason I'm kind of focusing on Larry Ellison because there's a lot of Larry Ellisons out there right now.
41:40Andrew Horowitz:But, you know, here's the deal. I mean, we own the stock and I was very pleased with the movement of the stock after the fact, right? Okay. But the problem is, I said at the time, when it went up, which is what? That was in, when was that? A month ago or so, yeah. It was September. So it went up to$323. $323. Currently trading, because that's about a month ago. So it's currently trading at, give or take,$256, right? So it's like$75. That's a good hunk on the downside from where it was. It's not all the way down to where it was. It started out that day before it got pushed to 248. It's at 256. It's only$15 higher right now.
42:24Andrew Horowitz:That brought in what I thought was one of those jump the shark moments, if you're familiar with that phrase and Fonzie jumping the sharks in happy days. It was like, wait a second. Like you said, you're committing to do a few hundred billion dollars in money you don't even have and hoping this is going to all work out. Somehow you're going to come up with this cash. And OpenAI and Oracle, that's not the only deal that OpenAI put forth. There was a ton of other ones. There's like a trillion dollars they committed of money they don't have. By the way, they pushed the valuation and the market cap of companies dramatically higher.
43:04Vitaliy Katsenelson:Well, I think that's the, if you look at all the deals, there was a lot of kind of incest and secularity in deal-making that has happened over the last couple of months. Right. But what's interesting about this, in the middle of all that, the domino that's going to topple everything is OpenAI, right? Because it's basically OpenAI has to succeed for all these deals to work out. Correct. And their success has to be so astronomical.
43:36Andrew Horowitz:Yep. and
43:39Vitaliy Katsenelson:now this is where Oracle has changed the game until Oracle most of these deals were done by just Facebook drawing its cash flows Google is drawing spending the money they had Oracle deal basically put us into this new phase of spending where it's debt financed now if everybody looks at it as an arm race and the prize is too big it's very big there is absolutely no reason why Facebook and everybody else are not going to start buying hundreds of billions of dollars so this party can I don't know when this party is going to end what I have learned through my experience is that like I'm willing to look like a moron for a while but but my goal when it comes to money management, my goal is not to blow up.
44:39Of course.
44:41Vitaliy Katsenelson:So I feel like I don't have to play this game. There's so many other companies I can look at and analyze. And this was kind of the point of my article about this, is that I don't have to play this, even though everybody talks about it. And it's entertaining. It's entertaining. But it doesn't mean I need to own any of those companies. and I think it's going to end in tears like it has in the past. By the way, we had bubbles like this in the past and like in the 1800s, there was a huge railroad bubble in Europe
45:16Vitaliy Katsenelson:and the railroads were going to change the world and they have changed the world, right? Except investors lost most of their money who invest in railroads. So this is kind of my thoughts. This is my thoughts about investing in today's environment, I guess.
45:33Andrew Horowitz:Well, I mean, I think there's a reality check that has to happen. And the reality check that has to happen is the acknowledgement that not every company is going to keep on growing at these levels. And I think that happened last week with Facebook meta where they said, hey, we're going to be spending this much. And other companies, I mean, Amazon had a great earnings number last week. Bottom line, by the way, a little surprise number. a surprise announcement. You mentioned Andrew Ross Sorkin. We have him scheduled sometime in December. We have two dates actually. And he hasn't been on the show in a number of years, but I thought it was a good time to get him on.
46:14Andrew Horowitz:And I guess my copy of my book's in the mail somewhere. Can I tell you, this book is so good.
46:21Vitaliy Katsenelson:And I rarely endorse books like this, but that book is so good because I think what it, what it, he gives you such a great insight into that time period and into human behavior. And you realize, I mean, there are things, like one thing you, after you read through this book, one thing you realize that how crooked the market, stock market was then and how you can't even, like sometimes you can't even draw parallels because like most, by today, if this, if most of the participants in the stock market then did those things today, they would have been in jail already for certain 10 lifetimes. So just the regulations were different, and it was Wild West.
47:10Vitaliy Katsenelson:But at the same time, what hasn't changed is just human behavior. The fear and greed, it's just— It's never going to change. It's never going to change.
47:19Andrew Horowitz:It's never going to change. Let's talk about valuations and try to make some sense out of things. You mentioned, you know, you're willing to be wrong for a while, but in the end, be right. That's the hope, right? You know, the long term, you're willing to take short term pain for long term gain or better said, you don't need to follow the crowd necessarily just to follow the crowd. You're going to use what you know is, I'm putting words in your mouth, but good solid analysis to get to the point of being much more comfortable than having to worry about having a company. Like, for example, we owned a company for clients, two of the SMR, the smaller modular reactor companies, right?
47:54Andrew Horowitz:They had no product, no nothing, but we saw that there was going to be a big boom in that opportunity in theory, right? Hundreds and hundreds of percent we made on the stocks this year. Sold them out not too, like, last week. But the point is, I was uncomfortable the whole time owning them. Because even though they were running up like crazy, I'm like, there's going to be, unless they come up with a product and actually a sale and actually they implemented a regulatory approval. I'm sitting out here like just hoping and praying.
48:24Vitaliy Katsenelson:Yeah, I think the, and you probably, you know, and I know you, you don't have a portfolio of them.
48:29Andrew Horowitz:Right. No, no, no. There's only a few.
48:31Vitaliy Katsenelson:That's exactly right. So I think the, I think the, if I look at this valuation, I mean, the market is quite, quite expensive. I mean, the best way to describe it is this way. A couple of things. Number one, 60 % of my portfolio today is outside of the United States. And by the way, I'm not getting much joy from that because you know how difficult it is to buy foreign stocks and how much more difficult it is operationally. So we're going through these pains because we can't find enough high-quality companies that are undervalued in the United States. Right. That's point number one. Point number two, our new accounts today are probably maybe 50 % invested.
49:19Vitaliy Katsenelson:Even with foreign investments, we cannot find enough companies that are, you know, kind of, where I can say it's a high-quality business that's undervalued. And the market is probably one of the highest valuations over the last 100 years. You know, I used to know the statistics and I used to be able to tell you how expensive it is. I gave up.
49:42Andrew Horowitz:Well, you look at the CAPE ratio, it's higher than it was back in 2020.
49:46Vitaliy Katsenelson:Exactly. And I wrote two books on this subject and you and I discussed it so many times. The bottom line is this. Your future returns are a function of how much you pay for stocks.
50:00Andrew Horowitz:Right. That's great.
50:01Vitaliy Katsenelson:You can have a great company, but if you overpay for it, your future return is going to be mediocre. It's just that simple. And today, if you look at the stock market, like the overall, it's very expensive. So if you own an average stock, the returns are gonna be mediocre going forward. Also, and this is kind of interesting. What we all said, like there was a tale of two economies. There was a tale of AI economy and the kind of large company economy and everything else. And I think this is kind of under the surface, that's what's going on. Because most of the growth in economy today has happened because of AI.
50:45Vitaliy Katsenelson:It's kind of like our Y2K version of kind of -
50:49Andrew Horowitz:Well, it's good. I mean, NVIDIA is an 8 % or 9 % position in the S &P 500. Exactly. $5 trillion company. It sneezes and the whole market goes crazy, either direction. Exactly.
50:59Vitaliy Katsenelson:Exactly.
51:00Andrew Horowitz:And by the way, that I find to be a fallacy in the construction of indices, that allows for these companies to get so large because you can't help it. You can't stop it. Because if you have market cap, it's just what it does. And the larger market cap begets larger buying, begets larger market cap, begets more. And it's a cycle that you cannot break because, and by the way, this happens on the up and the downside, right? So things roll over. Why? And this is a reason that many of the players out there are so desperate to keep things up because this thing rolls over, it rolls over the whole indice.
51:38Vitaliy Katsenelson:You know what's kind of interesting? These kind of parallels to 1929, the first 20 % of the book, like most of the conversation is talking about how to keep the stock prices high. Yeah. This is the narrative of the first 20 % of the book. Right. It's just like everybody's trying to figure out. To me, it's like how to try to, fight the gravity. Like you can fight it for so long, at some point it's still going to happen.
52:09Andrew Horowitz:Right.
52:09Vitaliy Katsenelson:So if you own overvalued assets, unless you get off, you know, you're going to lose money or you're going to have miserable returns.
52:19Andrew Horowitz:But the difference between then and now is a big difference. I think a gigantic difference is now you have players that have timeframes that are infinity. You have players like sovereign wealth funds that are actively buying, like Norway. Look at them. Look at the sovereign wealth fund of the US, which by the way, is not really in existence. But what do we do instead? We just take positions somehow magically in companies at low prices. Or you have NVIDIA who puts a billion dollars into Nokia, right? Who puts a billion dollars into this one. Or you have all of a sudden, the United States of America buying two supercomputers built by AMD for 500 million each.
53:04Andrew Horowitz:So how does that work? 500 million for a computer. Now, it's not your off-the-shelf laptop.
53:11Vitaliy Katsenelson:Actually, I'll be honest. That is like so like two years ago. Because half a billion dollars now is nothing. For a computer? For one computer? Yeah, quick. Hey, listen, 300 billion dollars. I guess. I guess. Yeah. No, but you're right. Can you imagine like half a billion dollars? Yeah, just incredible.
53:33Andrew Horowitz:It's got to be a great, I want that lightened up. I want to have great speakers on that laptop for that kind of money. No, but seriously, we have a whole different level of money that's being pushed in. You know, we used to laugh and we used to scoff at Japan that was actively buying. Oh my God, the Bank of Japan was actively buying inside their market. And we would look at China and we'd say, oh, you know, the SOEs, the state-owned enterprises, What an awful situation. How unfair that they have the Chinese government propping up, helping, creating a much better scenario for them from a competitive standpoint.
54:09Andrew Horowitz:And now we are doing the same thing. The money that is flowing in from all of this is like nonstop and unstoppable. Not to mention the 401k plans are all the normal mechanics of the market. But I think there's something to be said about the fact that there's a lot of pensions, people living longer. They have to change their structure. They used to have just bonds, and they've changed that dramatically. There's major funds at colleges, endowments. There's a lot of money out there that just says, you know what? We have a really long time, 10, 15, 20-year time horizon, and their time horizon, they don't flinch.
54:50Vitaliy Katsenelson:Can I give you a counter argument to this? Yeah, good. I'd love to hear it. I forget who said it, but I think that was an interesting insight. So most of those funds today don't own equities. They own private equity. And when I say most, let's say like 80-20, roughly. I don't know. Like maybe 80 % private equity, 20 % equity. Something like this. But what's interesting, if you're going to have enrollments start declining, then they're going to have to start digging into private, start selling their time horizons may end up being not as long as people thought they were. Mm-hmm. Okay. And so there would be pressure on private equity firms because private equities, the magic of private equity is that they're not marked to market 5 ,000 times a day.
55:51Vitaliy Katsenelson:And when they start marketing to market, they may realize that these businesses are worth less than those endowments thought they were. That's number one. Number two, what was interesting about the 1929 crash, what really made things a lot worse, and actually I would argue what really has created the collapse itself, is debt, is leverage. Yep. And I was watching an interview with Porter Jones, who basically said that, well, if you look at today's margin debt and you combine it with leveraged ETFs. So this is important. So not just to make it apples to apples. They're not that much different from 100 years ago.
56:45Vitaliy Katsenelson:So there is a lot of leverage in the system.
56:47Andrew Horowitz:We hit a peak leverage. We hit the margin debt at brokerage firms, hit an all-time high just two weeks ago. Okay.
56:57Vitaliy Katsenelson:Okay. Well, and that number probably understates the true leverage, right?
57:02Andrew Horowitz:Because of the leverage ETFs. The extra, well, how about all the extra options that are out there, which can expire over time, so that's fine. And those are expected. But yeah, the leveraged ETFs and other leveraged things. You know, you talk about private equity, by the way, and that has a indefinite, theoretical indefinite time horizon, right? But I got to tell you something. It's all fine as long as the marks look good. Exactly. And they could keep the marks looking good because nobody really cares because nobody knows what's going on underneath everything. But all of a sudden you get those marks looking bad.
57:31Andrew Horowitz:And by the way, you know, I don't know if you if you ever deal with like interval funds where you're locked in for a period of time. So it's a it's a it's kind of like a mutual fund that has some of the characteristics of the private equity hedge funds where they have a gateway where you can get in or out over only on a monthly quarterly basis, let's say. And we have a few of those clients that we inherited. And we've been trying for a while to get out. And these are the good times right now, right? These are generally where things are liquid. There's no problems. And what's interesting is that with regard to the request that we put in a couple weeks ago, we only got like an 18 % allocation for sale.
58:17Andrew Horowitz:And that's in the good times. In other words, we said we want to sell 100%. They said, no, you can only sell 18. So it's going to take us another year to get out of this deal. So my point, though, is what's really fascinating about all this is that, you know, you have a situation where we have good times. People know this long term, but yet you can't get out. Now, once all of a sudden people need, have to get out, things change when liquidity is not there.
58:48Vitaliy Katsenelson:I think, Andrew, this is kind of my, I think this is my message to your listeners. The time to get paranoid is right now. It's not when you have this euphoria and nobody cares about risk. This is when the quality of your decision matters so much. And I, but I'm not saying to get out of the market. I'm not saying none of this stuff. What I'm saying is you basically ask yourself a question. I want a portfolio of stocks. And if the market, like this is Warren Buffett's actually kind of approach to this. And this is his definition of quality. If the market was closed for 10 years and I could not sell them, would I still want to own what I own today?
59:41Vitaliy Katsenelson:And I think this is really kind of, this is how, like when I look at portfolio construction, and that's what I think about.
59:48Andrew Horowitz:Yeah, smart. That's the ultimate. Yeah. That's the ultimate feat, you know, to the fire.
59:54Vitaliy Katsenelson:That's right.
59:55Andrew Horowitz:Yeah. So, I mean, we're going to go through a lot of different cycles. You know, it was funny. Just recently, I was thinking, I was driving down the road. I'm thinking, what other things can happen from a financial engineering standpoint? Like, we see the vendor financing. We see the circular financing, the things with open AI, the money that goes in from governments, the NVIDIA that's buying this company or infusing money there. I'm thinking to myself just the other day. I'm thinking, you know, we haven't seen stock splits recently. I wonder, you know, if one company is going to come out with a stock split.
1:00:25Andrew Horowitz:And then all of a sudden, you know, remember where that was a big thing, where stock splits happened and companies, stocks went crazy. And we just saw the news that Netflix is doing a 10 for one.
1:00:33Vitaliy Katsenelson:Oh, really?
1:00:34Andrew Horowitz:You know, and I find it fascinating that we go through these cycles of, whether it's financial engineering or it's, You want to call it shareholder beneficial transactions. But it's kind of interesting how this whole thing flows. The point is, though, what you do is, what I like about what you do is you separate the noise from the facts. You know, you put aside some of these things and really come up with what is a company, like you said, that you would own for 10 years without having to even look at it, theoretically.
1:01:07Vitaliy Katsenelson:Yeah. Well, I think the beauty of what, and you do it kind of similar, I guess. is that I own individual businesses. Like, you know, they happen to be publicly traded. And therefore, when you analyze these companies, like I have a time horizon, like, you know, of decades, you know, five or 10 years at least. And therefore, you start looking at everything going on in the market through the lens of five or 10 years. And a lot of things just kind of, you know, fall, you know, kind of fall through and say, I'm not interested in that.
1:01:42Andrew Horowitz:I think it's smart. I think it's great. Vitaly Katsunelson, always appreciate you spending time with us.
1:01:49Vitaliy Katsenelson:Thank you so much. Again, you're so good at this. Oh, you always say that. Thank you. You're so nice. I always enjoy it. Thank you so much.
1:01:56Andrew Horowitz:You're so nice. You're nice. Make sure to go over to the website, thedisciplinedinvestor.com. We have links on how to get his books and his writings and information about IMA. and all the things are right there over on episode number 945 of thedisciplinedinvestor.com. Thanks, Vitaly. Talk to you.
1:02:13Vitaliy Katsenelson:Andrew, thank you so much. Thank you. Bye.
1:02:16Andrew Horowitz:Another great episode, another great guest. I want to thank everybody for joining me this time, every time on the Disciplined Investor podcast. Don't forget to listen to DH Unplugged, which is happening each and every week. We record myself and John C. Dvorak on Tuesdays. We talk about all the great stuff that's happening in the news. We'll be dissecting what's going on with the Amazon numbers, the Netflix 10 for 1 stock split, and all the other things that are going on with regard to not only companies, but the economics, the politics, the markets. All that we talk about every Tuesday. Thanks for joining me this week and every week, and I'll see you around real soon.
1:03:00Andrew Horowitz:This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz and Company Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements.
1:03:38Andrew Horowitz:Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement. Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliates.
1:04:20We'll be right back.
From the publisher
Swiss cheese agreements.
Overspending by big tech – could that be their downfall?
A rate cut in the dark and AI’s Impact on Future Workforce.
Guest: Vitaliy Katsenelson is discussing the basic math of the markets, including where to actually find bargains.
NEW! DOWNLOAD THIS EPISODE’S AI GENERATED SHOW NOTES (Guest Segment)
Vitaliy Katsenelson, born and raised in Murmansk, Russia (the home for Russia‘s northern navy fleet, think Tom Clancy‘s Red October). Immigrated to the US from Russia in 1991 with all his family three brothers, father, and stepmother.
His professional career is easily described in one sentence: He invest, He educates, he writes, and he could not dream of doing anything else.
He is Chief Investment Officer at Investment Management Associates, Inc (IMA), a value investment firm based in Denver, Colorado. After he received his graduate and undergraduate degrees in finance (cum laude) from the University of Colorado at Denver, and finished his CFA designation, he wanted to keep learning. He figured the best way to learn is to teach. At first he taught an undergraduate class at the University of Colorado at Denver and later a graduate investment class at the same university that he designed based on his day job.
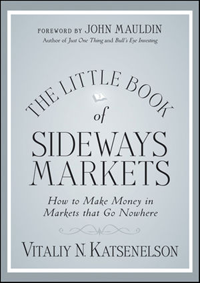
He found that the university classroom was not big enough, so he started writing. He writes a monthly column for Institutional Investor Magazine and he has written articles for the Financial Times, Barron‘s, BusinessWeek, Christian Science Monitor, New York Post, and the list goes on.
He was profiled in Barron‘s, and has been interviewed by Value Investor Insight, Welling@Weeden, BusinessWeek, BNN, CNBC, and countless radio shows.
Vitaliy has authored the Little Book of Sideways Markets (Wiley, 2010) and Active Value Investing (Wiley, 2007).
Check this out and find out more at: http://www.interactivebrokers.com/
More information available on Horowitz & Company’s TDI Managed Growth Strategy
Stocks discussed this week (ORCL), AMZN), (MSFT), (DIS), (AMD), (NVDA), (NOK)