
In short
Episode 929 of The Disciplined Investor focuses on U.S. macro/news catalysts (OBAA/tariffs, earnings season, rate-cut probabilities, pricing volatility) and then shifts to options strategy—especially how to interpret low VIX complacency and use VIX options, put-call ratios, and earnings straddles.
Key claims
(1) OBAA includes “no tax” items that are actually deductions/limited benefits, with some provisions retroactive to the 2025 tax year and expiring/renewed around 2028. (2) Bottoms-up S&P 500 EPS estimates fell about 4.2% for Q2, suggesting earnings season may disappoint even as markets hit highs. (3) Rate-cut odds shifted sharply lower (e.g., July 25 bps cut probability down to ~4.7%). (4) VIX is seasonally low in July; the “sell” signal is when VIX starts rising from low levels, not when it’s low.
Notable examples
Apple put-call ratio extremes preceding a rally; VIX speculation using short-dated, ~33% OTM calls; earnings straddle selection using Optionslam.com and buying straddles when recent post-earnings moves were larger than the current implied move.
Guests
Larry McMillan, options strategist and author of Options as a Strategic Investment (300k+ copies), active trader, and editor/contributor to Daily Volume Alerts/The Option Strategist.
Written by AI. May contain mistakes. Listen to the episode to check what was said.
Chapters
Tap a time to open that second in VOOverview of Current Financial Climate
1:23 to 2:28
Discussion about recent market events, the OBAA legislation, and its implications.
“From seed through harvest, cultivating financial success.”
Impact of OBAA and Tax Changes
2:28 to 7:37
Analysis of the new tax changes from OBAA and their potential effects on consumers.
“each and every week for the last, I think it's 17 years or so, which we love doing.”
Earnings Season Insights
7:37 to 11:11
Insights into the upcoming earnings season and analysts' EPS estimates.
“That's the kind of thing that we're dealing with here.”
Rate Cut Probabilities Discussion
11:11 to 13:38
Discussion on the changing probabilities of interest rate cuts and their implications.
“Let's talk about rate cut probabilities, shall we?”
Market Preparedness
14:00 to 14:31
Learn how disciplined investors remain calm amidst political uncertainty.
“political uncertainty, well, disciplined investors, they don't panic.”
From Grad School to Options Trading
15:30 to 16:41
Discover how Larry's early experiences shaped his interest in options.
“And we have great things happening, which we're going to get into, like the VIX is low and there's some complacency or at least something's going on.”
The First Experience with Derivatives
16:41 to 17:44
Hear about Larry's introduction to derivatives and the CBOE.
“Anyway, so to pass some time, I jumped into a bookstore, grabbed a book called How to Make a Million.”
Transitioning to Wall Street
17:44 to 18:46
Learn about Larry's transition from grad school to a career on Wall Street.
“And the reason I got the book was because I didn't exactly understand what the title meant at all.”
Early Days of Options Trading
18:46 to 20:04
Explore the challenges Larry faced in the early days of options trading.
“Then when the CBOE opened, I was working at Bell Labs.”
Building a Trading Career
20:04 to 21:13
Understand the steps Larry took to build a career in options trading.
“And I didn't have a pricing service either, so I had to type the pricing in by hand.”
Show all 24 chapters
Lessons from Early Trades
21:13 to 22:24
Larry shares insights and lessons learned from his early trades.
“I want to trade, I don't know, I want to trade some currencies.”
The Impact of 'Options as a Strategic Investment'
22:24 to 24:22
Explore the journey behind Larry's influential book on options.
“I mean, I remember, I can remember a bunch of bad trades.”
Turning Points in Larry's Career
24:22 to 25:16
Discover pivotal moments that shaped Larry's trading career.
“You know, it's probably 250 pages or so.”
Programming in the Options World
25:16 to 26:39
Learn about the programming skills Larry utilized in trading.
“I guess when the options first came out, it was trading some, you know, I had some success.”
A Day in the Life of an Options Trader
26:39 to 28:00
Get an insider’s view of what a typical day looks like for an options trader.
“In Wall Street, they didn't have Unix or C, but we still managed to get some programs done in Fortran.”
Understanding Put-Call Ratios
28:00 to 29:16
Learn about the significance of put-call ratios as a contrary indicator in trading, particularly in context with Apple stock.
“You know, again, sort of a theoretical value thing.”
The Importance of Moving Averages
29:16 to 30:27
Explore the role of moving averages in trading strategies and how they reflect market sentiment.
“I like to use strategies or if you're using technical analysis, things that make sense, just like you said, that other people are seeing the same thing and acting on it.”
Options on Futures Trading
30:27 to 31:44
Discuss the complexities and strategies associated with trading options on futures, including market timing.
“And, you know, some of the old patterns they would talk about, like flags and all that, it doesn't make any sense to me, really, because nobody else is really watching for that.”
Market Behavior and VIX Insights
31:44 to 34:22
Analyze the VIX behavior during seasonal trends and its implications for trading strategies.
“And the fact is that markets generally move from bottom left to top right over time, generally speaking.”
Risk Assessment with VIX and Market Trends
34:22 to 38:27
Evaluate the current market conditions as indicated by VIX levels and how to interpret them for trading.
“I'll do, let me put a little trade in that.”
Interpreting the Put-Call Ratio
38:27 to 42:00
Gain insights into how to calculate and interpret the put-call ratio for better trading decisions.
“Well, the one thing I kind of watch is the 200-day moving average.”
Understanding Put-Call Ratios
42:00 to 45:50
Learn how to interpret put-call ratios and their implications for market sentiment.
“not only volume, but what's my real commitment?”
Earnings and Options Strategy
45:50 to 49:49
Discover strategies for trading options around earnings announcements.
“So there's some common sense involved, too.”
Analyzing Option-Based ETFs
49:49 to 51:43
Explore the performance and strategies of option-based ETFs and their benefits.
“So it's typically the same letters as the underlying with the Y on the end.”
Transcript
Automatic transcript. May contain errors.0:00This episode is brought to you by Interactive Brokers. And here's a question for you. Will the U.S. retail sales growth rate be greater than 1.5 % in June of 2025? The yes forecast contract recently traded 11 % and the no was at 87%. With Interactive Brokers forecast contracts, you can trade on future events like climate change, the economy, or politics. You choose yes or no. And if you're right, you get paid. It's that simple. Explore trending data on all sorts of areas Spot the trends and make your prediction for June 2025 Trade forecast contracts, interact with brokers And earn a dollar for every correct prediction Plus, you'll earn 3.83 % APY on your investment With an interest-like incentive coupon And you get$3 when you start trading forecast contracts Now, forecast contracts are not suitable for all investors Go to ibkr.com slash forecast and start predicting today.
1:02The last trading for this contract is July 17th. The Disciplined Investor is all about you, your money, and the markets. Sit back and get ready for this edition of The Disciplined Investor Podcast.
1:18Larry McMillan:This episode of The Disciplined Investor is sponsored by Horowitz & Company. If you're looking for a portfolio manager, look no further. Horowitz and Company. From seed through harvest, cultivating financial success.
1:37Aha, the OBAR is signed into law. Letters are going out with new deadlines for tariffs, and we're coming up on earnings season. JP Morgan, in fact, reporting on the 15th next week. And our guest, Larry McMillan, the option strategist. All this and much more on episode number 929 of the Disciplined Investor Podcast.
2:15And a great hello to you. Welcome to another episode of the Disciplined Investor Podcast. I'm Andrew Horowitz. I'm your host, the founder of Horowitz and Company, an investment advisory firm right here downtown Fort Lauderdale, where actually our studios are also located, where we produce this show and DH Unplugged each and every week for the last, I think it's 17 years or so, which we love doing. So what's been going on? A flurry, I think it's a flurry, of stuff. This whole, the crazy chaotic manner that we're getting used to, aren't we though? Seems that the VIX has been rather complacent. We'll talk about that a bit.
2:58We saw that the OBAA, the One Big Beautiful Bill Act, we have to have an acronym. There's actually, I think, a chief of acronyms for the U.S. government. Somebody that says, you know what, no matter what bill, whatever legislation we have, whatever happens, the legislation has to have an acronym. And that's the acronym for this OBAA. You're going to hear it time and time again. Now, it was signed into law last week, and now we have to, well, I figure it out. the idea that there is no tax on tips, not exactly true. No tax on Social Security, definitely not true. No tax on overtime, not true either.
3:31Yes, we have some things like all babies that are born seem to have a new account with$1 ,000 that's going to put into them. We have to figure out how that goes. Only till 2028. A lot of these things that have been put into this legislation are only until 2028. Then they have to be voted on, et cetera. Obviously, why 2028? You know why. It's all political. It's all for the face value of, hey, look what we got during our tenure. And if you want to go back and vote against this by not renewing it, well, you're doing a big disservice. And who knows what party is going to be in power in the next term.
4:16So that's a big issue right now. So we looked at a lot of different measures that could be impactful. Some are, some aren't. Like the deduction you get for the tips, it's not, again, it's not no tax. It's a deduction. $25 ,000 maximum, depending on where your income is, between$150 ,000 and$300 ,000, depending on if you're single or married, there's a deduction there. Only part is excluded. There's a maximum household threshold. but the good news is that if you are a service worker and or get tips somehow some way the potential is depending on your income level let's say you're about earning 50 60 70 000 you could be getting about a 28 to 3 000 tax savings over the next number of years pretty good and the better part of that really cool is that it's retroactive to 2025 tax year so this tax year Even though it was voted in now, you don't have to wait till 2026.
5:13In other words, when you file your 2025 in 2026, you're going to get the tax break. So you don't have to wait a whole year. Very cool. Overtime workers will see some benefit as well. Not as much. And a friend asked me, oh man, wait, you know what, second. I put this on Twitter, by the way. My handle is Andrew Horowitz, one word. If you want to follow me, at Andrew Horowitz on Twitter. He asked me, he said, you know, well, do we tip less now? Kind of an interesting question because, you know, there's machines that come to you that we get after our meal that automatically puts 22 % on no matter what you buy.
5:50Or in fact, if you do a takeaway or, you know, a delivery, you should be giving all this money too, even though they get a fee for it. Okay, whatever your choice is, whatever you want to do, whatever your level of generosity is, maybe the new tip should be, I don't know, 13 % is the new 18 % because it's not taxable. Now, what would that would do? And he said to me, well, you know, think about it for a second. If we tip less, and again, that's only a small amount of money, but if we tip less, there's more money in our pocket, we can go and spend it in the economy. If we give it to the food service worker, I'm like, uh-huh.
6:26Well, then they get to spend it, because they have less taxes due, sometime in the future on whatever they're spending it on. How about I make the choice of where I want to put my money to work? I'm like, okay, if that's what you're going to do, if that's how it works, I don't know. The interesting thing about that line of questioning and that line of thinking is that that is what is going to have to be anticipated through economists. That's their job. They got to figure out all these different variables inside of these kind of laws. And the fact is it probably wasn't done ahead of time. We don't know exactly the impact of how this is going to play out.
7:04Is it going to be on higher end items, paying down credit card, putting into savings? Who is going to actually be spending the money or not that is saved from this? Something that's really interesting to think about. I think the question was kind of silly and I told him, but nonetheless, the exercise in that line of questioning is pretty fascinating because we really do not know when you push a little bit over here, what bulges over there. You know the butterfly effect, right? Where a butterfly can flap its wings in Asia and it creates a storm in South Africa. That's the kind of thing that we're dealing with here.
7:47We do not know the impact of how this is going to actually play out long term. Something that we're going to have to watch. Now, earnings season is right around the corner. I think JP Morgan is going to be reporting on the 20th. No, no, on the 15th. The 15th, that's next week. Yeah, JP Morgan is going to be reporting next week. And that's what the official kickoff is to earnings season these days. It used to be Alcoa when that was important, but they're not. Now, according to Facts, I did some digging in to see what was going on. During the second quarter, the outlook that we're going to find coming out right now, analysts reduce earnings per share estimates by a wider margin than usual.
8:28Now, this is a bottoms-up EPS estimate for quarter two, which means that we look at each of the various companies in the S &P 500. We look at their earnings per share, and then we add it up, and then divide it by the appropriate level of the way that the construction of the S &P 500 is, and you come out with a number, right? This aggregation of EPS forecasts for all companies, the median fell by 4.2%, dropping from 65.55 in March to 6 ,283. That was the last number. So we got a 4 % drop. Now, markets don't seem to care. Hitting on all-time highs, even a little tariff didn't bother anybody when the letters went out.
9:13You know, the bottom line here is that when you look at what went on with the recent rally that we saw, it really doesn't have to do with anything more than, at this point, hope for the future. because if you look at where we are with regard to the earnings estimates, well, they're down. Now, it's common, by the way, for analysts to lower EPS estimates during a quarter. And that seems to happen a lot because they want companies to reach that bar, it seems. But this particular quarter's decline stands out. When you look at the past 20 quarters, which is five years, the average quarterly decline in bottoms-up EPS estimates has been only 3 % Over the past years, 3.1%.
9:57Over the past 15 years, 3.2%. Now, when you look at the past 20 years, 80 quarters worth of data, estimates, et cetera, the average was actually 4.2%. So basically, the second quarter reduction in EPS estimates, it exceeded the 5, 10, and 15-year averages. I'm not sure what exactly that means per se. Does that mean that, well, on one hand, What we're looking at is that we're getting more of a reality check here, or are we saying, well, you know, it's more in line with the long-term average. I guess you can look at it a lot of different ways. But right now, we did see a larger-than-usual rate, earnings analysis estimate cut without a commensurate stock market drop into it, which means, by the way, this is important, that earnings season may be setting up to be a disappointment.
10:53That's the point you want to really look at. If the earnings estimates were reduced and companies don't meet those higher levels by a substantial measure because their stocks are already at a peak level, that could be problematic for many companies. I want to talk about one other thing. Let's talk about rate cut probabilities, shall we? You know, after that recent unemployment report that we saw last week, where it dropped to 4.1%. And we saw, generally speaking, a better overall employment report, right? The probability of a 25 basis point cut in July meeting is 4.7 % versus 21 % a week ago. The probability of a 25 basis point cut or a quarter basis point cut in September meeting still about the same 65 versus 68.
11:49October goes to 41 versus 74%. And December goes from 93 % down to 74%. So a huge change in expectations for rate cuts. And that is in line also with the very, I would say, stubborn. The stubborn Jay Powell and crew who say, you know what, it's really not time to do so. We don't know how the impact of tariffs are going to affect inflation, PCE, and other areas of the economy. There was a report last week during Prime Days, the Amazon Prime Days, that said that on average there was about a 4.5 % increase in most prices during this season compared to last. That's still a drop when you look at the Amazon products That I think mandate a 20 % reduction in overall pricing Compared to their average price or their normal price There still was an increase of about, I think, 4 % But the high-end pricing, this is where it really got interesting There was anywhere from, I think, a 5 % to a 15 % increase in overall pricing Over the last year in the higher-end products So we're starting to see that this little bit of volatility and pricing is starting to creep in, probably due to a year later, some inflation that's been already in the system and the impact of tariffs or the perception of the increase of tariffs.
13:26Or better yet, the fact that companies are saying to hell with it, we're just going to raise prices because, well, we got the cover of tariffs that, who's going to get upset with that? So just think about that. Something interesting. One of the things I also was looking at recently was the VIX. I talked about that a little bit. We're going to talk about that with our guest because he's the option strategist. And the VIX is an option that you could utilize, right? It's VIX futures, but you really could play it probably the purest way through options. We're going to get to that. First, let's talk about interactive brokers for a minute because if you want to navigate political uncertainty, well, disciplined investors, they don't panic.
14:06We prepare. At Interactive Brokers, you can help protect your portfolio and hedge market risks with bonds, precious metals, and foreign exchange, all from one powerful platform. With advanced tools, global access, and low cost, IBKR helps you manage volatility and stay ahead, even in uncertain times. The best informed investors choose Interactive Brokers. To learn more, visit ibkr.com slash navigate. Let me give you a quick intro to our guest before we get to him. Larry McMillan. He's a professional trader, perhaps best known as the author of Options as a Strategic Investment, the best-selling work on stock and index strategies, which has sold over more than 300 ,000 copies.
14:58He's an active trader on his own account. He also manages option-oriented accounts for some individuals. In a research capacity, he edits and contributes to his firm's publication, Daily Volume Alerts, The Option Strategist, and The Daily Strategist, derivative product newsletters covering equity, index, and future options. Finally, he speaks on option strategies in many seminars all over the world, United States, Canada, Europe. He gets to travel. And he's been all over TV. He's been all over TV and radio, podcasts. You've seen his writings. You've seen him somewhere. So I'm interested. I have a lineup of questions.
15:32So, Larry, how are you? I'm doing great, Andrew. Things are, you know, summer. That's good, right? Yeah, exactly. A nice time of year. And we have great things happening, which we're going to get into, like the VIX is low and there's some complacency or at least something's going on. And, you know, we have organized chaos. But I want to back up. I want to ask you. So I don't think I've ever asked you. Um, what was, you know, there's different strokes for different folks. People, you know, some people like the buy and hold methodology of, of investing. Some people like trading. Some people love the futures market, the currency markets, you know, a lot of people, newbies always seem to be really enthralled with the currency market.
16:14But what first drew you into the world of options trading? Well, actually it's kind of funny. I was in grad school at the University of Colorado, and the Denver Broncos used to sell a certain number of tickets to the public. You had to stand in line to get them, so I went down to standing in line. I always joked that line was a mile high and a mile long. Anyway, so to pass some time, I jumped into a bookstore, grabbed a book called How to Make a Million. Well, it turned out it was really, despite the frivolous title, it was actually a serious book about convertible arbitrage, or convertible bonds anyways.
16:59And so that was my first experience with derivatives, and kind of really struck me something I liked. And then the CBOE opened the next year, so I was pretty much on board right from the beginning. And I don't know, I really understood option strategies just sort of inherently. So I just stuck with that. So how were the Broncos that year? They were okay. You know, nothing great. Going way back, I think Frank Chupuka was their quarterback. Going back. Going back. You know, it's interesting you mentioned this. It jogs my memory. I remember one time I was somewhere and I was like, oh, maybe I'll talk about, think about investing as something, right?
17:50I'll do it. And I got a book. And the reason I got the book was because I didn't exactly understand what the title meant at all. But it looked kind of thin. I was like, all right, I'll start with that. It was something called the TED spread. And it was something, I don't know if you know that, it's something about currency spread. I don't remember even what it was. As a matter of fact, when I read it, I probably, but it was very, I thought it was very interesting to a point that I'm like, all right, well, I don't really get this, but it's kind of interesting how you could do this. It was another arbitrage book, right?
18:21How do you do this currency thing and all that? Well, maybe I'll look at that. I think it had to do with the 10-year and the dollar and some other currencies. Well, I regularly remember it myself, but I couldn't tell you what it was. Yeah, exactly. So that was kind of interesting. So that then took you into the world of directly into options trading or what? You started working at the CBOE? No, no, no. I was working at, well, I was in grad school at that time. Then when the CBOE opened, I was working at Bell Labs. I was a programmer. So I started my own newsletter. I used to have some interesting subscribers, one of whom was Ivan Boski.
19:01Really? Yeah. So I just advertised it in Barron's and it got, you know, some subscribers. And then about four years later, I had a position opened up at my brokerage firm, which was Thompson McKinnon, for an option strategist. So then I left Bell Labs and went to Wall Street then. Back then, you had to, I'm guessing here, and I know I'm right, but you had to calculate this stuff by hand, all the different variations of the strategies. Well, yeah. I mean, I was a programmer. I did have access to the Bell Labs computers. So I was doing a lot of Black-Scholes modeling and all that stuff back then, even.
19:42It was, you know, the Black-Scholes model came out right about the same time the CBOE opened. So I was able to, you know, do theoretical values, compute implied volatilities, all that sort of stuff, which was in those days considered really advanced. Yeah. And not only that, you didn't have the, I don't think, you didn't have the liquidity like you have today. to really hone in on the valuation models, right? Right, right, yeah. And I didn't have a pricing service either, so I had to type the pricing in by hand. I love that. I love that. How did you get pricing? Originally, there weren't that many.
20:19But how did you get pricing? And then, just take it out of the Wall Street Journal, there were only, in the beginning, 16 stocks with options, and then it went to 32. Two, you know, then it started to increase after that. But it still wasn't all that many. You could, especially if you were just, you know, if you were ignoring the deep out of the monies, you could type in all the at the money stuff pretty quickly. I'd say less than a half an hour or so. That's kind of interesting. So your name is synonymous with option strategy. But you're telling me that before that, you basically, well, there was no really before that, was there?
21:03You were kind of, you cut your teeth on the career that you're doing now. I mean, have you ever thought of maybe, oh, the hell with these options. I want to trade, I don't know, I want to trade some currencies. Yeah, no, that never really attracted me. I never was a floor trader. I was always an upstairs trader. And there's just, you know, there's a lot of option opportunities in general. So I never really felt like I was missing out on anything. Do you remember your first options trade ever? Worst or first? Well, we'll start with first, which was my question, but maybe we'll work our way into that one.
21:46Yeah, but early on, I remember, I think I was just buying some calls on Kodak or something. But then I started to do some put ratio spreads or call ratios. We wouldn't have puts back then, just calls. I did some call ratio spreads, which I got a little too cute. And I had naked calls, and then the market shot up after the October 74 bottom. So I got burned a little bit on that. That was actually probably one of my worst trades. That's a good lesson though, right? I bet. Yeah. Yeah. Absolutely. Always is. I mean, I remember, I can remember a bunch of bad trades. I mean, I remember a trade on a company.
22:32Well, today it's called MicroStrategy still, but this was back in 2000. I remember this and I was like, oh, that was bad. It was just cut in half overnight. And I realized I was in too heavy and this, and kind of set the stage for some deeper analysis and making sure that you have proper money management disciplines going into this, you know? So you've authored one of the most well-respected books in the field. It's called Options as a Strategic Investment. And did you expect it to become such a staple? I mean, what inspired you to write it first? And did you really, I mean, I don't know. I've written two books.
23:09I never thought it was going to be like, oh, my God, these crazy runaway fictional. Somebody's going to write a movie based on my book, right? Well, as I said, I went to Wall Street to be the option of strategist for Thompson McKinnon. And part of that job was writing a weekly letter. So I was just explaining strategies for the brokers, you know, put ratio, call ratio spreads, call buying, cover writing, you know, various things like that. and each issue came out like once a week. Anyways, the New York Institute of Finance was looking for a book on option strategies and they happened to ask the president of the CBOE, who was Jim Dalton at the time, and he said, well, I don't know this guy, but he's writing about strategies he seems to know he's talking about over at Thompson McKinnon.
24:01So they approached me and I submitted a very long outline for the book and they said, all right, let's do this. And so that was 78. Wow. And the book came out at the end of 79. I mean, they put a 1980 copyright date on it. Just to freshen it up. What's that? Just to freshen it up and make it look modern. Yeah, yeah, yeah. So that was the first edition. You know, it's probably 250 pages or so. But then they really sold it. I mean, they spent a lot of time marketing it. And then New York Institute of Finance was eventually bought by Prentice Hall, and they continued to market it. And now it's on, I think, by Pearson.
24:47But they still continue to market it. You know, some publishers really just publish books, and some people, some of them sell books. That's a big difference. So, Ken, I just want to continue on because I think it's fascinating. What was, was there a turning point in your career that it was like this, something that changed the trajectory or your mindset and what you were doing that really catapulted you?
25:15Well, I don't know. I guess when the options first came out, it was trading some, you know, I had some success. But although, like you said, theoretical values weren't doing you much good. I don't think they still really do you all that much good. Now it's all relative stuff.
25:34But, you know, I really felt that it was potentially a much more lucrative career than being a programmer. I don't know if that's really true or not. But there wasn't anything around it at that time like Apple or Microsoft to be a programmer for. So, you know, so I concentrated on that. And then, you know, once I got to Wall Street, I eventually ended up trading the house account, the proprietary account, which was very lucrative for pretty much all of us. And when you say you were programming, what language was back there? Was it Cobalt? Was it, what was it? No, Bell Labs had invented C by that time.
26:17It just was new. So we were programming in C and the Unix operating system, which never did really take off. I programmed in C Sharp. It's all about where you put the semicolon, isn't it? You know, just put it in the right spot. You're halfway there. Right. All right. In Wall Street, they didn't have Unix or C, but we still managed to get some programs done in Fortran. So you mentor, you train, you've taught, you trade, you write. There's a lot of things that you do, right? But give me what it looks like in the world of options trading. I'm talking about trading now. And what does a typical day look like?
27:04Where does it begin? Where does it end? And what happens a bit in between? You can leave out the lunch break. Yeah. Well, so I have a set of criteria that I look at pretty much every day in terms of some theoretical values. Like, for example, I like straddle buying. There hasn't been a lot of opportunity for that recently, but I'll check that. On our website, we crunch all kinds of numbers every night. In a lot of cases, we just put the outputs of all of our data analysis up on the website. So, you know, that straddle buys are there. then I look, I'm pretty much a large seller of naked options, especially puts.
27:53So I'll look for those, you know, where there just seem to be really skewed and out of line. You know, again, sort of a theoretical value thing. The option straddle buying is also theoretical value. and then uh i was as far as speculation i'll look at put call ratios that's a contrary indicator that has a pretty good track record um especially for individual stocks so again on a given day you may not even find any of these you know it's not like i'm trading a million things a day but we did it just have a buy signal and apple based on the put call ratio people have gotten pretty pessimistic on Apple and were buying a lot of puts over the last few weeks.
Read the full transcript
28:43And that forced the put-call ratio up to a really high level. Same level it was at about a year ago. And then there was a really good rally after that by the stock. So what came first though? Was it the reality of the put-call ratio that just was concurrent with the fact that it was oversold or underloved or underappreciated? Or maybe was it the fact that all these put-call ratio So watchers, sophisticated investors in the market, saw this and then said, well, it's time. Yeah, you never know. And that's the one thing about data or technical analysis. I like to use strategies or if you're using technical analysis, things that make sense, just like you said, that other people are seeing the same thing and acting on it.
29:32because it certainly doesn't hurt to have other people doing the same thing you're doing at the same time, especially if it's big money. So that is definitely a possibility. So just because there's a put-car issue, say, extreme pessimism or something, I won't really just jump in there and buy it until the stock begins to turn and I see that there's actually people starting to buy this stock. Then I'll move in. Yeah. Right, because it's just like the 50-day moving average. You know, what's the importance of the 50-day moving average? Absolutely nothing. But for the fact that other people look at it too.
30:10Right. And it becomes a self-fulfilling prophecy that everybody believes that the first stop of an institutional investor of a stock that they own and love will be to buy more on the 50-day moving average. And then the 200-day, maybe the 150, the 100, pick what you want. But what's the importance of those lines? And nothing except that maybe there is a, when you talk about the big money, the institutions are actually programmed, for better, for worse, for no reason, to buy on the 50-day moving average a stock they're going to hold forever. Right. Just follow along. Follow along. You're absolutely right.
30:45And, you know, some of the old patterns they would talk about, like flags and all that, it doesn't make any sense to me, really, because nobody else is really watching for that. But like you said, if you see an indicator that other people are paying attention to, then it behooves you to pay attention to it as well. Unless you're like an IBD. You look at investors' business daily. And you're a big proponent of, let's say, the cup and handle. Watch for the cup and handle. It's got to be this, this, this. Okay, it's a buy. And then all those people that are following investors' business daily, looking at the top 100 stocks, top 50 stocks, say, oh, that stock just hit the cup and handle, we're going to buy, reach the point.
31:31Or the momentum crowd that's just buying no matter what. It doesn't matter. Or they're selling no matter what. But the put selling is interesting to me. Because I'm going to ask you something. Is the idea that most of the people are mispricing the puts because there's too much potential anxiety or concern? And the fact is that markets generally move from bottom left to top right over time, generally speaking. Well, yeah. And, you know, institutions over the years have now understood that buying puts is a good form of insurance, but they tend to overpay for it. So I'm looking for cases where they're overpaying.
32:12typically they overpay for, you know, SPIRE or SPX insurance. That's the number one thing they overpay for. But then it does spread out to individual stocks as well. Now, do you do options on futures? I do, yeah. That's where the fun begins, right? Right, right. You know, there's been a delist of a lot of futures in recent years. so you don't really have orange juice futures anymore or lumber futures and things that I used to, you know, make some decent money on. I mean, you still got, of course, the S &P futures. That's just like SPX, the same thing. The thing I never understood about options on futures is that there is not a similar timing of the opening of the markets.
33:10Futures trade 24-7 technically during the week, right? Options close when markets close, right? Like 4 o 'clock. So you have all this empty time of anxiety, as I would see it at least. Oh, yeah. So now, like, for example, though, at the Chicago Mercantile Exchange where they're trading the S &P futures, the options trade all the time too. Is that liquidity? Oh, yeah. Yeah, you know, if something bad happens overnight, you can adjust your positions or whatever. But even the CBOE now is trading SPX options starting at 3 in the morning because they realize that, you know, for these foreign traders, Europeans especially, want to, you know, want to trade at that time if there's a reason for it.
33:59Although I wouldn't say the SPX options that trade on the CBOE are all that liquid at 3 in the morning. Yeah. But they do trade. I've stayed away from purposefully things that trade all night because I've done it before. And I got to tell you something. I sleep with one eye open. And I'm like, all right, I might as well get up and do something here. You know? And then you start doing like, oh, look at gold. I'll do, let me put a little trade in that. You know? Yeah. You know what I'm talking about. I often said in my lectures, if whatever strategy you're using is causing you to lose sleep at night, then find a new strategy.
34:38Yeah, exactly. Let's go into the VIX because the VIX is kind of interesting. This is July. I think you mentioned in a discussion we had that July is a seasonal period that becomes kind of an interesting time for the VIX, usually a seasonal low. Vic's under 17 lately. With all the chaos that's going on, by the way, fascinating to me. Truly fascinating. What's your current outlook? Vic's cares are just not all that concerned with tariffs, I guess. They're not concerned with tariffs. They're not concerned with bunker-busting bombs. They're not concerned with putting more warheads and stuff into the hands of Zelensky.
35:19They're not concerned about the Middle East. They're not concerned about anything. Yeah. What is that about? What's your current outlook on this? How are you positioning around it? Right. Like you said, VIX typically has a yearly low right around in June. It used to be right around the first, I'm sorry, July. It used to be right around the first of July, but now it kind of extends through the whole month. But by August, things start to pick up. And I've always said that when VIX is low, that's not the sign to sell. It's when it starts to jump up from having been low, that's the time to sell. And so we're watching for that to happen.
35:59You're talking about sell the calls? Well, sell the market, you know. Sell the market. So with the VIX on, let's kind of pretend, let's do a pretend trade here, shall we? The VIX at, well, it's going to use round numbers for the heck of it. VIX at 17. Now, if you were thinking that, okay, it's going to pick up, would you do something like, what are we in, July? Would you pick up in August something or other VIX at 20? Would you do it on a call side? Would you look to say, okay, well, no, I'm going to buy right at the money? What's your better trade on that? I know it's all about the numbers and all.
36:32I get that. I'm talking about generally. So VIX is interesting. You really need to stay fairly short term because there's a steep term structure in the VIX futures, which is what the options are based off of. So you can have, if you buy a six-month VIX and VIX explodes now, that six-month future is not going to go up for months. but the two week one will definitely be exploding. So what I usually say is you really want to speculate VIX. You only go out, you know, to the next month and probably about 33 % out of the money. So that therefore you're not spending a fortune on these calls, but when something happens is your calls are definitely going to kick in.
37:15Yeah. So, so using what you said, if it's at 17 and we go 33%, You don't want to go over 22, approximately. I'm just going to round number. 22, 23 in that area, you know. And right now, you're still in July. There are weekly VIX options, so they're maybe not as liquid as the other ones, but they do exist. So, you know, you might buy like an end of the month of July and then, you know. I mean, going all the way out to August right now is not terrible, but it's a little bit longer than I would. Right. Maybe the weekly is in August, the first weekly in August, but not first. So is this – so when do you get your trigger, though, on this?
37:58I mean, if the VIX is in this – I think we both agree it seems like the VIX is underrating the risk out there. Am I wrong? Well, maybe it's not. Maybe the fact is it is what it is. I don't know. It depends on how you look at it, right? I mean, like 2006 market, VIX was, I think, went all the way to 10. 2016, 2019, you know, very low for a long period of time. That's what I'm saying. Well, the one thing I kind of watch is the 200-day moving average. If VIX jumps above the 200-day moving average, then it could be interesting. But until it really does that, it's just dull, you know. So I wouldn't be getting too heavily speculating into long VIX calls as long as it's below its 200-day median average.
38:49But once VIX crosses above the 200-day and also the 20-day crosses above the 200-day, that's usually a pretty good sell. Sell saving for the model buy signal for VIX. So are there any sectors or any particular asset classes where you're seeing that there's an unusually high or low implied volatility right now? Yeah, we look for that, too. I'm not seeing much of anything. They're all relatively low, but I don't see anything that's really standing out as far as individual stocks. I mean, as I mentioned, Apple, that's sort of a, I wouldn't say all the rest of the Fantastic Seven or whatever you want to call them are great buys on an option basis, but Apple is.
39:43And, you know, we, of course, look at those. Those are easy ones to, you know, to analyze. But, you know, no, I'm not really seeing a sector that's contributing right now. So when you look at the overall market or you look at the market of a particular stock, there's two different things, right? It's either the markets or the stocks. And I'm not talking about futures, but you mentioned a put-call ratio. So as a contrary indicator. So can you kind of walk us through for, you know, pretend all of us listening have no clue what you're talking about here. We understand there's a call. We understand there's a put.
40:17We understand what those do. But can you understand this put-call ratio and what it means in terms and how to read it and what to look for? Okay, well, I'll give you a little history. The put-cut ratio, as an indicator, was invented by Marty Zweig all the way back in the 1950s. And he was getting the option volume out of the broker-dealer ads that ran in Barron's every Sunday. And so he thought, originally, that he would go with the volume. Quickly found out that there was a lot of calls being traded all over the counter back then. A lot of calls as compared to puts. The market went down. and vice versa.
40:54There's a lot of puts traded as compared to calls. The market went up. So we realized it was a contrary indicator. So that's held true all throughout. So it's just now become a matter of how do you interpret that? We prefer the dollar weighted put call ratio, which is where you take the option price times its volume. And that's how many dollars are being spent on that option. That seems to be the most accurate indicator to me. And in terms of individual stocks, we look for it to get really extreme. And you can tell the extremes if you just look at a chart. So like I mentioned, Apple. So it got up to a pretty high level.
41:34And, you know, now it's rolled over. Like, you know, the put buyers have sort of exhausted themselves. And the put call ratios begin to roll over and start to head down again. And that's the buy signal for the stock. So that's how it works. So it's like a VWAP of it? Is it like a volume weighted price? That's the point. So you're saying instead of just the price, you're saying I want to see actually how much, not only volume, but what's my real commitment? What's the real commitment? Exactly. Because, you know, the people come in and they're buying a lot of cheap, way out of the money options for a few cents.
42:13That doesn't mean nearly as much as if somebody's coming in and buying a bunch of at the money options and spending some real, real money there. That guy's the one you probably want to see what he's doing. But it's amazing. There was a time when they were opening the various option exchanges in Europe. And of course, what they did immediately was trade on their index. And no matter what country it was, it turned out that the Pucco ratio on the index was a great contrary indicator. It's just human nature, I guess. You get all excited about buying the calls. You think the stock's going up and pretty soon you're paying top dollar for the calls and the market turns.
42:57So who provides the put-call ratio? What service? CBOE? So now you have, well, we calculated ourselves. So we just get the raw data from, well, So we mostly get ours from DTN, but you could get it from the CBOE, but that's only the CBOE there. We try to get all the option exchanges. And then what does the numbers look like when you say, so I think it's, isn't it above and below one? Yeah, so one means that's an equal, so you divide the, you take the put calculations. So for each option, let's say an IBM. At the end of the day, you take the option price times the volume that traded that day, and you multiply them together.
43:41And then you add them up for all the puts. That's one number. And to add them up for all the calls, you divide the two. That's the put-call ratio. So if they're equal, it's one. Typically, you know, and to me, it's a relative thing. So I can't just say that if a put-call ratio is two, we should be buying it. That's not really the case. you need to look at the chart, as I said, to see how it's behaved in the past. But with Apple, for example, you know, it had a really nice move, you know, about a year ago. And that worked out great. I'm just going to look and see what the put-go ratio actually was at that time.
44:22but you know it's uh it's it's done a really nice job of um giving us some some trades where you might not else uh otherwise be looking for trades and it works for futures too so i mean i know there was a great buy say like cocoa last year and the options were relatively cheap at the time now cocoa options are not cheap anymore so when you get when you get you get to the point of whatever it is. I mean, again, it's looking at a put-call ratio of, let's say, I'm just picking a number, two. That means that there's twice as many options traded on the put side from your calculation than it is on the call side, meaning that people are pessimistic.
45:06Right, exactly. So the higher the number, the more pessimistic they are. The lower the number, and it can't get below zero, of course, on that. What's the highest put-call ratio do you recall ever seeing? Oh, ever? I mean, there's some crazy ones, but you have to watch out that you're not getting involved with getting mixed into an arbitrage situation. That gets distorted. You know, for like right now, yesterday, CoreWeave made a bid for a small stock called CORZ. And the puts on CoreWeave are just crazy. But it's not that everybody's expecting CoreWeave to go down. They're just hedging. It's a stock-for-stock arbitrage deal, so they're just hedging the deal.
45:51So there's some common sense involved, too. So I'd say profile ratios as high as 10, 11, 12. They're actually seeing to make some sense. Earnings season is coming up next week. How do you approach that from an options standpoint? So I have a very specific way that I like to look at these. I take a, there's a website called optionslam.com, which has just all kinds of data regarding earnings and what the stock did after the earnings came out. And it turns out that, you know, I'll take those, let's say take the last 10 and you take the earnings, the post earnings move, you can do one day or three days, whatever you want.
46:38I usually just do one day. And then I look at the current situation coming into the earnings. And if it's, you know, if it's low enough price that you don't have a, you know, in the past it's moved much farther than you're looking at right now. Let's say seven of the last ten have moved more than that. Then I'll buy the straddle. And typically I'm out the same day, the next day. So it's just a statistical thing. I mean, I'm not predicting the earnings or anything. There are sometimes ways if you see heavy option volume before the earnings, but the SEC cracked down on a lot of that stuff. So if you're doing that, you could get a visit from a regulator.
47:28Oh, boy. That's not good. I'm just looking at Apple right now. This last one recurred at about 2.4. So$240 are being spent on puts for every$100 being spent on calls, if you want to look at it. That's a lot. Yeah, yeah. That's a lot. And that was very late June, so that's rolled over now, and that's why we're buying it. So in February, there was this false upside breakout, right? Right. We're seeing that after the recent downstroke of the tariff tantrum in March, everybody is just all happy go lucky buying. Do we have something like that going on now? Is that is that in the future cards? So I think this one right now is much more positive, much stronger.
48:28I'm seeing better readings from all the internal indicators, including put-car ratios. Put-car ratios are low on the index because it's been going up for, what, two months now. But they're not turning. They're still going down. As long as they're still going down, I think the market has some upside. And other things like new highs versus new lows, that just gave a new buy signal for us. And, you know, as we noted before, VIX is not rolling over and starting to rise either. So this is much stronger, I think, than the one in February. Pretty fascinating. Again, considering all the crap that's going on.
49:08You mentioned a couple of high dividend yielding ETFs. I'm kind of curious why that was something that you thought would be an interesting thing, because it's kind of outside the bounds of what we're talking about. Right. So we got questions because the way these are constructed, they use options. So we got questions from people about, you know, could you just do an analysis on this or that situation, you know, with the – well, I think the first one we did was NVIDIA. So there's a covered writing ETF on NVIDIA where they write covered calls. And its symbol is NVDY. You mentioned MicroStrategy.
49:56There's a good one on that, MSTY. So it's typically the same letters as the underlying with the Y on the end. Tesla has one. Coinbase has one. And the Y stands for yield or income, either one. It is something, I guess. I don't know, sort of a convention at this point in time. But what these people are doing, and it started out, they were just writing cover calls and trying to use maybe some leverage. And then these stocks went up so much that the cover calls were cutting off the profits on the upside. So they decided to do the call credit spreads. So that was an interesting thing. So we explained that to people, and that's why we were analyzing them.
50:40But they pay a huge dividend. So like the MicroStrategy one, I think in the last, it's more than it's paid its entire price out as a dividend in like about 16 months. And so you could have bought that, you know, 16 months ago, held it, and now you own it for free. It's taxable dividends, yes. But now you basically own it for free. And they are, you know, it doesn't have the upside of MicroStrategy itself, but it also doesn't have the downside. Sure. So these are things to look into is if you want to maybe have some option-based strategies, but you don't want to do it yourself. Right. And you definitely have to believe in the underlying.
51:27You know, you got to believe in Bitcoin if you're doing MicroStrategy or Coinbase. You have to believe in NVIDIA if you're doing that, you know, the NVIDIA one or Tesla, whatever. And there's a couple, there's a one that Morgan Stanley has called JEPI, J-E-P-I. I'm not too impressed with that one. That's supposedly doing covered rights on a broader way of stocks, but it seems like there's something wrong in the performance there. It doesn't really seem to be performing as much as it, as well as I think it should. Interesting, interesting. Well, Larry, it's been a pleasure. All sorts of great information today.
52:07I know my listeners will look for more. We have the information on how to get in touch with Larry on the show notes for episode number 929 over on thedisciplinedinvestor.com. And we'll make sure that people know where to find you, my friend. Okay. Appreciate it. Appreciate it. Have a good summer. All right, Andrew. You too. Thanks. Yeah. Well, we cover so many different possible things on this show. Options, futures today. Just some of them and some great information from Larry there. So that was, this is a guy that's a master of what he does, folks. This is the guy that wrote the book on what he does and what is used throughout the industry.
52:46So hopefully you paid attention to what was going on there. And yeah, for a lot of it is probably like, what did he say? Listen to this again. Get his book. Whatever you got to do, options are a really good play. When it comes to hedging portfolios and utilizing it inside of what you can do, as long as you understand what's going on, understand the risk and all that. But it's something at least to have in your toolbox. That's the whole point. Having it in your toolbox really gives you the benefit and the opportunity if you need to use it. So there you go. Next week coming up, Anthony Scaramucci is going to be on the show.
53:23So we're going to be looking forward to that. Probably going to be talking about Bitcoin and all sorts of crypto and all things in between. Thank you for joining me this week and every week. I hope you're having a great summer. I'll see you again real soon.
53:44This podcast is intended for informational purposes only and does not constitute personalized investment advice. Investing involves risk, including the possible loss of principal and past performance is not indicative of future results. The views and opinions expressed are those of the host and any guests and may not necessarily reflect those of Horowitz and Company, Inc., an investment advisor registered with the U.S. Securities and Exchange Commission. Registration with the SEC does not imply a certain level of training or skill. Advisory services are only offered to a client or prospective clients where Horowitz and Company is properly registered or is excluded from registration requirements.
54:22Any mention of third-party companies, products, or services is provided for informational purposes only and does not constitute an endorsement. Hypothetical scenarios or forward-looking statements are for illustrative purposes and should not be viewed as guarantees. Content is intended for U.S. residents only and may not be applicable in other jurisdictions. Listeners should consult a qualified financial advisor before making any investment decisions. Please visit our website for additional information, disclosures, as well as a copy of our form CRS. Advertisements are not related to the host or affiliates and are not considered recommendations by the host of the show or any affiliate support.
From the publisher
The OBBBA is signed into law.
Letters are going out with a new deadline.
Coming up on earnings season – JPM reporting on the 15th – next week.
And our guest – Larry McMillan – The Options Strategist.
NEW! DOWNLOAD THE AI GENERATED SHOW NOTES (Guest Segment)
Professional trader Lawrence G. McMillan is perhaps best known as the author of Options As a Strategic Investment, the best-selling work on stock and index options strategies, which has sold over 300,000 copies. An active trader of his own account, he also manages option-oriented accounts for certain individuals. In a research capacity, he edits and contributes to his firm’s publications: Daily Volume Alerts, The Option Strategist and The Daily Strategist – derivative products newsletters covering equity, index, and futures options. Finally, he speaks on option strategies at many seminars and colloquia in the United States, Canada, and Europe.
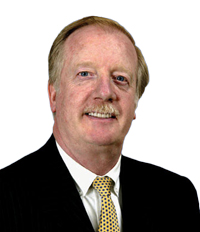
He is often seen on CNBC and Bloomberg TV and is quoted in publications such as The Wall Street Journal, Barron’s, Technical Analysis of Stocks and Commodities, Data Broadcasting’s “Exchange” magazine, Futures Magazine, theStreet.com, Active Trader Magazine and many others. In 2011, Mr. McMillan received the prestigious Sullivan Award in recognition on behalf of his outstanding contributions to the growth and integrity of the U.S. options markets.
CHECK IT OUT To claim the offer attendees should visit www.OptionStrategist.com/TDI
Check this out and find out more at: http://www.interactivebrokers.com/
Looking for style diversification? More information on the TDI Managed Growth Strategy – HERE
Stocks mentioned in this episode: (AAPL), (NVDA), (JPM), (NVDY), (MSTY)