Ask ChatGPT
 Alt Goes Mainstream: The Latest on Alternative Investments, WealthTech, & Private Markets
8 Sep 2026 · 59m · 32 chapters
James Li, president/partner at Davidson Kempner, explains how the firm’s principal, family-office DNA drives a “no situation is too complex” approach to liquid and illiquid credit. He discusses convergence/divergence of credit markets, deglobalization as a long-running theme, and why opportunistic credit opportunities are emerging as private capital vintages from 2018–2022 mature and face refinancing/mark-to-market pressure. He also covers DK’s integrated hedge fund and private credit “multi-strategy” model, its lack of reliance on leverage, and why it’s building a Wealth Channel-focused business.
James Li previously worked at Goldman Sachs: intern in Special Situations; ~9 years in prime brokerage covering hedge fund clients; later relationship management for large institutions, including Davidson Kempner, before joining DK in 2018.
DK aims for differentiated, relative-value returns; uses liquidity optionality and real-time feedback from liquid markets to inform private investing; expects 21% of private capital since 2015 to be below an 8% hurdle; sees “capital solutions” and loan/workout opportunities as private credit indigestion plays out.
pandemic-era discount buying of investment-grade; US covenant pressure from CLO/direct lending; “pull-to-par” in public loans (e.g., buy at 80 cents, exit near 95–97); distressed recovery of “par plus accrued” (e.g., buy at 40 cents, recover 70–80); capital solutions via second lien/MEZ/warrants; merger arbitrage treated like fixed income by deal-spread probability.
Written by AI. May contain mistakes.
A look into Davidson Kempner’s history and investment philosophy.
“Great conversation with James, really enjoyed it.”
Michael welcomes James Li and sets the stage for the discussion.
“James, welcome to the Alco's Mainstream Podcast.”
James discusses his career path and experience in private markets.
“And I think what a fascinating conversation we have on tap today.”
Discussion on the generational transitions within Davidson Kempner and its impact.
“How have all of those experiences informed how you think about private markets today as you help run Davidson Kempner?”
James explains how Davidson Kempner approaches complexity in investments.
“So Marvin Davidson initially was a senior executive at Bear Stearns and started what was initially called MH Davidson in 1983.”
Insights on how Davidson Kempner operates within both liquid and illiquid markets.
“speaking, there's multiple ways to kind of get to a potential return.”
Discussion on macroeconomic factors affecting investment strategies.
“So like you have all these different vantage points.”
Learn how changing market cycles affect both liquid and illiquid investment strategies.
“public or private, more challenging in many respects.”
Understand the significance of a global footprint in the context of deglobalization.
“is heavily invested in the deglobalization theme broadly.”
Explore how competition varies across different investment markets and its implications.
“substantial amount of leverage is just hard.”
Dive into the complexities and challenges faced in private equity and credit post-GFC.
“And so that becomes, I'd say, a very key element of why are we getting the price and what's our margin of safety relative to the other competitive dynamics that are happening in that sub-market.”
Learn about capital structure challenges and the need for refinancing in today's market.
“I'd love to unpack that and tie it to some of the data that you've looked into.”
Discover how a private equity mindset influences investment and restructuring strategies.
“eventually pay the principal back because your refinancing proceeds won't cover the full principle of your legacy debt stack.”
Understand the benefits of integrating public and private investment approaches.
“and create that investment on a de-risk basis because we're creating it through the debt.”
Learn about the diverse strategies in both public and private credit investment.
“Where do you think you get the most edge or value from that information sharing between public and private?”
Explore the evolving view of credit allocation and its implications for investors.
“But I'd say we approach both public and private markets with a very expansive toolkit, which I think has become somewhat underappreciated in the growth of primarily par lending.”
Explore the relationship between fixed income allocation and private credit in today's market.
“And so people said, well, there's actually, there could be a correlation between this equity and fixed income allocation.”
Discuss the current interest of allocators in hedge funds and the lessons learned from past financial crises.
“is if I'm ultimately putting this allocation into the fixed income cash replacement bucket, is it really liquid?”
Understand the importance of aligned incentives between hedge funds and their investors during volatile market periods.
“but they really want something that I think has been tested through cycles on the secure and defensive part of their allocation portfolio.”
Learn how multi-strategy hedge funds operate and their approach to investment design and liquidity.
“Whether or not you do that in the future is, I think, irrelevant in the context of this question, which is like a hedge fund in a sense is an evergreen vehicle.”
Examine various credit investment strategies and how they are managed for optimal performance.
“And we've done that with a very low vol.”
Delve into the intricacies of merger arbitrage and its implications in equity and credit markets.
“You mentioned you do merger arb, you do both equity and credit.”
Explore how the investment-led structure of the firm shapes its investment philosophy and decision-making.
“You better bring something in credit for marginal dollar that's going to be competitive to an ARB deal.”
Learn about the differing incentive structures for public and private investment firms.
“And I give a huge amount of credit to a number of the big public alt firms.”
Explore how market changes affect investment strategies and competition.
“If you said, okay, I really like music royalties, there's people that are unbelievable music royalties, but what if spreads compressed in that space and you've committed to a fund and that's the only thing that they do?”
Discover the opportunities in dealing with smaller loans and restructurings.
“may not move the needle for some of the really large firms.”
Understand why and how firms are developing wealth-channel services.
“As you mentioned, you're the largest investor as a firm, so it's your principal.”
Learn about the importance of educating the wealth channel on alternative investments.
“And I think for a period of time, there were firms that simplified their message and made the product so easy that those were the firms that ultimately kind of garnered and gained the most share.”
Examine the evolving landscape of private credit and its implications for investors.
“And so I think that there are many different forms of alpha that investors can use to complement their total portfolio allocation.”
Explore the vision for growth and strategic direction of Davidson Kempner.
“And as you said earlier, like the counter to that would be opportunistic credit.”
Learn how the firm leverages its expertise in credit and structured products to expand its business.
“advantage across a wider range of products.”
Understand the firm's long history and its vision for future growth amidst evolving market opportunities.
“I think it's clear you're so excited about the different things that you do and also the opportunity set going forward.”

Get the gist, explore an idea or ask about something said.
 Claude
On Alt Goes Mainstream: The Latest on Alternative Investments, WealthTech, & Private Markets, what are the key points of this episode?
Searching your listeningAutomatic transcript. May contain errors.
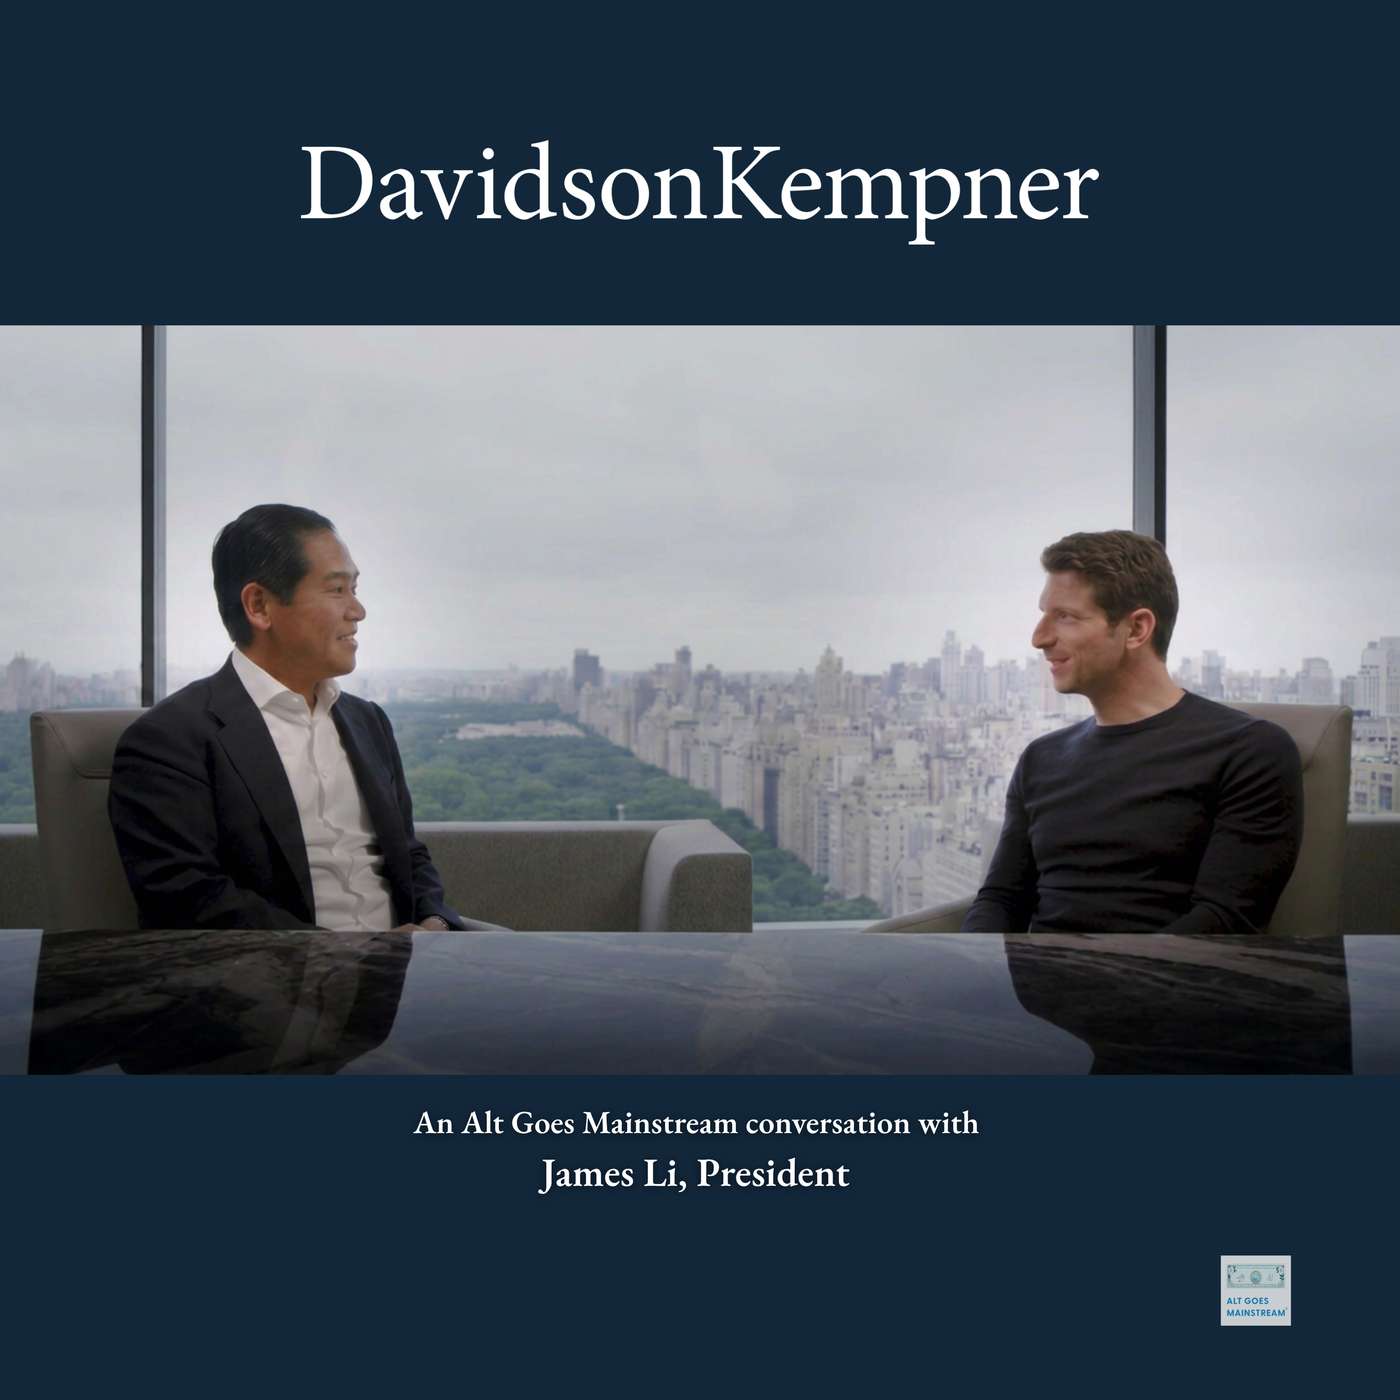
0:00Welcome back to the Altco's Mainstream Podcast. I'm here from Davidson Kempner's office, live in New York, got Central Park behind us, and a great conversation on tap with James Li, president and partner, Davidson Kempner. Davidson Kempner is a$40 billion alternative asset manager steeped in both the hedge fund world as well as private capital. The firm has founding history as a family office. It started as a family office in 1983, started taking outside capital in 1987. And as James talked about, there's this old firm, young energy feel to such a fascinating, interesting firm that finds value in complexity, doesn't mind complex situations, as they've said on their website, takes a principle approach mindset.
0:48And we just had a fascinating conversation about what's going on in credit, both liquid and illiquid credit, how those worlds are both converging and diverging, how private capital, private equity, private credit may be creating opportunities for things like opportunistic credit, and how and why Davidson Kempner is thinking about the Wealth Channel and what that means is an extension of the firm's history and the three generations of leadership that they have. Great conversation with James, really enjoyed it. Such a fascinating discussion about different nuances within both hedge fund world and private capital world.
1:23So here we are.
1:36And now a word from our sponsor, Altimus Fund Solutions. This episode of Altgo's Mainstream is brought to you by Altimus, the full service fund administrator and transfer agent powering asset managers in private and public markets. As Altgo Mainstream, you need real expertise to handle complex fund structures, connect with key distribution partners, and handle sophisticated compliance, reporting, and transparency demands. That's Altimus. High-tech, high-touch solutions for over 450 clients and 2 ,500 funds with over$775 billion in assets under administration. Backed by an expert team of over 1 ,200 employees, they place client service at the core of their business, helping you navigate complexity during your fund structuring or launch, and then supporting you through every stage of growth.
2:20Whether you're already in the market or thinking about entering private wealth, you can trust their team's deep expertise in retail alternatives to help you reach your goals. Learn more at ultimisfundsolutions.com or email info at ultimisfundsolutions.com. We're going mainstream. James, welcome to the Alco's Mainstream Podcast. Michael, thank you for having me. Big fan of the podcast. Appreciate it. Well, thanks for having me here. We got a fantastic view in the background of Central Park. And I think what a fascinating conversation we have on tap today. Such an interesting evolution as a firm.
2:53Davidson Kempner, your career, you've also seen all the different aspects of private markets on both the liquid side and the liquid side. And you're really straddling those two worlds in many respects at DK today. So we'd love to start with your background because I think it's instructive in terms of how you think about private markets broadly, as well as the hedge fund universe. You were at Goldman. You covered hedge fund universe. You worked with alternatives managers. You've handled client relationships. How have all of those experiences informed how you think about private markets today as you help run Davidson Kempner?
3:33Sure. Thanks. Thanks again for doing this. Happy to have you in the office. I started my career actually at Goldman as an intern in the Special Situations investing group. And coming out of school, I was excited to get an investing seat. That group was renowned for doing value and distressed investing. And I didn't realize how that would boomerang back to the latter part of my career. my senior year of college a number of the partners that ran that business actually left to start alts firms and I had an option to effectively go back to a different desk and I ended up joining the prime brokerage business out of school and I didn't know very much about prime brokerage but I loved it and I spent almost nine years working with hedge fund clients across a pretty wide range of strategies and working with them across various different investment strategies, how they deployed their business, how they built their businesses, how they raise capital, how they frame those to investors.
4:27And then in 2015, Goldman was rethinking how to structure their senior relationship management efforts. So this was a group that covered the largest institutions at the firm. And there was a real focus on moving away from just covering the monoline businesses. So if you were a sponsor coverage banker for private equity, you are used to dealing with M &A deals and maybe real estate. But if there was a growing private credit business, that may be a financing opportunity within fixed income. And so I joined this group and we sat private side. I covered 10 of the largest accounts at the firm. One of those firms ended up being Davidson Kempner and serendipitously spent a few years covering the firm and building a relationship with a number of the partners.
5:12And then ultimately had the opportunity to join here in 2018. You covered a lot of different hedge fund and alternatives clients. What about Davidson Kempner was different to you? What was exciting to me was this was in 2018. Tom Kempner was still running the firm, but had really handed off day-to-day functioning responsibility to Tony Yosilov. And Tony is our managing partner and CIO now. And so Tony was already running the investment process and was transitioning to run the rest of the business. And Tom Kempner actually was our second leading managing partner. So the firm was originally started by Marvin Davidson and Marvin had handed the firm over to Tom in 99, 2000.
5:56And I saw the spectacular success that generation two was able to have over that 18 year run. And the opportunity presented itself to be part of what would eventually become generation three. And that was too interesting to pass up. So a few interesting things in there. One is Davidson Kempner has now gone through three generational transitions. I want to start with the formation of the firm. I think that will also get into some of the generational transitions of the asset management business and how that informs how you think about investing. Because I think that probably does. Every firm's DNA, I think, is reflected in its culture, its values, its investment.
6:40culture as well. The firm was started as a family office, correct? How do you think that informs how you think about investing and running the business today? It's core to our DNA. So Marvin Davidson initially was a senior executive at Bear Stearns and started what was initially called MH Davidson in 1983. And then Tom Kempner ended up joining and the The firm started to run outside capital in 87, but the firm operated as a single family office for four years. And so a few things that are relevant are one, Marvin was generous in sunsetting his equity because he wanted the firm to have durability and staying power.
7:25And he wanted the working class of partners to own the economics of the business. And then in addition to that, Marvin's capital, and then eventually the other partner's capital became and still today is the largest single investor within our complex. And so we've always thought about a few things. One, how do we want to invest our capital side by side with our clients? How do we think about products that we're excited to put capital into? And therefore, we hope our clients will ultimately want to put capital into. And then how do we create the right long term alignment where as the current generation doesn't have to think through outside shareholders, whether that be having sold a stake or someone that initially seeded the firm or ultimately potentially having gone public.
8:14And so we can align around a longer term incentive of how we ultimately want to invest the capital. That's a good jumping off point to how you think about investing capital. You walk outside and there's the values on the side of the wall. Acting like a principal is one of them. Another thing that comes through when you read the front of your website is complexity. There's no situation that's too complex for you. I think another aspect of DK's story is the fact that distressed is in the DNA and complexity is at the core of a lot of more challenging investment opportunities, but then you find a way to create value.
8:53How do you think about approaching complexity from an investment perspective? And how do you then underwrite that complexity across the different aspects of your business on both the liquid side and the illiquid side? Whenever a new investment comes through investment committee or portfolio reviews, there's usually this question of why is this investment coming to us? And if we're the winning bid, why are we the right pool of capital to potentially purchase this asset? And so broadly speaking, there's multiple ways to kind of get to a potential return. And we tend not to be dependent on leverage, and we tend to have a fairly high cost of capital.
9:31And our investors want us to deliver differentiated returns relative to what you could potentially get in credit indices or equity indices. And so oftentimes we need to think about what is the kind of angle here that creates this opportunity set for us. And so I'll give you a few examples. there could be market stress, and the instrument that you're purchasing is not complex, but the environment's complex. So that would be the pandemic period where you could buy investment-grade assets at a 20 or 30-point discount, and that investment is not complex, but the environment is complex. Our footprint is global, and close to half the firm's assets are invested outside of the U.S., but that may be going to a market where you have less competition that we've seen in U.S.
10:17credit markets. So the growth of credit in the US and the growth of CLOs and direct lending has put a lot of pressure on covenants, for example. So you may go into a certain market like that, and that may be your complexity premium. Or more classically in distressed, you're not necessarily making a performing loan. You're going to have to go and work that situation out. And your value creation is going to come from not just your coupon, but some accrual back to par over a period of time. Where do you think the best risk adjusted returns are made from investing in complexity? I would say this has always made our products hard for investors to understand because we create a lot of flexibility and we want to be nimble and dynamic depending on what the environment delivers for us.
11:07And so I would say in any given situation, we're very much a relative value-oriented shop. And being a multi-strap manager, we're constantly scouring a range of markets and then comparing the relative opportunity set that we are being shown. So in certain periods, you just have to know what the risk that you're taking is. And that type of risk is going to be priced different ways in different regions over different periods of time. One interesting thing there where my head goes is because you do a lot of distressed and opportunistic credit, and you may see things in certain sectors or markets or geographies before others might in different asset classes.
11:52How does that inform how you think about investing? And then you have the benefit of the liquid side and you've both, you've had and held assets in private markets and then from maybe a workout and then it's gone public and you've bought it in public markets and the credit side. So like you have all these different vantage points. How do you think about how some of those vantage points inform how you invest and where to delineate between the risk and return? Our business today is a little north of$40 billion. and roughly$25 billion of that is in hedge fund assets and about$15 billion in private products, the largest being a drawdown distress strategy or opportunistic credit.
12:34And the biggest product there is our multi-strategy and that is a multi-product business that does both credit and relative value equity investing and then ultimately invests globally. And so if we think about the way that we invest, if you're in a liquid instrument and you're wrong, you can get out and you're constantly being given feedback from the market as it relates to was your purchase price a good purchase price or not? And what catalyst were you ultimately expecting to get to that value realization? In private markets, you don't always have that benefit. When you commit capital, it often becomes harder to then change your mind and you're not always getting the same feedback loop.
13:15And so having a large liquid market business allows us to kind of assess in real time how the market is thinking about risk and allows us to also have the resources to have kind of the velocity of information processing, which is a big benefit that we ultimately utilize for our private business. On that point, how do you think about some of the macro forces, because you're able to see this from the hedge fund side. But one, market structure has changed. Two, there's been more challenging rate environment, maybe more uncertain rate environment in a sense. Maybe it's higher for longer, so we should talk about that too.
13:57And three, the dynamic geopolitical landscape, I think, is making all investing, whether it's public or private, more challenging in many respects. How do you think that impacts these relative value opportunities and also how long you have to express those specific themes? Because if cycles happen faster or markets change quicker, maybe on the liquid side, it's okay. But on the illiquid side, maybe that's a bit more challenging. I'll talk about one broad theme and then I'll give you a number of sub themes because I also think some of the trends that we see are slightly different between the liquid markets business and the privates business.
14:37So broadly speaking, I'd say over the last 10 plus years, the firm is heavily invested in the deglobalization theme broadly. Not to say that we believed that this would happen 10 plus years ago, but we've been in Europe for north of 25 years and we doubled down in the GFC when a number of people pulled back. And then we've been in Hong Kong for north of 15 years and then ultimately opened an office in Mumbai and Shenzhen during the pandemic, where I think a number of people were fleeing those markets. And then over the last few years, we opened an office in Abu Dhabi. And so one, just around the broad deglobalization theme, I think it's increasingly important, especially for credit and value-oriented investors, to have a global footprint because of the nature of how capital cycles have flowed.
15:26There's been so much capital formation that's happened in the U.S. that irregardless of what you think about the macro economy in the U.S., and I hope it continues to stay strong, credit spreads are tight. And so the effective ability to earn reasonable returns without using a substantial amount of leverage is just hard. And we can talk about some of the themes that we're finding in U.S. credit, but we found it important to be in a very broad range of markets to give ourselves flexibility on a relative value basis globally. And we want it to be in those markets locally, not just investing out of the U.S.
16:00On that point, and tying it back to the complexity being core part of the DNA, do you find that you'd rather go to markets that are more complex or smaller, not as crowded, maybe a bit riskier, but that's where you generate return? Or is there some other way that you look through the prism of balancing that risk and return? We think a lot about who is the competition and what's the marginal buyer look like. And the marginal buyer for a new loan for a leveraged buyout in the US is extremely competitive. The marginal buyer for a non-performing loan portfolio in the Middle East or in Asia is going to be more limited and potentially not as well resourced or as sophisticated as we are.
16:49And so that becomes, I'd say, a very key element of why are we getting the price and what's our margin of safety relative to the other competitive dynamics that are happening in that sub-market. I would say that's true in the private market because it tends to be more of a bid at a longer time horizon. And then in the public markets, if you're not local, you can often miss the velocity of a trading cycle. You know, the credit portion of our multistrat is designed to have a high degree of velocity. So we don't want a lot of duration in that portfolio and we don't want to just buy to hold. Maybe if I go back to some of these other kind of broad themes, because I think they tie into your fundamental question.
17:27And one of the themes that I think we are quite excited about relates to how we think about this capital dynamic is post the GFC, there was growth in private capital. And that growth largely came in private equity and private credit. I don't think it's controversial to say that there's some indigestion in that space today. And that's one of the themes that we're very excited about as opportunistic investors, because there's many ways to kind of address that, you know, that unraveling or that need to get capital through the system. I'd love to unpack that and tie it to some of the data that you've looked into.
18:06A recent white paper you did, I think, found that 21 % of private capital invested since 2015 is below its 8 % hurdle rate. What does that mean to you as an opportunistic credit investor? So a lot of capital was deployed when rates were zero. And a lot of that capital was deployed for a very long time horizon. And so I think we're still at the somewhat early days. I mean, the press has written about this, but we're still in the very early days of getting some of those vintages, whether that's 2018, 19, 20, 21, even 22, getting that capital back to investors. And record amounts of capital were raised during that period.
18:47So the first path is you can work with the equity sponsor. You have a good business, but you don't have the right capital structure because your capital structure was set up in a zero rate environment and you haven't necessarily fully grown into your capital structure, but you need to refinance your business or you need to eventually pay the principal back because your refinancing proceeds won't cover the full principle of your legacy debt stack. And so there's been a lot of opportunities in what are typically called capital solutions. So that allows you to go and reset what the capital structure looks like.
19:17It may be doing something with the existing first lien. It may be putting in a piece of second lien. It may be ultimately putting in a mez piece that partially delevers the first lien and gives you some warrants into the business. And so that's kind of one path where I'd say you believe that the equity can support incremental debt and they need a custom piece of debt to effectively get to that outcome. The other is where you think there could be impairment to the effect of equity, but the private credit first lien or senior debt is in a good place. And you're seeing a lot of this in the press today.
19:55Not all those loans are marked at par, and that would lead you to believe that there may be some issues with the potential equity. But a number of these firms don't want to do all the workouts, or they ultimately may not want to operate that individual business. And so we've learned this in the public markets as well. And so engaging with the private credit group to potentially identify individual loans on companies that we may want to buy, especially as marks start to be rationalized. And I think that's something that we're going to continue to see. Do you have to have a private equity mindset when underwriting those types of deals if you're ultimately going to do a workout and operate the business?
20:38Or is it more of a credit mindset where you figure out how to get those capabilities either from bringing in a team or partnering with someone who can do the workout? Yeah. So one of the big evolutions here is in Gen 3, I'd say we have invested in the infrastructure for our private business holistically. So today, approximately 30 % of our assets are in private assets. And always through a public market lens, if you restructured a public broadly syndicated loan to own the equity of the business, you ended up becoming the equity owner of that business. And so we always had operational chops, but probably more restructuring oriented chops.
21:21And oftentimes those were done in combination with other potential creditor groups and you would bring advisors and agree upon management teams, we realized the benefit of if we could restructure businesses and assets ourselves and control them and build our own operating partner platform, we could add a lot of value to the equity and create that investment on a de-risk basis because we're creating it through the debt. And so I'd say for a number of years now, we've had to have more of a private equity mindset because we found ourselves ultimately owning and operating businesses largely through the debt.
21:58But the end position is you're the controlling equity holder of that business. How has that changed some of the complexion or culture of the firm, if at all? We have one integrated global credit business. We've built a different set of support infrastructures for the public versus private business. So in the public business, you need traders, you need a treasury team. In the private business, you need a capital markets team, you need sourcers, you need an operating partner platform, you need workout expertise in both public and private. But we also have purposefully not put any walls within the organization, meaning we want the teams to be able to collaborate.
22:38And so there's a huge amount of shared information that can be leveraged across our research or quantitative research efforts, as well as just commentary and understanding of what's going on with public comps for private businesses. And so having those teams integrated as one effective business, but realizing that the sub-skill sets of someone that is trading public bonds versus potentially operating a private business can be slightly different. Where do you think you get the most edge or value from that information sharing between public and private? Is it an understanding of sectors or industries from the public side that you're able to port over to the private side?
23:20Is it the private side informs what's going on in private markets and that helps navigate public markets better? Like where is the value really captured in a way that a purely private capital firm just can't do? Can I say all of the above? Yes. Yes, you can. No, I would say it's a little bit of all of those. I mean, listen, we really have a hedge fund DNA. And so if you think about the DNA of being relative value and event driven, which is a real kind of core DNA, you're constantly scouring and having a global mandate. You're constantly scouring where you see the best risk adjusted return. And I would say that that comes across geographies.
24:03It comes across sub-strategies within credit. So just from a sector perspective, you could say, which sectors ultimately do you want to invest in? It also could be, how much do you want to be in structured products, corporate credit, specialty finance, hard asset investing, like infrastructure and real estate. So we have all those businesses. And then how do you think about the value catalyst to repayment? And so my sense is most of your guests think about private credit as primarily being par lending, but there's many other ways to invest in credit. In March of this year, there was a lot of sell-off in public loans of SaaS businesses and technology-oriented businesses.
24:40Many of those we think are going to be okay. And so if you can buy loans that you think are worth par at 80 cents, your return is a current coupon plus 20 points of principal. That would be classically what we would call a kind of a pull-to-par process, which is not just your coupon. And then you could potentially exit that position when the loan trades to 95 or 96 or 97 because you captured a substantial amount of the embedded return versus having to take the risk of holding that loan for however long and not realizing if you're going to continue to keep that coupon and get that principal back.
25:13And then similarly, I'd say in distressed, they're almost always never paying a current coupon. And so oftentimes something is not performing for a reason or it's picking or it's fractionally paying. And so the majority of your return is going to come for what distressed investors would typically call par plus accrued. So you buy in a loan at 40 cents and you hope to recover 100 cents plus accrued interest. That doesn't always happen. But if you can buy a loan at 40 cents and go through a process and recover 70 or 80 cents, that's a very compelling return. But I'd say we approach both public and private markets with a very expansive toolkit, which I think has become somewhat underappreciated in the growth of primarily par lending.
25:58I think that's an interesting way to frame it, particularly for allocators, as they think about where credit broadly. I mean, if we think about the market structure of credit, it really feels like it's moving from there's a carve out for private credit versus liquid credit or fixed income. And it's now become this kind of spectrum of I want to invest in credit from liquid to illiquid. And I'm going to take different types of liquidity risk and maybe other types of risk as well, but also maybe different types of return. I think you kind of touched on that and I want to unpack that a little more because I think it's an interesting way for allocators to think about it but how should they then bucket one some of these other categories of credit outside of direct lending so things like opportunistic credit and then even the liquid side of what you do there may be some semblance of similar return profile but different liquidity profile so how are you seeing allocators, whether institutional or wealth, think about this today versus the few years ago where direct lending was really on the rise?
27:12I try to anchor myself back to a legacy 60-40 split. So on a historical basis, people would say, I'm going to have an allocation to equities. That's going to be my high compounding growth over a long period of time. And I'm going to have my allocation to fixed income. And that's going to be my defensive, slow and steady allocation. And then historically, the view was you could put an alts to kind of smooth the effective return of what that total complexion looks like. And then at a certain point, people said, well, the fixed income return in zero rates is too low. So how do I get excess return for that cash or fixed income defensive allocation?
27:51And then furthermore, I would say in 2022, both parts of that trade went down. So equity sold off and fixed income sold off, credit sold off, but so did even treasuries. And so people said, well, there's actually, there could be a correlation between this equity and fixed income allocation. And so you started to see, at least from our perspective, more investors take that fixed income allocation and potentially put it into some spectrum of private credit, largely speaking. And so if we think about our hedge fund business, which a lot of allocators would call absolute return, we've also gone after that same bucket traditionally, because it's a similar return stream with low volatility and low correlation to equities and credit.
28:37And so I think that persists today. And with rates being higher, people can actually, Tony uses this line a lot, can get home with absolute return where it is, because typically if you could compound at 10 % and if you think that's slow and steady, you can ultimately afford to take lots of different types of risk with your equity bucket, whether that's in public equities, which have had a great compounding rate, or whether that's in venture or growth or in private equity. I think the other thing that people are digesting today is that the correlation between private equity and private credit are actually quite high.
29:14So decoupling those two pieces didn't fully happen where people are sitting and saying, okay, well, if these two asset classes are somewhat correlated, how does that work? And And then I think the other big question for allocators, which they're also processing, is if I'm ultimately putting this allocation into the fixed income cash replacement bucket, is it really liquid? And so I get an illiquidity premium, but how much of the illiquidity premium should I be spending on a kind of fixed return asset class relative to a higher expected return asset class given materially more risky? Are you seeing more allocators shift over to the liquid side of what you do?
29:58I think about this a lot because I was working in the hedge fund business at Goldman through the great financial crisis. And I think a number of people had poor experiences with hedge funds. I do potentially see some general parallels where I believe in what middle market direct lending is. It just maybe got too big and too many people got into it. But that asset class will persist and remain and it's an attractive asset class. I think the benefit that absolute return managers are having today is the firms that went through that strain and dealt with people being upset around crystallization of losses and then earning incentive fees later or dealt with gating issues and illiquidity have largely been washed out.
30:41And so I'd say that the asset class, we've seen a high amount of demand as people say, okay, how do I think about filling this kind of defensive absolute return ballast to my portfolio? and even in a traditional barbell of saying, okay, I need something that's stable and consistent return and then I'm going to take more risk over here. And if you think about how the economy is growing, there's a massive debate on what will happen with AI and will that ultimately create a huge amount of upside? And you can see this in capital markets activity and equity capital markets. So people want to participate in the high growth part of the allocation ecosystem, but they really want something that I think has been tested through cycles on the secure and defensive part of their allocation portfolio.
31:26You talk about hedge funds having to figure things out post-financial crisis, and it feels like they've kind of come back into fashion more recently a bit, and for good reason in a number of ways. I mean, I think there's always reasons why hedge funds make sense as part of an allocation. But over maybe we're talking 10, 12 years, but allocations to private markets, strategies have grown pretty dramatically. allocations to hedge funds. Hedge funds was actually one of the largest portions of the alternative universe in terms of AUM, but has not grown as rapidly as other categories of private markets.
32:00What do you think today's private markets landscape can learn from what hedge funds went through and sorted out during that post-GFC period? I think very simply about, do you have the right aligned incentives with your client? And are you deploying capital in a way that you would want your capital to be deployed versus being overly focused on excessive growth? So there was a real consideration for a number of the best hedge funds in the world around real capacity and where they could have differentiated returns over growth. And then I would say, lastly, there needs to be a real understanding of what is being sold to the investor and is that experience going to be the experience that was sold to the investor?
32:48And so I think really what was difficult for many hedge funds over that period was even though there was a high watermark, returns became too volatile. So people would pay incentive fees in good years and then funds would draw down and potentially close and investors couldn't ever make back the high watermark. They had too many illiquid assets, inappropriate vehicles, so they had to gate investors. There's a number of things that actually rhyme. What do you think the benefit of having a multi-strat hedge fund, which is in some senses an evergreen vehicle, how do you think that prepares you for building, managing, and running evergreen vehicles more broadly?
33:29Whether or not you do that in the future is, I think, irrelevant in the context of this question, which is like a hedge fund in a sense is an evergreen vehicle. Yeah, one of the lessons that we learned was to bifurcate our public and private businesses. So instead, we offered investors an a la carte approach. And so I do think you have to think about the product design of does the end investment fit in the wrapper? And I think a lot of time has been being spent on how to create wrappers for less liquid products, which I think will continue to evolve. I believe that we'll get there and someone will be on the leading edge of that innovation.
34:04But if I think about our multi-strategy approach, we value liquidity optionality for our investors and therefore do not want to be dependent on leverage. Why are you not dependent on leverage? We've always been mindful of what can happen in levered asset classes. We have a saying, especially in credit, that it's an escalator up, elevator down return stream. You collect small wins is your interest. And if things go poorly and your recovery is tough, that can be penal. and leverage can exacerbate that. We do have a number of equity relative value strategies and arbitrage strategies, which I actually would love to talk about too.
34:42But it's one of the ways when we talk about complexity, if you're a par lender, you typically need to have leverage to get to the return stream post fees that investors are expecting. And so it becomes embedded in the nature of how you effectively invest. For us, we want to ultimately earn that return on an unlevered basis. And therefore, we have lower correlation effectively to credit and equity markets. And we've done that with a very low vol. And then we've done that in a mark to market format. I think that's one of the questions that people are asking a number of the semi-liquid structures is how do the transfer mechanics work when the loans aren't marked to par?
35:23Or am I transferring into loans that are marked a par that maybe shouldn't be marked a par. So I think that that can create vol, but we've managed through that vol on a monthly basis for decades. Do you think the current period in private markets will make more allocators move back into hedge funds? I hear you talk about this. There's a lot of the mechanics that are similar. And it's like, if you're going to have exposure through evergreen structures, maybe hedge fund structure. And again, it depends on the strategy. Every allocator is different. This is a more general question with obviously understanding that many people have specifics or views or mandates.
36:06But do you think that that will, or are you seeing flows into hedge funds increase because of what's been happening in private markets or evergreen? From an institutional basis, we're seeing a number of investors increase their absolute return or hedge fund bucket that may be coming from fixed income. It may be coming from other assets and alts. We'll see if that also happens for the wealth channel. I think there is a good amount of education that needs to be done because hedge funds aren't one thing. Absolute return is not one thing. There are many sub-strategies within that. So investors have to process and understand that component of it.
36:38But I do think that is something that is continuing to gain momentum. I want to get to what you just shared, that an absolute return hedge fund strategy or a multi-strat is not just one thing. You mentioned you do merger arb, you do both equity and credit. You have a number of different credit strategies. I think about it simply as we have two large buckets of strategies and each of these two buckets have different sub-strategies. So one is global credit, and I'll put that aside for a second. And the other is what we call relative value and arbitrage and largely expressed through equity securities.
37:10Merger arbitrage, convertible arbitrage, and equity long short. Very simply, if you think about what merger arbitrage is is company a announced it's going to be by company b and there's a deal spread so company a says i'm going to buy this company for 30 a share the stock doesn't go to 30 a share there's some general discount so if the stock's at 27 there's roughly a 10 discount to effectively that closing and then there's also a timeline that's kind of an announced closing timeline and an expected timeline for that that security to close and so we view that very much like fixed income because there's a duration and there's a yield, if we're right, about the probability weighting of what the market is predicting on what that deal spread is.
37:52And then in addition to that, if the deal breaks, meaning there's antitrust considerations, another bidder comes in, company A says, somehow I actually don't, I had a MAC clause and I can't buy company B anymore, I can't get the financing done, then you can anticipate what the stock prices will do of the respective companies. and because you're usually long one company and short another, you're not having market risk. You're isolating that deal spread and that almost looks like your recovery or severity of loss in a deal break. And so we're constantly comparing what we think we can earn in even equity relative value and equity arbitrage returns without taking directional risk relative to what we're ultimately seeing in global credit.
38:34And then in global credit, we wanna be in as many regions as possible. So we're global, we spoke about that, before. So almost half the multi-strats allocated outside of the US. And we can talk about why we have that, especially in the credit business. And then within that, we have sector risk for corporates. We have structured products. And then structured products I think about as traditional structured products being mortgages, consumer loans. And then you could also look at specialty finance, which people may think about aviation loans, maritime loans. And some of those loans become less liquid.
39:05And we also have a private asset back strategy, but we want to look at all these markets. And then you also can then look at the various different levers to getting your return in credit, whether that's par lending, whether this is pulled apart that we talked about, whether it's some of these workout situations. How do you balance that within a portfolio and think about both the risk and return with each of those types of return generators and credit? We don't farm this out to a big number of teams. We have long-tenure partners here that run a lot of these verticals. So even within credit, we have three partners that run global credit.
39:39We have a partner that runs structured products, US corporate credit, European corporate credit. We have multiple partners in some of these businesses, Asia corporate credit, and then commercial real estate and hard asset investing. And so we're regularly looking at kind of what the market is providing us. And there could be periods where we say, we're fairly certain this deal is going to close and it's implying a large spread. You better bring something in credit for marginal dollar that's going to be competitive to an ARB deal. So that regularly happens here. And then we also think about having a lot of velocity to the credit portfolio.
40:10So we regularly want to repopulate the risk, which I think is very different than what you would ultimately look at in private markets, where you're largely making an investment and you're holding it. So we want to be moving our feet. And then we built the risk infrastructure to sit and say, okay, well, we expected a 15 % gross return on this credit. The loan's traded up three points. the forward return is diluted because we captured some of those points. And so we may want to move out of that risk, even though we think it's a good credit. And so I'd say we're regularly moving our feet around how that portfolio works.
40:44And we want to make sure we have the velocity to make sure that our investors are capturing what we think is kind of the best risk at any given time. We don't want people to think that we're high frequency in the way that maybe a quant trading firm would ultimately trade. You've talked about as a firm being an investment-led firm rather than a distribution-led firm. And it's interesting too that your current managing partner is also the CIO. How does that inform how you think about investing? Is that different in your mind in terms of what it means, in terms of how you invest or express your investment views, how you think about allocating time and capital to certain opportunities versus others?
41:28We have one partner that's going through our retirement program today, but the rest of the equity is controlled by the active partners. So we're all effectively working for ourselves and the employee base of the firm. And the partners plus employees, as I said, are the largest individual investor at the firm. And so it allows us to really think about where we want to invest our dollars and how we design products that give us the appropriate flexibility to invest in a way that we ultimately think our investors will want to invest alongside us with. Some of this goes back to your original question, but our roots is as a family office.
42:01And I give a huge amount of credit to a number of the big public alt firms. I think they've built incredible franchises and businesses, but I understand the incentive structure. If you're a public company and your stock trades many times these stocks traded even north of 25 or 30 times of fee-related earnings or FRE, you want to grow into very large markets. That's the incentive. And I would say if you're a private firm that's dealing with succession or generational transfer, you want to potentially sell a portion of your firm or sell your firm at the highest multiple. And so you think about the same dynamic around FRE.
42:38We do think about this quite a bit from a capital markets perspective of where do we go into strategies and regions where we just don't have the same level of competition and we don't have to be focused on strategies that have a very high TAM. And so I think if you're at a very large firm, you kind of have two considerations. You have very specialized firms or you have firms that need to go into high TAM products. And what we want to be able to do is kind of sit in the middle where we can say, okay, if you're making the bet on the specialized firm, especially if it's a long commitment, that may no longer be attractive over a period of time.
43:16If you said, okay, I really like music royalties, there's people that are unbelievable music royalties, but what if spreads compressed in that space and you've committed to a fund and that's the only thing that they do? We have 500 people here. We have eight global offices and approximately$40 billion. We have the capacity to have enough scale to look at a wide range of strategies, but then we want the flexibility to move our feet around where we see the best relative value return across those. Do you think that the change in market structure and asset management, as you mentioned, the big firms getting bigger and having to grow in size and scale, that to some extent dictates the deals that they may do.
43:57Have you found that, But as you said, going to maybe more capacity constrained strategies, is there less competition for a lot of the deals that you're investing in given this evolution in the business of asset management? In private markets, for sure. And so, you know, I'd say if you're generally looking at bite sizes, sub$500 million, it may not move the needle for some of the really large firms. And so one of the things that I think we're quite excited about is if you don't have scale, you can't deal with restructurings and you can't deal with operating businesses. But if you're a firm that has a number of loans, you've largely originated loans.
44:39We always joke that we're not in the origination business. We're in the repayment business. And if you've originated a number of loans, you may want someone like us to take some of those loans off your hands, especially if they're the smaller loans. So if you've done a very large deal, you may go and enforce your rights and restructure and own and operate that business. But if you're looking at a$100 million loan or a smaller effective face loan, it's not going to be worth your time. And if someone shows up and says, you have the loan marked at 80 cents, I'll give you 70 cents for it. You ultimately may do that.
45:15And so that's one of the spaces I think we're quite excited about is identifying private capital structures where we like the sector, and we've executed on this, where we like the sector and we can provide a benefit to the creditor and ultimately potentially, in some cases, there is a benefit to the equity because going through that restructuring with the creditor can be quite expensive. And so if you can do something out of court and take your licks, there could be a real benefit of that as well. So I think tying the last two questions together, there's areas that you want to invest in. As you mentioned, you're the largest investor as a firm, so it's your principal.
45:56The people who are running the firm and doing the day-to-day work are your capitals being directed in places you want to invest in. I think it's a great tie-in to the Wealth Channel. You're now building out the infrastructure to work with the Wealth Channel more broadly. In a sense, you have worked with the Wealth Channel. It started out as a family office. You've worked with certain types of allocators in the Wealth Channel. And now, as the merging of OCIOs with wealth platforms, there's this kind of institutionalization of wealth platforms anyways, in a sense. And I imagine there's some overlap there.
46:32Why build a wealth-focused business? And how does that dovetail with kind of how you already thought about allocating capital on your own? I mean, you're in a sense wealth investors too, in a sense. And you're allocating your own capital that way. So we've always had wealth clients. Between the partners, employees, institutional family offices, and RIAs, it's 20 % to 25 % of our capital days. And so we've always been used to servicing a pretty wide range of clients, whether that is a large institutional sovereign wealth fund or state pension or a large family office or a set of individuals. And so we have a very wide roster in terms of client count.
47:16I was surprised when I started to look under the hood at just the number of clients we have because of our heritage. So even friends and family that have come in. And so we've always had to think about how do we deal with servicing that client base? And for a long time, I think we prided ourselves on being one of the largest hedge funds no one had ever heard of. And, you know, at a certain point, you realize like that's not a winning strategy. And we needed to be more proactive in communicating what we actually do, what our business looks like, explaining to investors what our investment strategy is.
47:48And we also realize our products are complicated. And inherently, that's one of our core parts of our DNA. And so I'll make a quick plug on our website. You can find a number of the white papers that actually Michael referenced. But we started to put pretty long-form content out around a number of our views because we wanted to take the time to unpack and not overly simplify what we think ultimately is not a trivial investment process. How do you balance that? I think you create simplicity out of complexity with the way you invest, and you almost make it look easy even if it's hard. How do you think about doing that as it relates to educating the wealth channel?
48:29One of the things that I strongly believe is that as an alts industry, it's our collective responsibility to educate the broader wealth channel if democratization of alts is to happen. And I think for a period of time, there were firms that simplified their message and made the product so easy that those were the firms that ultimately kind of garnered and gained the most share. And so I don't always believe that the simplest message is necessarily the best investment wrapper. And so I just think it's going to take time. It's going to take formats like this where people can learn about a range of options within alts itself.
49:11I spent a number of years early in my career only looking at hedge fund strategies, and there are so many sub-hedge fund strategies, yet alone thinking about private equity and venture and infrastructure and venture capital and growth equity and royalties. That's just a massive menu. And so I just think that that process is going to take a little bit of time, but it's one that we want to make sure that we're doing our part and helping people understand what that is. Do you think many allocators in the wealth space will have less allocations to private markets and or hedge funds or more over time because they want to express thematics or exposure to all these different sub strategies?
49:52I think about this simply for myself. If you look at what the S &P can deliver and if you look at what the index oriented firms have been able to do, beta is almost free. And so I think that there are many different forms of alpha that investors can use to complement their total portfolio allocation. And my general sense is that you're going to have a material growth in what alts is within wealth platforms and wealth portfolios. I do think the real question is how do you think about which one of those alts options best complements the existing exposures that you already have, whether that be public fixed income, cash, munis, and equities.
50:33And I think it's going to be inherent on all of us to kind of think through that education process as well as the conduits for people to ultimately gain that exposure. What's a complex strategy that may be less obvious to investors now or allocators now that you're very excited about? If you go back to the GFC, private credit really had three verticals and they almost were the same size. You had distressed or what is now called opportunistic. You had middle market direct lending and you had asset back finance. And over the last 15 plus years, middle market direct lending far exceeded those other two strategies.
51:14And if you think about wanting your private credit allocation to be complementary to your equity allocation, you actually want a counter-cyclical versus pro-cyclical asset class. and I would argue that middle market direct lending is pro-cyclical to private equity and much more correlated to that asset class. Oftentimes you're in a different part of the capital structure, but you're in the same businesses. Distressed inherently is counter-cyclical to that. And so that's one space that I'm excited for investors to understand more. And then similarly, I think in the asset back space, there's certain asset classes within that, whether it's consumer loans, it's going to be somewhat pro-sick, but you're often contractually kind of connected to something, some individual asset.
52:01And then you have a number of other asset classes within that space, maybe, you know, equipment finance or, you know, aviation leasing. And so you have a number of sub-asset classes there that should be less correlated as well to your equity allocation. If investors already have a lot of exposure to private equity, maybe direct lending. And as you said earlier, like the counter to that would be opportunistic credit. If you think about things through a relative value basis, for those who have exposure to private equity, private credit, is having some exposure to opportunistic credit right now a good hedge against some of the more challenging aspects of the private equity direct lending markets?
52:38We think so. But listen, I think we've tried to design that product to be all weather, but you're going to have great vintages. And we believe that this could be a very attractive time, just given some of the indigestion that we talked about in private equity and private credit. We're thrilled by kind of the pipeline of what we're seeing. We also wrote a white paper about this, but the other consideration is if you're in a drawdown fund versus an evergreen, you really need to think about your DPI profile. And so some of the statistics that we put into one of our white papers really relates to the inverse correlation of DPI and the benefits that you get from an opportunistic credit allocation on DPI relative to private equity and private credit because the situations that tend to be hard is if you're committed to dry down fund series, you want to be in multiple vintages.
53:22You don't necessarily want to take all the vintage risk. And you can think about timing things. So people may say 2026 and 2027 are great for opportunistic, and I'm not sure if that was the best thing in 2024. But if you're more programmatic, you want your DPI cycles to balance each other out to allow for you to take that vintage risk. It's not dissimilar in venture, right? And so you have a number of our institutional allocators that believe in the opportunistic credit investment philosophy and therefore do not want to be vintage dependent, even in the other vintages. And they say, okay, well, I also want it because I want to fund my continued commitments to venture capital.
53:55And your DPI cycles are more consistent and are less dependent on these kind of, you know, balloon end payments of exits. So I do think that those are, you know, factors, I think, for consideration for people. And I think something else interesting as I think about some of the things you've shared is, One is the firm has gone through three generational transitions. You're also one of the younger executives that I've interviewed in the 211 plus podcast. As you think about Davidson Kempner's growth from here, we talked about the wealth business that's growing the business of Davidson Kempner. How do you think about the vision of where Davidson Kempner is over the long run?
54:40I joke a lot that we have an old firm with young energy and a lot of enthusiasm. We've tried to keep so much of the core DNA of what made the firm successful over a long period of time, but to continue to innovate on that. And so if I think about the things that you definitively wanted to keep, we wanted to keep this focus on capital preservation and downside protection. That goes back to Marvin Davidson's roots of saying, okay, started family office, he was already wealthy, how do I compound that capital with low volatility and low correlation over a long period of time? So all our products generally have that sort of feel where we want the products to be low vol and kind of steady compounders.
55:21We often also think about how do we create some products that may complement or be diversifiers, not necessarily directly, but because we create this optionality on how we allocate. If you think about our op credit series, you're going to have some public market distress. You're going to have some credit capital solutions. You're going to have some special sits that we help, you know, we take equity risk on. You're going to have some real estate, you have some infrastructure. And so we have a number of clients that take that product and use it as like a single kind of diversifier to a prong of individual allocations.
55:56And I think over the last couple of years, we've made sure that we've evolved our product lineup and our investment capabilities to take advantage across a wider range of products. So we felt fantastic about our credit DNA in the public space. We were used to operating businesses through public distress. The asset-backed finance space, we've had a structured products business for decades now. And so how do you ultimately take advantage of current pay paper that may not be tradable, so it's less appropriate for the multi-strat? And so we saw a real pocket to build that business. We did that in 2021.
56:31one. Ultimately, we were going through these processes in primarily ABF and saying, okay, we're hiring a third party to ultimately buy the senior tranches of the debt. If you underwrite down to the MEZ or the RESID, you've underwritten the entire capital stack. Can we place that senior tranche someplace? And so, you know, we spent a lot of time on an insurance business. We've, I think, also heard the feedback from our investors. They've said, there are various different things that you do that I want kind of more direct access to. And so I think we've been mindful to say, how do we create opportunities for that sub-strategy?
57:05We have a great opportunistic real estate business that was born and built out of our multi-strategy and credit opportunity strategies. I think people are really excited about the opportunity set in commercial real estate today. I've been at the firm for eight years. So this is a collective group that's been together for a very long time and I think is quite aligned. So rather than kind of importing new capabilities in, we've said, how do we take what we already have and kind of expand the offerings of how we can make that accessible to our end clients? I think that we don't have a target on growth.
57:40We don't have a FRE target. And by the way, I think we talk about this all the time. If we're going to start a new product, we know we're going to put a lot of our own money in it. And so do we ultimately want to be in that business for a sustained period of time? And so So those are some of the trade-offs and things to consider. I think we're very pleased with what our business looks like today, but excited about what collectively we can do as Generation 3. An old firm with Young Energy, I love that way of tying everything together. I think it's clear you're so excited about the different things that you do and also the opportunity set going forward.
58:16But yet, it's steeped in history of how you operate as a firm and the firm's founding as a family office. So it's a fascinating conversation. Thanks so much, James. Thank you.
58:27Thanks for listening to this episode of Alt Goes Mainstream. I hope you enjoyed it. You can read more about alts at my substack, altgoesmainstream.substack.com. Thanks a lot and have a great day.
Welcome back to the Alt Goes Mainstream podcast.
Today’s podcast takes us to the heart of New York City to talk with James Li, the President and Partner of Davidson Kempner, a firm that was an early participant in the merger arbitrage, distressed debt, and opportunistic credit industries.
Davidson Kempner’s heritage lies in cutting through complexity to find value.
Founded in 1983, Davidson Kempner’s origins began in merger arbitrage, distressed debt, and opportunistic credit. The firm, which now has around 1,800 clients, began accepting outside capital in 1987 and has since built out its investment platform to include convertible arbitrage, long / short equities, asset-based lending, and real estate strategies.
Davidson Kempner has since grown to almost $40B in AUM across public and private markets strategies.
The firm has a penchant for navigating complex situations across public and private markets to opportunistically uncover value, noting that “no situation is too complex for [them].”
James unpacked how the firm’s family office DNA has evolved across three generations of leadership into a scaled investment platform across public and private markets to inform the firm’s relative value investing perspective.
James and I had a fascinating conversation on a number of pressing topics at the intersection of public and private markets. We covered:
Bio
James Li is the President and a Partner at Davidson Kempner. Mr. Li also co-manages the Client Partnerships & Business Development department and oversees the Firm’s Capital Markets, Strategy and Treasury Teams. He joined the Firm in 2018 and is based in the New York office.
Before joining Davidson Kempner, Mr. Li was a Managing Director in the Client Relationship Management and Strategy Group at Goldman, Sachs & Co. Mr. Li received a B.S. from Columbia University.
Thanks, James, for sharing your wisdom, expertise, and passion about public and private markets and your approach to investing in complex situations.
Show Notes
00:00 Live From Davidson Kempner’s Office in NYC
01:36 A Message from Ultimus Fund Solutions
02:37 Introduction to James Li
03:36 Career Roots At Goldman
05:16 Discovering Davidson Kempner
06:13 Three Generations Of Leadership
06:42 Family Office DNA
08:23 Investing In Complexity
10:44 Where Complexity Pays
12:20 Liquid Versus Private Feedback
13:37 Macro Shifts And Deglobalization
16:01 Finding Edge In Less Crowded Markets
17:28 Private Capital Indigestion
18:47 Capital Solutions Playbook
20:48 Building Operating Capabilities
25:59 Allocator Shift In Credit
31:26 Hedge Funds Return
32:12 Post GFC Lessons
32:48 Fees Volatility Gating
33:13 Evergreen Vehicle Design
34:04 Liquidity Over Leverage
34:15 Leverage Risk Explained
35:14 Semi Liquid Marking Issues
35:36 Flows Back To Hedge Funds
36:26 Wealth Channel Education
37:14 Merger Arb Basics
38:34 Global Credit Toolkit
39:18 Portfolio Velocity Risk
40:58 Investment-Led Ownership
43:43 Scale Competition Edge
44:28 Restructuring Repayment Focus
45:43 Building Wealth Business
54:07 Firm Vision And DNA
A Word from Our Sponsor, Ultimus
This episode of Alt Goes Mainstream is brought to you by Ultimus, the full-service fund administrator and transfer agent powering asset managers in private and public markets. As alts go mainstream, you need real expertise to handle complex fund structures, connect with key distribution partners, and handle sophisticated compliance, reporting, and transparency demands.
That’s Ultimus: high-tech, high-touch solutions for over 450 clients and 2,500 funds with $775B in assets under administration. Backed by an expert team of over 1,200 employees, they place client service at the core of their business, helping you navigate complexity during your fund structuring or launch and then supporting you through every stage of growth. Whether you’re already in the market or thinking about entering private wealth, you can trust their team’s deep expertise in retail alternatives to help you reach your goals.
Learn more at ultimusfundsolutions.com or email [email protected].
We thank Ultimus for their support of alts going mainstream.
Editing and post-production work for this episode was provided by The Podcast Consultant.